15 Big Rules and Changes Taking Effect in October 2026
October 2026 is an important month for taxpayers, businesses and professionals from the perspective of income tax, GST, banking and financial compliance. Several new provisions are taking effect this month, while a number of important compliance activities also require attention.
One of the key developments is the extension of the tax-audit and income-tax return deadlines. Meanwhile, the GST sector is preparing for the 57th GST Council meeting, and businesses should also begin their preparation for the FY 2025-26 annual GST return.
Beyond taxation, taxpayers should also take note of changes concerning property purchases from NRIs, UPI charges, EPF, NPS, bank withdrawals, fixed deposits and digital banking records.
Here are the major October 2026 updates that taxpayers and businesses should keep in mind.
1. Tax Audit Due Date Extended to 21 October 2026
A major update for taxpayers and tax professionals is the extension of the tax-audit report deadline for Assessment Year 2026-27.
Through CBDT Circular No. 07/2026 dated 28 September 2026, the due date for furnishing the tax-audit report has been extended from 30 September 2026 to 21 October 2026 for taxpayers falling within the relevant category specified under Explanation 2 to Section 139(1) of the Income-tax Act, 1961.
The related deadline for filing the Income Tax Return has also been shifted from 31 October 2026 to 21 November 2026.
Who can avail of this extension?
It is important to understand that this extension is not applicable universally to every taxpayer or every type of audit report.
In general, the extended timeline applies to taxpayers belonging to the category where the normal ITR due date was 31 October 2026, including:
- Companies required to get their accounts audited and which do not fall under transfer-pricing provisions.
- Non-company taxpayers whose accounts are subject to audit under the Income-tax Act or another applicable law, subject to the prescribed conditions.
- Firms, LLPs and other entities covered by the relevant tax-audit provisions.
- Partners of firms whose accounts are required to be audited, wherever the applicable conditions are fulfilled.
- Other taxpayers falling within the relevant category under Explanation 2 to Section 139(1).
A key distinction is transfer pricing. Taxpayers covered by Section 92E follow a separate compliance schedule and are not covered by this particular extension. Their applicable reporting and return deadlines continue according to the transfer-pricing provisions.
What happens to Form 10B and Form 10BB?
Charitable and religious trusts and institutions should also examine the impact of the extended deadline.
Form 10B is the audit report applicable to specified charitable or religious trusts and institutions. Form 10BB applies to other eligible cases. These forms are required to be furnished within the specified timeline linked to Section 44AB.
Accordingly, where the trust or institution falls within the category covered by the revised specified date, the applicable Form 10B or Form 10BB deadline will also move to 21 October 2026.
This should, however, not be confused with Form 10BD.
Form 10BD follows a separate deadline
Form 10BD relates to the statement of donations received by specified charitable institutions. Its normal due date is 31 May immediately following the financial year in which the donations are received.
Therefore, the October tax-audit extension does not change the Form 10BD due date to 21 October.
In summary:
| Compliance | October 2026 deadline/status |
|---|---|
| Tax Audit Report – eligible audit cases | 21 October 2026 |
| ITR – eligible audit cases | 21 November 2026 |
| Form 10B – eligible cases | 21 October 2026, where linked to the specified date |
| Form 10BB – applicable cases | 21 October 2026, where applicable |
| Form 10BD | Not covered by the extension; normal due date is 31 May |
| Form 3CEB – Transfer Pricing Report | Not covered by this extension |
2. ITR Due Date for Eligible Audit Cases Moved to 21 November
The extension of the tax-audit deadline has also resulted in additional time for filing the Income Tax Return for eligible taxpayers.
The revised deadline has changed from:
31 October 2026 → 21 November 2026
This provides additional time to taxpayers and professionals to complete the audit process, finalise financial statements and file the corresponding income-tax return.
However, taxpayers should remember that this is not a general extension applicable to everyone. Non-audit taxpayers and taxpayers covered by transfer-pricing provisions continue to follow their respective statutory deadlines.
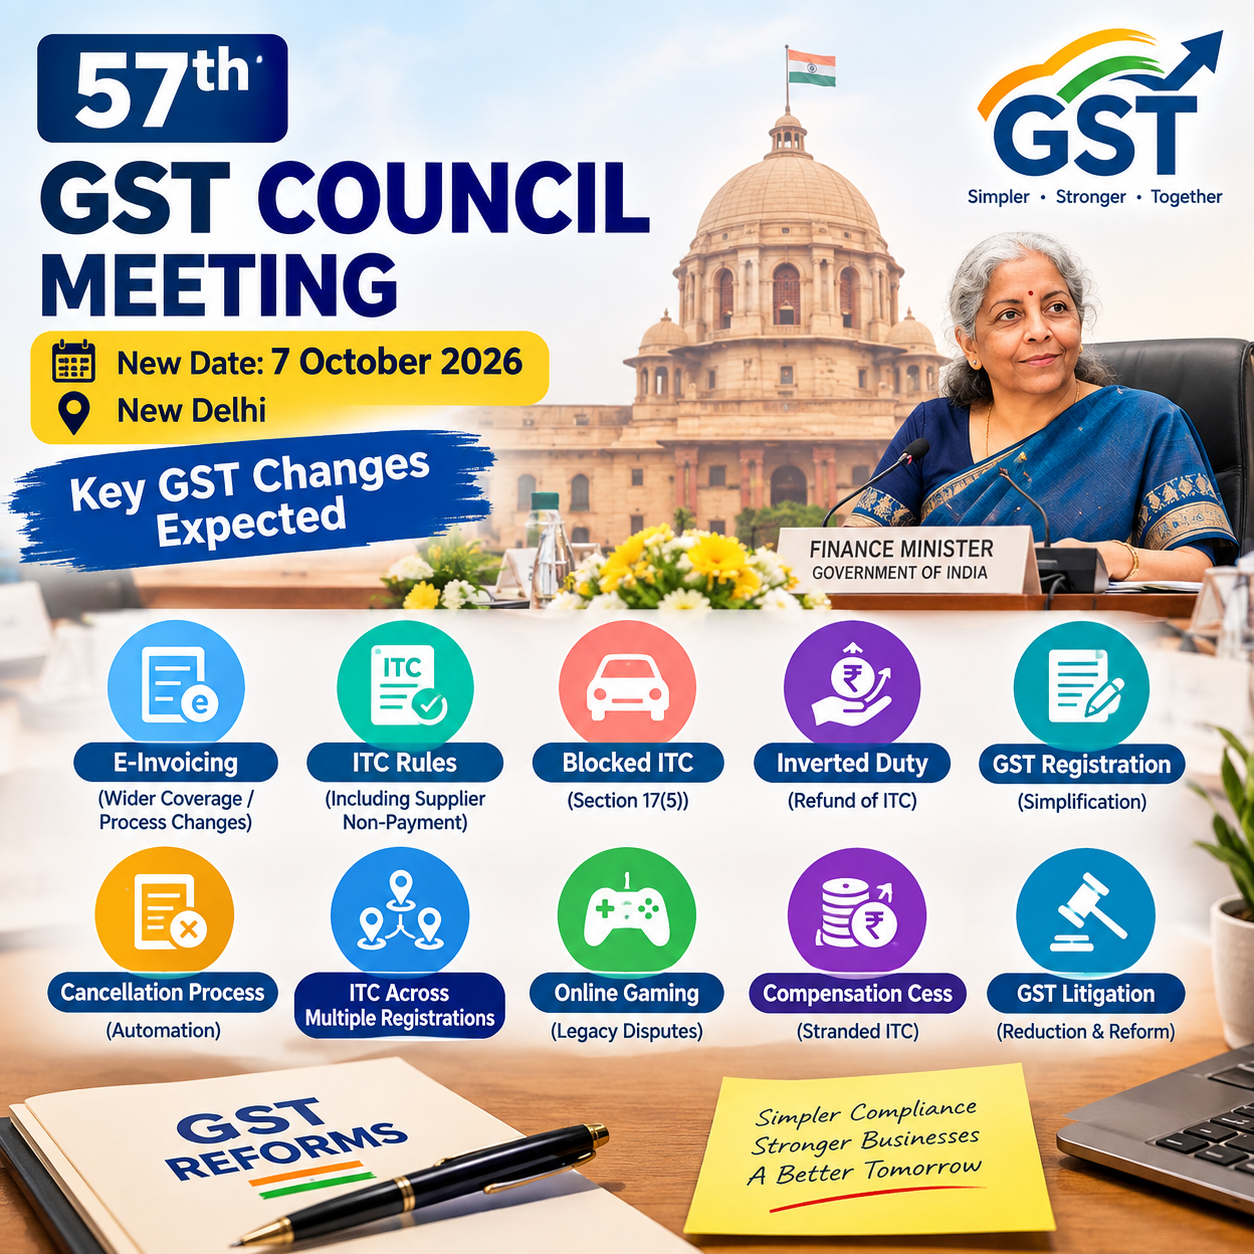
3. 57th GST Council Meeting Scheduled for 7 October 2026
The 57th GST Council meeting, scheduled for 7 October 2026, is another significant development to watch during October.
The meeting is relevant for businesses, taxpayers and GST professionals because various matters concerning GST administration, compliance procedures and taxpayer facilitation may come up for discussion.
However, there is an important distinction between a proposal or recommendation discussed by the GST Council and an actual amendment in GST law.
A GST Council recommendation does not automatically make a new GST rate, rule or compliance requirement effective. Businesses should wait for the relevant notification, circular, amendment or other legal communication before making changes to their accounting and GST compliance processes.
4. Preparation for GSTR-9 and GSTR-9C for FY 2025-26
October is also an important period for businesses to start preparing for their annual GST return for FY 2025-26.
Based on the previous year’s GSTN process, annual-return forms such as GSTR-9 and GSTR-9C are expected to become available during the October period.
Businesses should therefore begin their reconciliation work well before the December deadline instead of waiting until the last month.
Key areas that should be reconciled include:
- Books of accounts with GSTR-1
- GSTR-1 with GSTR-3B
- ITC recorded in books with ITC claimed in GSTR-3B
- ITC with GSTR-2B
- Reverse Charge Mechanism transactions
- Credit and debit notes
- Amendments reported in later periods
- HSN/SAC details
- Exempt, nil-rated and non-GST supplies
- Refunds and outstanding demands
For FY 2025-26, the annual-return filing deadline is 31 December 2026, subject to the applicable provisions and any subsequent notification. Current professional guidance also refers to the ₹2 crore threshold for GSTR-9 and ₹5 crore threshold for GSTR-9C.
Practical approach: Businesses should use October to start the GSTR-9/9C reconciliation process rather than postponing the exercise until December.
5. New TDS Compliance for Property Purchase from an NRI
From 1 October 2026, an important compliance change applies to certain property transactions involving a non-resident seller.
When a resident individual or HUF purchases an immovable property from an NRI, the buyer-side TDS compliance process is being modified so that the buyer does not have to obtain a TAN solely for this specified TDS compliance.
Under the revised mechanism, PAN-based reporting and the prescribed form, including Form 141, become important.
It is important to understand that the removal of the TAN requirement does not mean that the TDS obligation has been abolished.
Anyone purchasing property from an NRI should therefore verify the following before completing the transaction:
- Whether the seller qualifies as a resident or non-resident.
- Whether TDS is applicable under the relevant provision.
- The correct TDS rate applicable to the transaction.
- PAN details of both parties.
- The reporting and prescribed-form requirements applicable from 1 October 2026.
Property transactions involving NRI sellers require particular care because incorrect TDS compliance can result in interest, fees and other tax-related consequences.
6. EPF Wage Ceiling Revised
Another important development concerns the EPF wage ceiling.
The wage ceiling has been increased from ₹15,000 to ₹25,000, effective from 17 September 2026. As a result, employers may need to consider the revised limit while handling October payroll and the related ECR compliance process.
Employers should review their payroll systems and verify employee eligibility, contribution calculations and ECR information before completing the applicable monthly filing.
7. Revised Charges for NPS Services
NPS subscribers should also take note of the updated charges applicable to various NPS services from October 2026.
The changes may be particularly relevant when opening a new NPS account or reviewing the charges associated with services provided through Points of Presence and other intermediaries.
Subscribers should remember that charges may vary between PoP-based NPS accounts and direct/e-NPS channels. The applicable cost depends on the account-opening and service route.
Therefore, users should refer to the applicable PFRDA/NPS charge structure for their specific account instead of relying only on the headline charge.
8. Disclosure of Interest Rates on Bulk Fixed Deposits
Another banking-related change concerns bulk fixed deposits.
Under the revised framework, banks are required to publish the applicable interest rates for bulk deposits on their websites.
This requirement is more relevant to large depositors, companies and institutions than to individuals holding smaller fixed deposits.
Businesses, trusts and other organisations with significant deposits should therefore check the bank’s published bulk-deposit rates before making a fresh deposit or renewing an existing large deposit.
9. SBI BSBD Accounts: Revised Cash Withdrawal Charges
SBI’s revised service-charge provisions for Basic Savings Bank Deposit (BSBD) accounts are also relevant during October.
Under the revised arrangement, BSBD customers are entitled to a specified number of free cash withdrawals. Charges may apply once the permitted free limit has been exceeded.
The reported revised fee is ₹15 plus applicable GST per transaction after the free withdrawal limit.
Customers who make frequent cash withdrawals should check the free transaction limit applicable to their account and refer to the latest SBI service-charge schedule.
10. Revised SBI ATM Transaction Limits
SBI customers should also review the ATM transaction limits applicable from October 2026.
For certain salary-account customers using ATMs belonging to other banks, the number of free transactions is being revised.
After the applicable free limit is exhausted, charges may be imposed on both financial and non-financial transactions, depending on the nature of the transaction and the relevant service-charge rules.
Customers who regularly use other-bank ATMs should therefore verify their applicable free limit rather than assuming that the previous limit remains unchanged.
11. UPI Merchant Transactions and MDR Changes
Another significant payment-related development involves UPI merchant transactions.
Under the reported changes, merchant transactions above the specified threshold may attract MDR under the revised framework from 15 October 2026.
MDR is primarily a cost associated with merchant payment acceptance. It should not be treated as a general fee imposed on normal person-to-person UPI transfers.
Businesses accepting UPI payments should therefore examine the charges applicable through their acquiring bank or payment service provider and assess the potential impact on transaction costs.
Before making changes to customer pricing or accounting treatment, businesses should verify the final applicable regulatory and implementation instructions.
12. LPG Subsidy and Aadhaar-Based Authentication
Consumers who receive LPG subsidy benefits should ensure that their Aadhaar authentication or e-KYC requirements have been completed wherever applicable.
Those who have already completed the required authentication generally do not need to repeat the process simply because October has begun.
Consumers who have not yet completed the applicable authentication should check the latest instructions issued by their LPG provider to avoid any disruption to eligible subsidy benefits.
13. Greater Recognition of Digital Banking Records
Changes concerning the legal framework for bankers’ books and banking records are also relevant to the financial sector.
From October 2026, the framework provides recognition to electronic, digital and certain cloud-based banking records, subject to the applicable prescribed conditions.
The development reflects the increasing shift from traditional physical banking records to digitally maintained information.
For businesses, it also highlights the importance of maintaining accurate electronic records, proper audit trails and dependable data backups.
14. Updated Process for Delayed Birth and Death Registration
The procedure for delayed registration of births and deaths is also undergoing changes.
Under the revised framework, the authority required to approve a delayed registration can vary depending on the length of the delay.
Therefore, applicants should not assume that the same authority or approval procedure applies to every delayed registration case.
The relevant authority, documents and approval process should be confirmed according to the specific period by which the registration has been delayed.
15. October TDS/TCS Compliance Requirements
October is also an important compliance month for TDS and TCS deductors and collectors, particularly in relation to quarterly compliance for the second quarter.
Businesses should ensure that they have:
- Deducted TDS correctly.
- Properly matched and accounted for challans.
- Verified PAN details.
- Filed applicable TDS/TCS statements within the prescribed time.
- Initiated corrections promptly wherever errors are identified.
- Reconciled Form 26AS, AIS and other relevant records wherever required.
As tax compliance continues to become increasingly digital, businesses should also maintain the underlying supporting documents and records in an organised manner.
16. MCA and Annual Corporate Filing Requirements
October can also be an important compliance period for companies and LLPs, depending on their financial year, AGM date and applicable statutory filing timelines.
Companies should review whether they need to complete filings or compliances such as:
- AOC-4
- MGT-7 / MGT-7A
- MSME-related reporting
- Director-related compliances
- Auditor-related filings
- Other applicable event-based MCA forms
There is no common October deadline that applies to every company. The actual due date depends on the entity’s AGM date, financial year and individual statutory circumstances.
Companies should therefore maintain an entity-specific MCA compliance calendar instead of relying on a standard October deadline.
Key October 2026 Dates at a Glance
| Date | Important update |
|---|---|
| 1 October 2026 | Various banking, NPS, property-TDS and other compliance changes take effect |
| 7 October 2026 | 57th GST Council Meeting |
| October 2026 | Expected period for GSTR-9 and GSTR-9C availability/preparation for FY 2025-26 |
| 15 October 2026 | UPI merchant MDR-related implementation |
| 21 October 2026 | Extended tax-audit/reporting deadline for eligible taxpayers |
| 21 November 2026 | Extended ITR filing deadline for eligible audit cases |
| 31 December 2026 | FY 2025-26 annual GST return deadline, subject to applicable provisions |
What Should Businesses and Taxpayers Do in October 2026?
October should be viewed not only as a month in which several new provisions take effect, but also as an important preparation period for upcoming compliance deadlines.
Businesses should first determine whether they actually fall within the category eligible for the 21 October tax-audit deadline. Companies, firms, LLPs, trusts, societies and other entities should examine their applicable statutory provisions and return category rather than assuming that the extension automatically applies to them.
Charitable and religious institutions should separately verify their Form 10B or Form 10BB requirements. These should not be confused with Form 10BD, which follows a separate due-date mechanism.
GST-registered businesses should also begin their FY 2025-26 GSTR-9 and GSTR-9C reconciliation once the relevant forms are available on the GST portal. Starting early can help businesses identify discrepancies between books of accounts, GSTR-1, GSTR-3B and input-tax-credit records and resolve them before the annual-return deadline.
Businesses should additionally review October payroll changes, NPS charges, banking service fees, UPI merchant costs and NRI property TDS requirements wherever these are relevant to their operations.
Taking these steps early can help taxpayers and businesses organise their documentation, identify applicable changes and avoid last-minute compliance issues.