57th GST Council Meeting: 10 Major Tax Reforms and Important GST Announcements

57th GST Council Meeting: 10 Major GST Decisions and Key Compliance Reforms

The 57th GST Council Meeting, conducted in New Delhi on 8 October 2026, primarily focused on simplifying GST administration, improving processing speed, and expanding the use of technology in tax compliance. Rather than introducing changes to GST rates, the Council concentrated on procedural and administrative reforms relating to registration, return filing, refunds, Input Tax Credit (ITC), litigation, registration cancellation, e-commerce, exports, and transportation of goods. According to the meeting’s outcome note, no GST rate revisions were announced. The Council also decided that rate-related issues would be considered annually at a separate meeting dedicated exclusively to GST rates.

The reforms follow a year of implementation of the two-rate structure. During this period, taxable supplies and GST collections increased, while the effective tax rate on domestic supplies declined. The Council reported that monthly taxable supplies rose from ₹40.19 lakh crore to ₹50.58 lakh crore, while supplies reported to consumers increased from ₹5.98 lakh crore to ₹7.58 lakh crore. Gross tax liability also recorded growth, whereas the effective tax rate on domestic supplies decreased from 14.55% to 13.13%. The overall observation was that tax rates declined while the tax base expanded.

1. GST Registration Process to Become Simpler and More Automated

A key area of reform is the GST registration system. Currently, applications identified as low-risk, along with applications where output tax on supplies to registered persons does not exceed ₹2.5 lakh per month, can receive system-based registration within three working days without direct intervention by a tax officer. The Council stated that approximately 61% of GST registrations are already processed through this automated mechanism, while the remaining applications are examined by officers.

Under the proposed improvements, the registration portal will become more intuitive and applicant-friendly. It will display only the fields relevant to the applicant and identify the documents required for each specific purpose.

The Council has also approved automatic processing of selected registration amendment applications. Between November 2025 and September 2026, approximately 16.73 lakh amendment applications were submitted, of which 65.45% concerned changes such as trade names, directors’ or partners’ details, and addresses of additional places of business. These specified categories will now be eligible for automatic acceptance.

These changes are intended to reduce manual verification, simplify applications, and speed up routine registration-related procedures.

2. GST Return Filing to Improve Buyer-Seller Data Matching

The Council has proposed further integration between supplier-reported transactions and the Input Tax Credit claimed by buyers. It observed that approximately 95,000 system-generated notices are issued annually because of differences between GST returns. However, the recovery against these notices represents only around 0.08% of the amount involved, suggesting that many discrepancies arise from reporting or data-entry errors.

Under the proposed mechanism, adjustments made by a supplier to previously reported sales will be communicated through the sales statement, enabling the corresponding buyer to account for the change in the original transaction. Taxpayers will also be allowed to correct certain details relating to earlier periods, including an incorrectly entered buyer GST registration number.

The Invoice Management System (IMS) will play an important role in reconciling these transactions. The buyer’s accepted position will flow into the relevant return, helping align supplier reporting with the buyer’s ITC records.

The proposed framework represents a move towards invoice-level reconciliation, reducing avoidable mismatches and improving coordination between buyers and suppliers.

3. GST Refunds to Be Processed More Quickly Through Automation

Improving the refund mechanism is another significant objective of the Council’s recommendations. The time permitted for issuing an acknowledgement of a refund application is proposed to be reduced from 15 days to 10 days. If neither an acknowledgement nor a deficiency memo is issued within this period, the application will be treated as acknowledged.

The Council has also proposed a risk-based refund system under which 90% of the claimed refund amount may be sanctioned through automated processing, subject to the prescribed risk assessment. The refund order is proposed to be issued within three working days of acknowledgement, compared with the existing seven-day period referred to in the outcome note.

Additionally, refunds relating to excess balances in the Electronic Cash Ledger are proposed to be processed automatically without requiring officer intervention.

The proposed system will also reduce repetitive data entry. Relevant shipping details will be obtained from Customs records, while payment information will be sourced from banking systems. This integration is expected to simplify refund applications and reduce administrative delays.

4. Important Proposed Changes in Input Tax Credit

The 57th GST Council Meeting has recommended several changes concerning Input Tax Credit. The proposals include allowing ITC on health and life insurance policies taken for employees, as well as on telecommunication towers and pipelines installed outside factory premises.

Credit is also proposed to be allowed on free samples and on stock written off due to the expiry of its shelf life where the applicable law requires the goods to be destroyed.

Another important proposal concerns services that are purchased and resupplied within the same business line. The Council has indicated that such transactions should not result in the same service being taxed twice because the credit chain is interrupted.

Examples discussed include hotel accommodation costing up to ₹7,500 per night booked through an agent, restaurant and catering services, and passenger transportation. In certain cases, these services were taxed at 5% without ITC, which restricted the flow of credit between businesses.

The proposed changes aim to restore the credit chain in eligible transactions and reduce tax-related distortions in service industries.

5. Inverted Duty Structure Refunds to Include Input Services and Plant & Machinery

The Council has proposed expanding the refund mechanism applicable to an inverted duty structure. Under the earlier framework described in the outcome note, refunds were restricted to tax attributable to input goods.

The proposed amendment will allow refunds relating to tax paid on input services under the inverted duty structure for ITC availed on or after 1 November 2026.

The restriction relating to tax paid on plant and machinery is also proposed to be removed. In such cases, the eligible refund would be calculated at one-sixtieth of the relevant credit for each month, reflecting the working life of the asset. This provision is proposed to apply to ITC availed on or after 1 April 2027.

These measures could help businesses manage accumulated credits and improve working capital availability, particularly in industries such as pharmaceuticals and fast-moving consumer goods (FMCG).

6. GST Litigation Procedures to Follow a Standardised Framework

The Council has proposed a more uniform approach to GST litigation and adjudication. The standard framework is expected to cover the issuance and service of notices, pre-notice communications, the grounds for alleging fraud, hearing procedures, and the preparation of adjudication orders.

Another important proposal is the introduction of a monetary threshold for issuing notices. Under the recommendation, no notice would be issued where the tax amount involved is below ₹10,000.

The objective is to reduce unnecessary disputes and avoid spending disproportionate administrative resources on matters involving relatively small amounts.

Standardised procedures could also improve consistency in the handling of GST disputes across different jurisdictions.

7. Proposed Relief in GST Arrest, Prosecution, and General Penalties

The Council’s outcome note contains important recommendations concerning GST enforcement and penalties. It states that the power of arrest under GST is proposed to be removed.

The prosecution threshold is also proposed to increase from ₹1 crore to ₹5 crore. In addition, the minimum punishment is proposed to be removed, allowing the court to determine whether a fine, imprisonment, or both would be appropriate in an individual case.

The general penalty applicable when no specific penalty is prescribed is proposed to be reduced from ₹25,000 to ₹10,000.

The Council has emphasised a more proportionate approach to compliance failures. Delayed return filing, reporting mistakes, or payment defaults would continue to attract the applicable recovery provisions, interest, and proportionate penalties, rather than additional punitive consequences beyond the relevant legal framework.

The broader objective is to use technology and invoice-level information to identify mismatches and potentially fraudulent ITC claims. The Council’s approach places greater emphasis on detecting irregularities through data analysis rather than relying primarily on deterrent enforcement measures.

8. E-Way Bill Checks and Physical Inspection of Goods in Transit

The Council has proposed changes to the procedure for physically inspecting goods transported under the GST framework.

Under the proposed system, a vehicle may be stopped for inspection only when specific intelligence is available. Prior authorisation from an officer holding a rank not below Joint Commissioner would also be required.

The proposal further restricts inspection powers to the originating State and the destination State. States through which the goods merely transit would not be permitted to stop the vehicle for inspection under the proposed framework.

For instance, if a consignment travels through five States before reaching its destination, physical verification would generally be limited to the State from which the goods originate and the State where they are delivered, rather than permitting routine checks in every intervening State.

E-Way Bills and other prescribed documents would continue to be required, and their details would remain subject to system-based verification. The principal change is that physical inspection would be linked to specific information or intelligence rather than conducted routinely without such a basis.

9. Simplified GST Registration Cancellation and a Proposed Scheme for Small Businesses

The Council has recommended an automated and phased approach to GST registration cancellation and business closure, beginning with smaller taxpayers.

Under the proposed framework, filing the final return would become part of the registration closure application instead of being treated as a separate subsequent step.

Where a GST registration has been suspended or cancelled because of a pending return or missing bank account details, the system is proposed to restore the registration once the taxpayer fulfils the outstanding requirement.

The Council has also granted in-principle approval for an optional compliance scheme for small taxpayers with turnover of up to ₹5 crore who make supplies exclusively to consumers. Under the proposed arrangement, eligible taxpayers would file returns annually while paying tax quarterly.

However, the detailed framework and the necessary legal amendments are expected to be presented at the next Council meeting. Therefore, this proposal should be understood as an in-principle decision rather than an operational filing facility currently available to taxpayers.

10. Key Reforms for Service Exports and E-Commerce Businesses

The meeting also addressed GST-related issues affecting exporters of services and sellers operating through e-commerce platforms.

Changes concerning export of services

An Indian business providing services to a foreign customer through its own overseas branch is proposed to become eligible for export benefits, subject to the applicable conditions and the removal of the restriction identified in the outcome note.

This proposal may be relevant to analytics companies, design businesses, engineering consultants, and Indian offices of international organisations.

The Council has also proposed treating services performed in India on goods belonging to a foreign customer as exports of services, even when the goods do not physically leave India. Examples include testing, repairs, certification, research, and processing activities.

The objective is to improve the tax treatment of these transactions and make India more competitive as a destination for contract processing and specialised services.

Changes concerning e-commerce sellers

Small sellers using e-commerce platforms may receive greater flexibility in managing GST registrations across States.

Under the proposal, a seller could declare an electronic commerce operator’s warehouse located in another State as the seller’s Principal Place of Business in that State, subject to the operator’s consent. This consent is proposed to be obtained automatically through the system.

The seller would still need to maintain a physical presence in at least one State, and the registration in the additional State would be restricted to supplies made through the relevant platforms.

The Council has also proposed a consistent tax treatment for similar services offered through different platform business models. Differences in contractual arrangements have led to varying interpretations of the same provisions. Under the proposed approach, the tax treatment would be determined by the actual service supplied, ensuring that comparable services receive comparable tax treatment regardless of how a platform structures the transaction.

No GST Rate Revision in the 57th GST Council Meeting

A key takeaway from the meeting is that no GST rate changes were announced at the 57th GST Council Meeting.

Instead, the discussions focused on resolving operational difficulties, removing inconsistencies, and addressing ambiguities that remained after the previous year’s rate-related changes.

The Council has decided to consider GST rate matters once a year at a dedicated meeting. This approach is intended to separate rate-related decisions from discussions concerning GST administration and compliance procedures.

Consequently, businesses should distinguish between the procedural reforms proposed at this meeting and changes to the tax rates applicable to goods and services. The emphasis was on improving how the GST system functions in practice, including registration, return filing, refunds, ITC claims, business closure, transportation, exports, and dispute resolution.

How Will the 57th GST Council Meeting Affect Taxpayers?

The recommendations indicate a move towards a more automated, technology-enabled, and risk-based GST compliance framework.

The principal implications for businesses include:

  • Registration: Greater automation and faster processing of eligible applications.
  • Return filing: Improved coordination between supplier declarations and buyer ITC claims.
  • Refunds: Shorter acknowledgement timelines and increased system-based processing.
  • Input Tax Credit: Proposed changes affecting selected insurance, infrastructure, sample, stock, and service transactions.
  • Litigation: More standardised procedures and a proposed monetary threshold for notices.
  • Enforcement: Proposed changes to arrest, prosecution, and general penalty provisions.
  • Transportation: Greater reliance on specific intelligence before conducting physical inspections.
  • Business closure: A more integrated registration cancellation process.
  • Small taxpayers: A proposed optional annual return scheme with quarterly tax payments for eligible businesses.
  • Exports and e-commerce: Proposed clarifications intended to simplify selected cross-border service and platform-based transactions.

For businesses, the key message is that GST compliance is gradually moving away from repetitive manual procedures towards data matching, risk-based assessments, and automated decision-making.

However, taxpayers should carefully distinguish between recommendations announced by the Council and provisions that have become legally effective. Some proposals require detailed rules, system modifications, notifications, or legislative amendments before they can be implemented.

In conclusion, the 57th GST Council Meeting represents a significant step towards GST process reform rather than another round of rate revisions. Its broader objective is to make compliance more convenient for businesses while strengthening the tax administration’s ability to identify discrepancies through technology and invoice-level information.

The proposed measures aim to address the remaining inconsistencies and ambiguities in GST administration and advance the principles underlying GST 2.0, with a greater emphasis on simplification, transparency, automation, and proportionate enforcement.
RBI EDF Rules Change from October 2026: Important Update for Freelancers & Content Creators

New RBI EDF Rules Effective from 1 October 2026 for Freelancers, YouTubers & Influencers

A major regulatory update has become applicable from 1 October 2026 for individuals and businesses in India earning income from overseas service transactions.

The Reserve Bank of India (RBI) has introduced the Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026, replacing the previous FEMA framework governing exports. The new Regulations came into effect on 1 October 2026.

One of the key changes under the new framework is the introduction of a common Export Declaration Form (EDF) mechanism covering exports of goods, services and software.

This change is especially relevant to:

  • Freelancers
  • Consultants
  • Content creators
  • YouTubers
  • Social-media influencers
  • Digital marketing professionals
  • Graphic and web designers
  • Agencies
  • IT and software service providers
  • Other professionals supplying services to clients or recipients located overseas

For service exporters operating from the Domestic Tariff Area (DTA), the Authorised Dealer (AD) bank is the designated authority for services other than software. For software exports, the framework also provides for AD banks/STPI in the DTA, while separate provisions apply to SEZs.


1. What is the Major Change from 1 October 2026?

The earlier FEMA framework generally allowed exports of services to be carried out without an export declaration where none of the prescribed declaration forms was applicable.

The position has changed under the 2026 Regulations.

As per Regulation 3(2), an exporter of services is required to furnish an Export Declaration Form (EDF) declaring the amount representing the full export value of the services.

Accordingly, individuals and businesses receiving payments from overseas for genuine service exports should review whether their transactions are covered by the new FEMA reporting requirements.

Important Clarification

EDF is not a GST return or GST form.

It is an export declaration under FEMA/RBI regulations and operates separately from GST returns, GST invoices, LUT requirements and income-tax compliance.


2. Which Service Providers May Come Under EDF Compliance?

The new requirement may be relevant to several categories of professionals and businesses providing services to overseas recipients.

Freelancers

A freelancer based in India who provides services such as programming, graphic design, consulting, writing, advertising, marketing or similar professional services to a foreign client may be carrying out an export of services.

YouTubers and Content Creators

Digital creators may also need to evaluate the new rules where they receive payments connected with overseas entities or platforms.

Possible arrangements may involve:

  • YouTube or Google
  • Meta
  • Upwork
  • Fiverr
  • International customers or clients
  • Other overseas platforms

However, receiving money from a foreign source alone does not automatically mean that the receipt qualifies as an export of services.

The actual agreement, nature of the service, identity and location of the recipient and applicable place-of-supply rules must be considered.


3. What Qualifies as an Export of Service under GST?

The FEMA requirement should not be confused with the GST definition of export of services.

Under Section 2(6) of the IGST Act, a service is treated as an export of service when the prescribed conditions are fulfilled.

These include:

  1. The service provider is located in India.
  2. The recipient is located outside India.
  3. The place of supply is outside India.
  4. Payment is received in convertible foreign exchange, subject to the applicable legal provisions.
  5. The supplier and recipient are not merely establishments of the same person.

These conditions are also reflected in CBIC’s official GST guidance.

Therefore, simply receiving a payment in dollars, pounds or another foreign currency does not automatically establish that the transaction is an export of service for GST purposes.

The transaction must be tested against all applicable conditions.


4. Who Receives the EDF?

For service exporters located in the Domestic Tariff Area (DTA), the designated authority for services other than software is the Authorised Dealer (AD) bank.

An AD bank is a bank authorised under FEMA to undertake specified foreign-exchange transactions.

Consequently, freelancers, consultants, creators and other service exporters receiving overseas payments should coordinate with the AD bank through which their export proceeds are processed.

The actual submission process may differ between banks. Depending on the bank, EDF filing may be handled through an online banking portal, email-based process or another prescribed mechanism.

Therefore, exporters should confirm the exact procedure with their respective AD bank rather than assuming that every bank follows an identical filing method.


5. What is the EDF Filing Deadline?

The filing timeline is an important aspect of the new compliance framework.

The 2026 Regulations state that the EDF is required to be furnished within 30 days from the end of the month in which the invoice for services was raised.

Example

Suppose a freelancer raises service invoices during October 2026.

The applicable monthly deadline would generally be:

30 November 2026

This means the calculation is not simply 30 days from the date of each individual invoice.

Understanding this distinction can help service exporters organise their monthly FEMA compliance properly.


6. Can Multiple Service Invoices Be Reported Through One EDF?

Yes.

The new framework provides an option to submit a single EDF covering services exported during a month to one or more recipients.

This can make the reporting process more convenient for professionals who issue several export invoices during the month.

Example

Suppose a content creator has the following invoices during October 2026:

Overseas Recipient Invoice No. Amount
Google/Overseas Entity INV-101 USD 1,000
Meta/Overseas Entity INV-102 USD 700
Foreign Client INV-103 USD 500

Subject to the transaction-specific requirements and the AD bank’s process, these service exports may be reported through one monthly EDF.

The EDF includes relevant invoice-level details for the services being declared.


7. Alternative Filing Option for Non-Software Services

The Regulations also provide an important alternative for services other than software.

In such cases, the exporter may furnish the EDF on or before the date on which the payment is received.

Therefore, service exporters should consider the applicable filing route based on their transaction structure and coordinate with their AD bank to ensure that the declaration is submitted correctly and within the prescribed timeline.


Standard Filing Route

Invoice issued during a month → EDF to be filed within 30 days after the end of that month

Alternative Route for Non-Software Services

EDF may be submitted on or before the date the payment is received

This alternative provides additional flexibility to exporters of services other than software.


8. Can the EDF Deadline Be Extended by the Bank?

Yes.

The Authorised Dealer (AD) bank has the authority to extend the time limit for submitting an EDF when the exporter requests an extension and explains the reasons for the delay.

The bank must be satisfied that the reasons provided by the exporter are reasonable before granting the extension.

Therefore, where a genuine delay occurs, the exporter should approach the AD bank and request appropriate relief instead of leaving the EDF compliance pending.


9. What Details Need to Be Reported in the EDF?

The EDF requires detailed information about the export transaction. It is not limited to reporting the amount received from the overseas customer.

The form generally captures information such as:

  • Nature/type of export
  • AD code
  • Importer Exporter Code (IEC)
  • GSTIN
  • PAN
  • Name and address of the exporter
  • Details of the AD bank
  • Method of realisation
  • Recipient or consignee details
  • Third-party payment information, wherever applicable
  • Description of the goods or services
  • Total export value

For service exports, additional information may include:

  • Name and address of the recipient
  • Country of the recipient
  • Invoice number
  • Invoice date
  • Currency
  • Invoice value
  • Net realisable value
  • Contract number and date, wherever applicable
  • Description of services
  • SAC code
  • Relevant remarks

Because the EDF requires invoice and transaction-level information, exporters should maintain accurate invoices, contracts and payment records.


10. What Records Should YouTubers and Content Creators Keep?

Creators receiving income from overseas sources should maintain sufficient documentation to establish the nature and flow of the transaction.

1. Contract or Agreement

Keep the agreement, platform terms or other documentation identifying the relevant contracting party or overseas recipient.

2. Payment Reports

Download and retain statements, payment reports or remittance confirmations provided by the platform or client.

3. Export Invoice

Raise and preserve the relevant invoice for the services supplied.

4. Bank Records

Maintain bank statements and foreign-remittance documents showing receipt of the export proceeds.

5. EDF Copy

Keep a copy or acknowledgement of the EDF submitted to the AD bank.

6. GST Documentation

Where GST registration applies, maintain export invoices, LUT documents and relevant GST return records.

A well-maintained documentation trail should ideally look like:

Agreement → Invoice → EDF → Foreign Remittance → Bank Statement → GST Records


11. The Payment Country Does Not Always Identify the Service Recipient

One practical issue that service exporters should understand is that the country from which a payment is received may not necessarily be the country or entity of the actual contractual recipient.

For instance, an international platform may have one entity as the contracting party while the payment is processed through another group company, payment centre or jurisdiction.

Therefore, exporters should not identify the recipient merely by looking at the location from which the bank payment originated.

Instead, review:

  • Contract/agreement
  • Platform payment statement
  • Invoice
  • Actual recipient or contracting entity
  • Payment arrangement

The key principle is:

The source of the remittance should not automatically be treated as the identity of the service recipient.

The entire transaction structure should be examined before reporting the details in GST and FEMA records.


Export Proceeds Realisation Period Has Also Been Revised

Another important change effective from 1 October 2026 concerns the period within which export proceeds must generally be realised and repatriated.

Under the amended Regulation 5, export proceeds relating to services, including software, are generally required to be realised and repatriated within:

9 months from the date of invoice

For exports invoiced or settled in Indian Rupees, the applicable period is generally:

12 months

This remains subject to the conditions and requirements prescribed under the applicable regulatory framework.

The September 2026 amendment reduced the earlier 15-month period to 9 months, with the revised provision becoming effective from 1 October 2026.

Realisation Period at a Glance

Category of Export General Realisation Period
Services and software 9 months from invoice date
Exports invoiced/settled in INR 12 months
Goods Generally 9 months from shipment
Goods supplied to an overseas warehouse 9 months from sale from the warehouse
Project exports Based on applicable contractual payment terms

Where circumstances justify additional time, an exporter may approach the AD bank for an extension, subject to the applicable conditions and approval process.


GST Compliance Still Applies Separately

The introduction of the RBI EDF mechanism does not eliminate or replace GST requirements.

A service provider exporting services must separately determine whether the transaction satisfies the GST conditions for export and whether registration, LUT and refund provisions apply.

Under Section 16 of the IGST Act, exports of services are treated as zero-rated supplies.

Subject to the applicable conditions, a registered exporter may generally choose to:

  • Export services under LUT/bond without payment of IGST and claim an eligible refund of accumulated ITC; or
  • Export services after paying IGST and claim the applicable refund.

GST Registration for Exporters

GST registration should be examined separately from FEMA/EDF compliance.

CBIC guidance indicates that a person whose outward supplies consist entirely of exports may need GST registration to claim refunds because exports are treated as zero-rated supplies.

For service providers, the general GST registration threshold is ₹20 lakh, subject to applicable exceptions and the lower threshold prescribed for specified special-category States.

Therefore, exporters should assess their individual circumstances instead of assuming that receiving foreign payments automatically removes the need for GST registration.


LUT for Exporting Services Without IGST

A registered exporter who intends to supply services without payment of IGST will generally need to make the export under a valid Letter of Undertaking (LUT), subject to the applicable GST rules and conditions.

This allows eligible exports to be made without charging IGST, with the possibility of claiming a refund of eligible accumulated input tax credit.

Therefore, exporters should keep their compliance chain properly coordinated:

GST Registration → LUT → Export Invoice → GST Return → EDF → Bank Realisation


Export Invoices Must Contain the Required Details

Export invoices issued by registered persons should comply with the applicable GST invoice requirements.

Depending on the method of export, the invoice should contain the appropriate endorsement, such as:

“SUPPLY MEANT FOR EXPORT UNDER BOND OR LETTER OF UNDERTAKING WITHOUT PAYMENT OF IGST”

or the relevant endorsement applicable when IGST is paid.

The invoice should also contain the prescribed information relating to the supplier, recipient, invoice number and date, description of services, country and other applicable particulars.

Proper invoice preparation is important because the same information may need to be reflected consistently across GST, FEMA and banking records.


Reconcile FEMA and GST Records

Maintaining consistency between different compliance records will become increasingly important.

For example, assume a service exporter issues export invoices worth:

₹10 lakh during October 2026

The following records should be capable of being matched:

  • Export invoices
  • GST returns
  • EDF
  • Bank remittance records
  • Accounting books

Since the EDF captures invoice-level information and SAC details for service exports, maintaining a consolidated export-reconciliation statement can simplify the compliance process.


Example: Income Earned by a YouTube Creator

Consider a creator based in India who receives payments from an overseas entity for content-related or other qualifying services.

Step 1 – Determine the Recipient

Review the agreement, platform documentation and payment statement to establish the actual overseas contracting/recipient entity.

Step 2 – Issue the Invoice

Prepare the appropriate invoice containing the required service and recipient information.

Step 3 – Review GST Requirements

Check whether the transaction meets the conditions for export of services and determine the applicable GST registration and LUT requirements.

Step 4 – Prepare the EDF

Report the relevant transaction through the EDF applicable to the relevant month.

Step 5 – File Through the AD Bank

Submit the EDF using the process specified by the relevant Authorised Dealer bank.

Step 6 – Receive the Export Proceeds

Ensure that the payment is received through the appropriate banking channel and properly recorded.

Step 7 – Reconcile the Records

Match the transaction across:

Invoice ↔ EDF ↔ Bank Credit ↔ GST Records


Example: Creator Using Multiple Overseas Platforms

Suppose an Indian creator earns service-related income during October 2026 from:

  • YouTube
  • Meta
  • Upwork
  • A direct overseas customer

Where the individual transactions qualify as service exports, the new FEMA framework allows one EDF to cover services exported during the month to one or more recipients, subject to the applicable requirements.

The EDF will still require the relevant invoice- and recipient-level details.

Therefore, exporters should not automatically assume that a separate EDF must be prepared for every individual invoice.


What Should Service Exporters Do Now?

Service exporters should consider taking the following practical steps:

✔ Review Overseas Receipts

Identify all payments received from foreign clients, platforms and entities.

✔ Establish the Actual Recipient

Check the underlying agreement and supporting documents instead of relying solely on the country from which the payment was received.

✔ Verify Export-of-Service Conditions

Review the GST definition of export of services and applicable place-of-supply rules.

✔ Review GST Registration

Check turnover, registration requirements and refund eligibility.

✔ Maintain a Valid LUT

Where applicable, ensure LUT requirements are completed before exporting services without payment of IGST.

✔ Issue Accurate Invoices

Ensure that invoice information is consistent with GST and FEMA requirements.

✔ Coordinate With the AD Bank

Contact the Authorised Dealer bank and understand its EDF filing procedure and documentation requirements.

✔ Prepare Monthly EDF Data

Maintain invoice-wise information every month so that EDF filing can be completed within the prescribed timeline.

✔ Reconcile All Records

Regularly match invoices, EDF details, GST returns, accounting records and bank receipts.


Final Takeaway

The introduction of the EDF requirement for service exports from 1 October 2026 is an important FEMA compliance development for professionals and businesses receiving overseas service income.

Freelancers, consultants, YouTubers, influencers, designers, digital marketers, agencies and other service providers should review whether their transactions fall within the new reporting framework.

However, RBI/FEMA compliance and GST compliance remain separate obligations. A foreign payment should therefore be reviewed from both the FEMA and GST perspectives.

The practical compliance flow can be summarised as:

Overseas Income → Identify the Actual Recipient → Issue Proper Invoice → Review GST/LUT → File EDF → Receive Export Proceeds → Reconcile Bank, GST & FEMA Records

Key EDF Deadlines to Remember

Normal route:
Invoice raised during the month → EDF within 30 days from the end of that month

Alternative route for services other than software:
EDF on or before receipt of payment

The important point is that the normal deadline is calculated with reference to the end of the month in which the service invoice is raised, rather than simply counting 30 days from the individual invoice date.

With the new framework, maintaining accurate contracts, invoices, EDF records, GST documents and banking records will be essential for smooth FEMA and tax compliance.

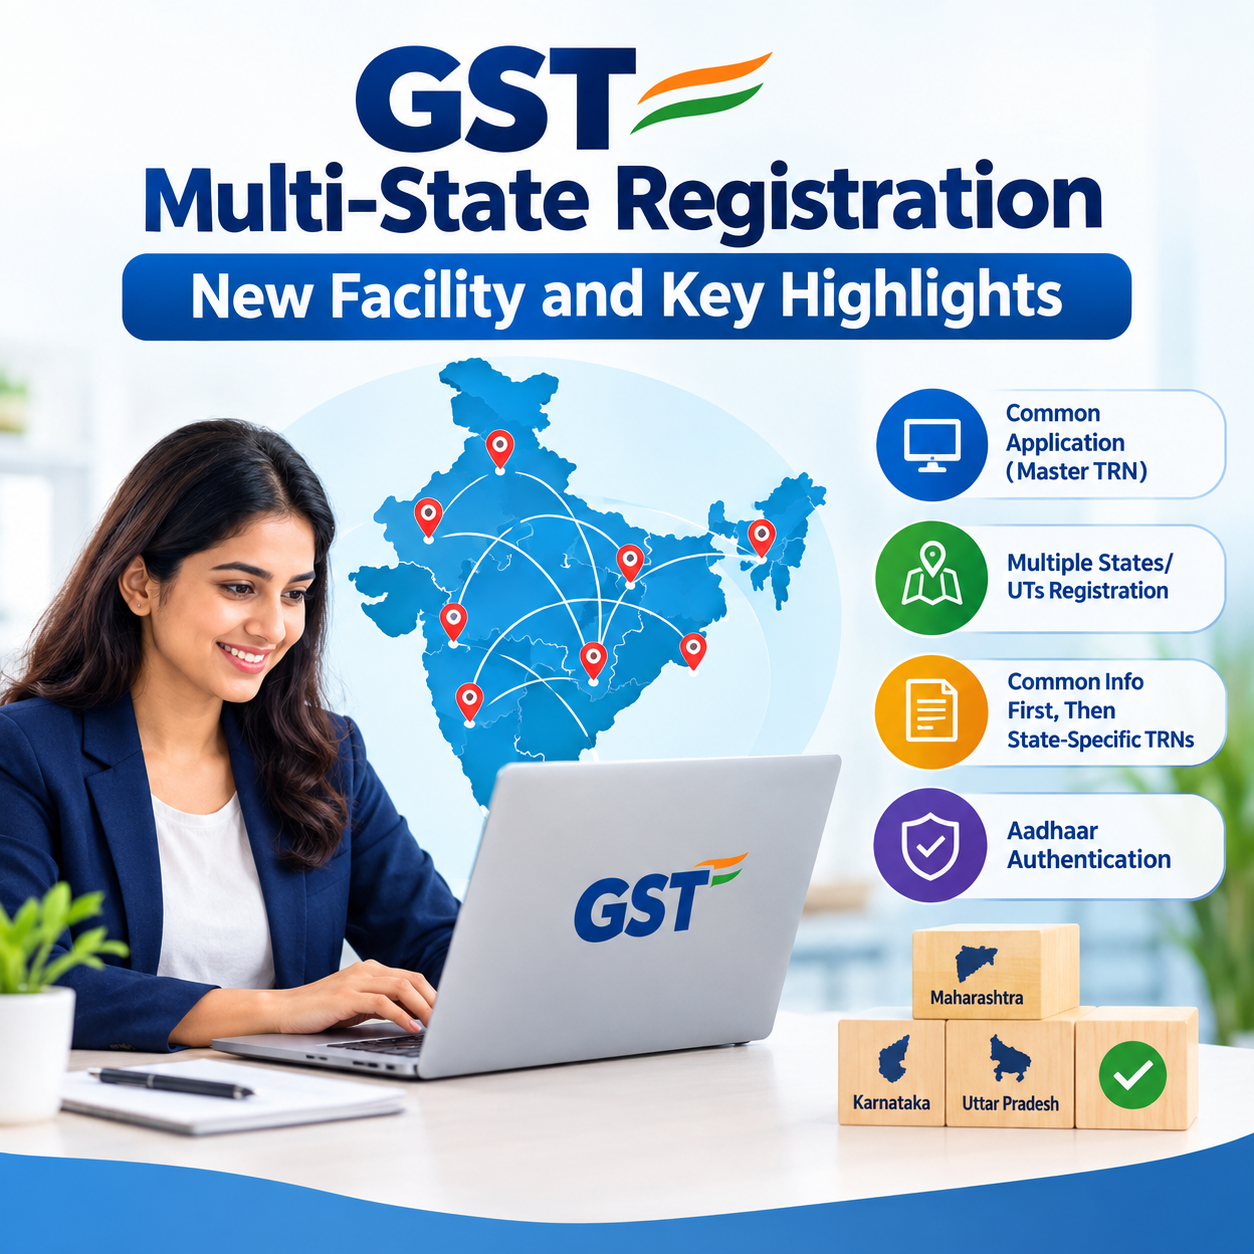
New GST Multi-State Registration Facility: Key Details

GSTN launches a new facility for GST registration across multiple States/UTs

Facility introduced from: 1 October 2026

GST registration has become more convenient for businesses that operate or plan to operate in multiple States and Union Territories.

GSTN has introduced a new “Multistate Registration” functionality on the GST Common Portal. This facility allows taxpayers having the same PAN to start GST registration applications for multiple States/UTs through a single process, eliminating the need to repeatedly enter common registration information for each State.

At present, the facility is available only to Normal Taxpayers.

The new functionality aims to simplify the registration process by reducing duplicate data entry and making it easier for businesses with operations in multiple States and Union Territories to complete their GST registrations.

What Is the New Multistate GST Registration Facility?

The GST Common Portal has introduced a new “Multistate Registration” facility for taxpayers who need GST registration in more than one State or Union Territory.

Under this facility, applicants can select all the required States/UTs together instead of initiating completely separate registration processes from the beginning for each State.

The applicant first enters the common details through a Master Temporary Reference Number (Master TRN).

After the common registration information is submitted, the GST portal creates separate State-specific TRNs for each selected State/UT.

This helps eliminate the need to repeatedly enter the same basic information for every State registration application.


Who Is Eligible to Use This Facility?

The Multistate Registration functionality is intended for taxpayers who:

  • Need GST registration in multiple States or Union Territories;
  • Have the same PAN for all the registrations; and
  • Are registered or applying as a Normal Taxpayer.

According to the GSTN advisory, the functionality is currently available specifically for Normal Taxpayers.

Therefore, it should not be understood as a registration facility currently available to every category of taxpayer.


Where Can Applicants Find the New Multistate Registration Option?

A dedicated “Multistate Registration” option has been added to the GST Common Portal homepage.

Using this option, an applicant can choose the States and/or Union Territories where GST registration is required.

Once the required locations are selected, the portal generates a Master Temporary Reference Number (Master TRN).

This Master TRN is then used to provide the common registration details applicable to the selected registrations.


What Does Master TRN Mean?

The Master TRN (Temporary Reference Number) is generated after the applicant selects the States/UTs for which GST registration is required.

It serves as the initial reference for entering and submitting the Common Registration Information (CRI) for all the selected locations.

As a result, the applicant does not need to enter the same basic information separately at the initial stage of every State registration application.

This common-data approach is one of the key advantages of the new Multistate Registration facility.


What Is Common Registration Information (CRI)?

After receiving the Master TRN, the applicant can enter the Common Registration Information (CRI).

The GSTN advisory includes various common details, such as:

1. Business Information

Details concerning the business and its basic constitution are provided at this stage.

2. Promoter or Partner Details

Information relating to promoters or partners can be included in the common registration details.

3. Authorised Signatory Details

Details of the authorised signatory are also captured as part of the common information.

4. Authorised Representative

Where applicable, information relating to the authorised representative can also be provided.

5. Goods and Services

Details of the goods and services supplied or dealt with by the business are included in the common registration information.

The major benefit is that these common details are entered once instead of being repeatedly entered for every State.


Master TRN Must Be Submitted Within 15 Days

One important requirement under the GSTN advisory is that the Master TRN must be submitted within 15 days.

Simply generating the Master TRN does not mean that the GST registration process has been completed.

The applicant must use the Master TRN to provide and submit the Common Registration Information within the specified 15-day period.

Practical Tip

Businesses should keep the necessary information and supporting documents ready before starting the Multistate Registration process.

Generating a Master TRN without completing the common information within the prescribed period could result in unnecessary delays.


What Happens After the Common Information Is Submitted?

The major benefit of the new facility becomes visible after the Common Registration Information (CRI) is successfully submitted.

Once the CRI is submitted through the Master TRN, the GST portal generates separate TRNs for each State/UT selected by the applicant.

For example, assume a business requires GST registration in:

Delhi + Haryana + Maharashtra + Karnataka

The applicant can select all four locations through the Multistate Registration option.

The process will broadly work as follows:

Master TRN is generated

↓

Common Registration Information is entered and submitted

↓

Individual State-specific TRNs are generated

↓

Separate State registration applications are completed

Therefore, the applicant does not need to repeat the entire registration process independently from the beginning for every State.


Which Details Are Auto-Populated in State Applications?

Once the State-specific TRNs are generated, the common information submitted through the CRI is automatically populated in the respective State registration applications.

Importantly, the GSTN advisory clarifies that this information remains editable.

Applicants should therefore carefully review the pre-filled information and make corrections or modifications wherever required before submitting the individual State applications.


What Details Need to Be Entered Separately for Each State?

The Multistate Registration facility does not eliminate the need to provide State-specific information.

After the common details are carried forward, the applicant must complete the information applicable to each individual State/UT.

This includes:

Principal Place of Business (PPoB)

Details of the Principal Place of Business applicable to the particular State registration must be provided.

Additional Place of Business (APoB)

Where applicable, the applicant must enter details of the Additional Place of Business for that State.

State-Specific Details

Any other information specifically required for the relevant State/UT registration must also be furnished.

Aadhaar Authentication

Where applicable, the required Aadhaar authentication process must be completed separately for the respective registration application.


Does Multistate Registration Mean One GSTIN for Multiple States?

No.

The new facility does not create a single GST registration number that covers multiple States.

Instead, it simplifies the GST registration application process.

The applicant enters common information once through the Master TRN, after which that information is carried forward into the respective State applications.

Each State/UT will continue to have its own GST registration and applicable State-specific requirements.

In short, the new Multistate Registration facility makes applying for GST registrations across multiple States more convenient by reducing repetitive data entry while retaining separate State-wise registration requirements.

Master TRN vs State-Specific TRN

The new GST Multistate Registration process becomes easier to understand when the roles of the Master TRN and State-Specific TRN are separated.

Particulars Master TRN State-Specific TRN
Role Starts the common registration procedure Used to complete registration for a particular State/UT
Generated when After the applicant selects multiple States/UTs After the Common Registration Information (CRI) is submitted
Common details Common information is provided through it Common information is pre-filled
PPoB Not provided at the common stage Must be provided for the relevant State
APoB Not provided at the common stage Required wherever applicable
State-specific details Not required at this stage Must be furnished
Aadhaar authentication Forms part of the complete registration procedure Completed for the relevant State application, wherever applicable

In short, the Master TRN serves as the common entry point, while the State-Specific TRNs allow the applicant to proceed with registration separately for each selected State or Union Territory.


Key Benefit: Less Repetition in Data Entry

The biggest advantage of the Multistate Registration facility is that it helps businesses avoid entering identical information multiple times.

Previously, a business requiring GST registrations in several States generally had to complete separate applications and provide common business information repeatedly.

For businesses operating in many States, this could involve entering the same details again and again, including:

  • Business information;
  • Promoter or partner details;
  • Authorised signatory information;
  • Authorised representative details; and
  • Goods and services information.

Under the new system, the common details are submitted through the Common Registration Information (CRI) at the initial stage.

That information is then carried forward to the respective State applications, making the registration procedure more convenient and efficient.


Does the Facility Provide a Single GSTIN for Multiple States?

No.

The introduction of Multistate Registration does not mean that a business will receive one GSTIN covering all its States.

The facility is designed to allow taxpayers to start applications for multiple State/UT registrations through a common process.

Once the Master TRN and CRI stages are completed, separate State-specific TRNs are generated. The applicant must then complete the registration requirements for each individual State or Union Territory.

Therefore, the facility simplifies the registration application workflow, but the State-wise GST registration structure continues to remain in place.


Multistate Registration: Step-by-Step Example

Consider a company named ABC Private Limited that has the same PAN and requires GST registration in:

Haryana, Delhi, Maharashtra and Karnataka.

The process would broadly work as follows.

Step 1 – Select the States

ABC Private Limited opens the Multistate Registration option on the GST Common Portal and selects Haryana, Delhi, Maharashtra and Karnataka.

Step 2 – Obtain the Master TRN

After the States are selected, the portal generates a Master TRN.

Step 3 – Provide Common Details

The applicant uses the Master TRN to submit the Common Registration Information.

The common information may include:

  • Business details;
  • Promoter/director/partner information, as applicable;
  • Authorised signatory details;
  • Authorised representative details, wherever applicable; and
  • Goods and services details.

Step 4 – Submit the Master TRN

The Master TRN has to be submitted within the prescribed 15-day period.

Step 5 – Generate State-Specific TRNs

After submission of the CRI, the portal creates individual TRNs for the selected States:

  • Haryana
  • Delhi
  • Maharashtra
  • Karnataka

Step 6 – Complete Each State Application

The common information is carried forward and auto-populated in the respective State applications.

The applicant then completes the remaining State-level requirements, such as:

  • Principal Place of Business;
  • Additional Place of Business, where applicable;
  • State-specific information; and
  • Aadhaar authentication, wherever required.

Thus, the common registration information does not have to be entered from scratch for every State.


Who Can Benefit From the New Facility?

The Multistate Registration functionality can be particularly helpful for businesses that have operations spread across different parts of India.

Examples include businesses with:

  • Multiple branches;
  • Warehouses in different States;
  • Manufacturing plants in different locations;
  • Offices across various States;
  • Distribution or supply networks; and
  • Several State-wise business establishments.

Such businesses may require multiple GST registrations.

The ability to provide common registration information once can reduce the administrative effort involved in preparing multiple applications.


Which Information Still Has to Be Provided Separately?

The new facility does not remove State-specific requirements.

Even after the common information has been submitted, the applicant must complete the information relevant to each individual State or Union Territory.

The State-level information includes:

Principal Place of Business

The applicant must provide the PPoB details applicable to the particular State registration.

Additional Place of Business

Where relevant, APoB details must also be furnished for that State.

State-Specific Information

Any information specifically required for the relevant State/UT must be completed separately.

Aadhaar Authentication

Where applicable, the required Aadhaar authentication must be completed as part of the respective State registration application.

For example, if a company operates warehouses in both Haryana and Maharashtra, the applicable location details for Haryana and Maharashtra will still need to be entered separately.


How Can Tax Professionals Use This Facility?

The new functionality can also be useful for CAs, GST consultants and tax professionals managing multiple registrations for their clients.

Instead of preparing every application independently from the beginning, the work can be divided into common and State-specific information.

Stage 1 – Common Data Preparation

The professional can first collect and verify:

  • Business details;
  • Promoter/partner details;
  • Authorised signatory information;
  • Authorised representative information; and
  • Goods and services details.

Stage 2 – State-Wise Data Preparation

Separate State-level information can then be arranged for:

  • PPoB;
  • APoB;
  • State-specific requirements; and
  • Applicable Aadhaar authentication.

This two-stage approach can make the registration exercise more structured and reduce duplicate data entry.


Important Things to Keep in Mind

Taxpayers should consider the following points before starting the Multistate Registration process.

1. Currently Applicable to Normal Taxpayers

As stated in the GSTN advisory, the functionality is presently available for Normal Taxpayers.

2. Same PAN Is Required

The facility is designed for obtaining multiple State/UT registrations under the same PAN.

3. Master TRN Is Not the Final Registration

Generating the Master TRN does not mean that GST registration has been completed.

The applicant must submit the CRI and subsequently finish the individual State applications.

4. 15-Day Requirement

The Master TRN must be submitted within 15 days as prescribed under the functionality.

5. State-Level Details Continue

PPoB, APoB, State-specific information and applicable Aadhaar authentication still need to be completed for the respective State applications.

6. Common Data Is Auto-Populated

After the CRI is submitted, the common registration information is automatically carried into the individual State applications.

7. Pre-Filled Information Can Be Modified

The auto-populated information is editable. Applicants should therefore check the details carefully and make corrections wherever necessary before submitting the State application.


How Does Multistate Registration Make GST Compliance Easier?

The main purpose of the new functionality is to minimise duplicate information entry.

For businesses seeking GST registrations across multiple States, entering identical details separately can take additional time and may create inconsistencies between applications.

With the new process, common information can be submitted once and subsequently used in the selected State/UT applications.

This can make the registration procedure more organised, especially for businesses that are expanding their operations across multiple States.


Conclusion

The new Multistate Registration facility introduced on the GST Common Portal provides a more streamlined approach for taxpayers who need GST registrations in multiple States or Union Territories.

The process begins with the selection of the required States/UTs, following which a Master TRN is generated. Through this Master TRN, the applicant submits the Common Registration Information, covering common details such as business information, promoters/partners, authorised signatory, authorised representative and goods/services.

After the CRI is submitted, the portal generates individual State-Specific TRNs. The common information is then auto-populated into the respective State applications.

However, applicants must still complete State-specific requirements, including Principal Place of Business, Additional Place of Business, State-specific information and applicable Aadhaar authentication.

Therefore, Multistate Registration does not replace separate GST registrations for individual States. Its main purpose is to make the application process faster and easier by reducing repetitive entry of common information.

For businesses with a presence across several States, as well as professionals managing multiple GST registrations, this functionality can help create a more efficient registration workflow.

In Simple Terms

Select States/UTs → Generate Master TRN → Submit Common Information → Generate State TRNs → Complete Individual State Applications

The facility is currently available for Normal Taxpayers, and taxpayers should refer to the latest GST Common Portal instructions while using the functionality.

Source: GSTN Advisory on the “Multistate Registration” Facility for GST Registration, dated 1 October 2026.