57th GST Council Meeting: 10 Major Tax Reforms and Important GST Announcements

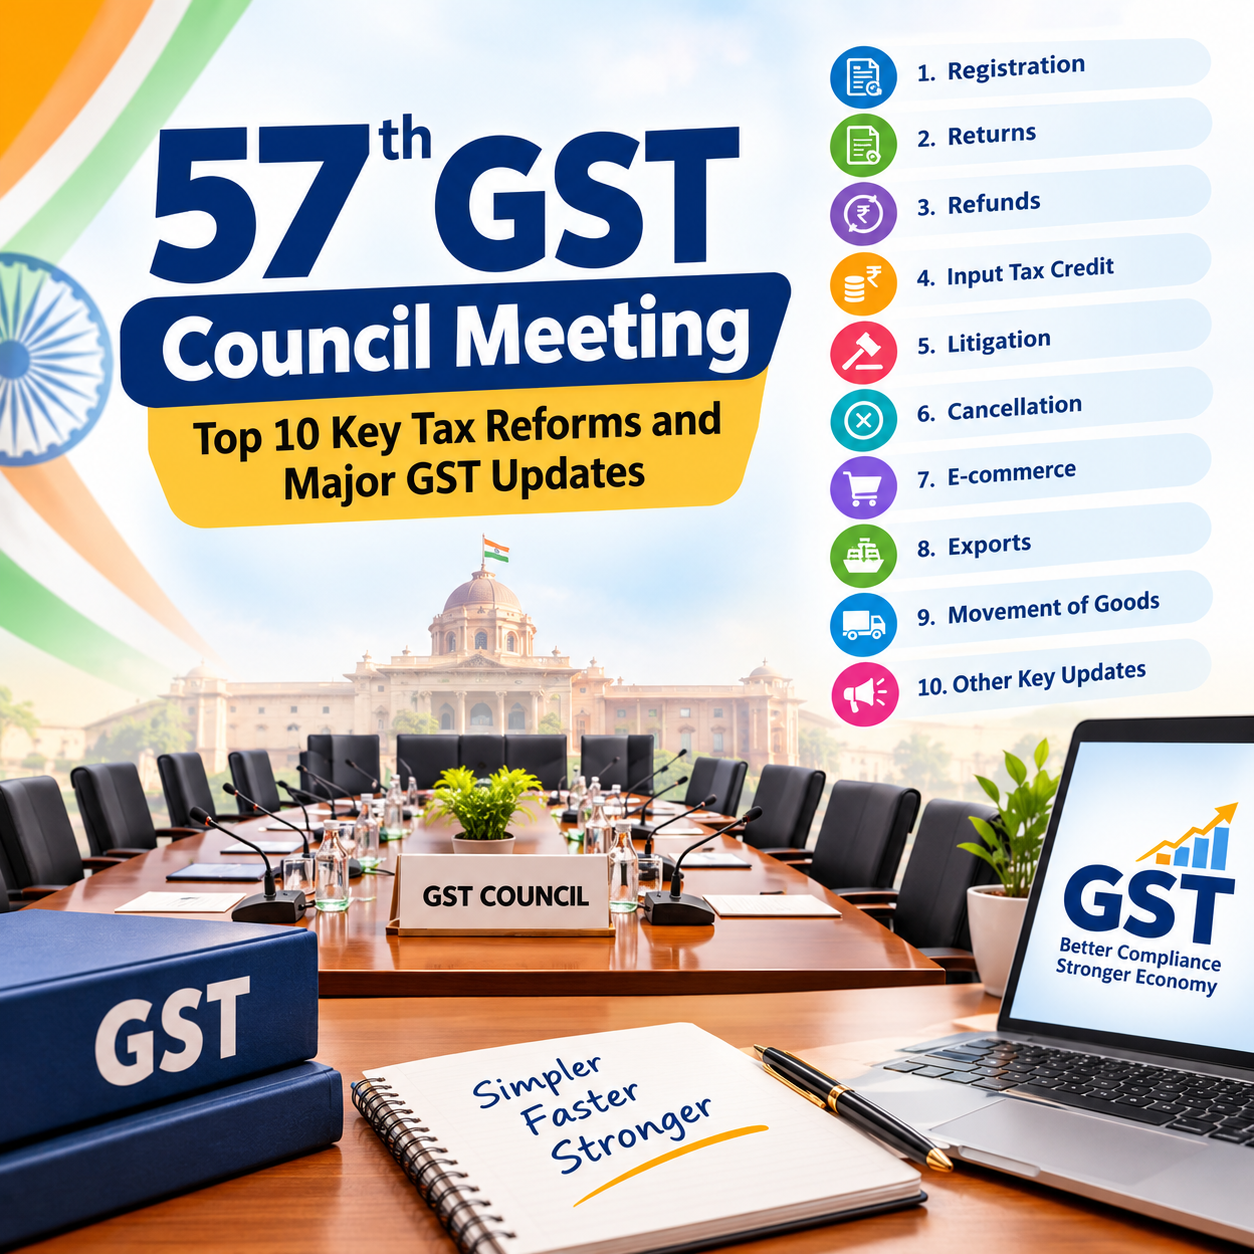
57th GST Council Meeting: 10 Major GST Decisions and Key Compliance Reforms

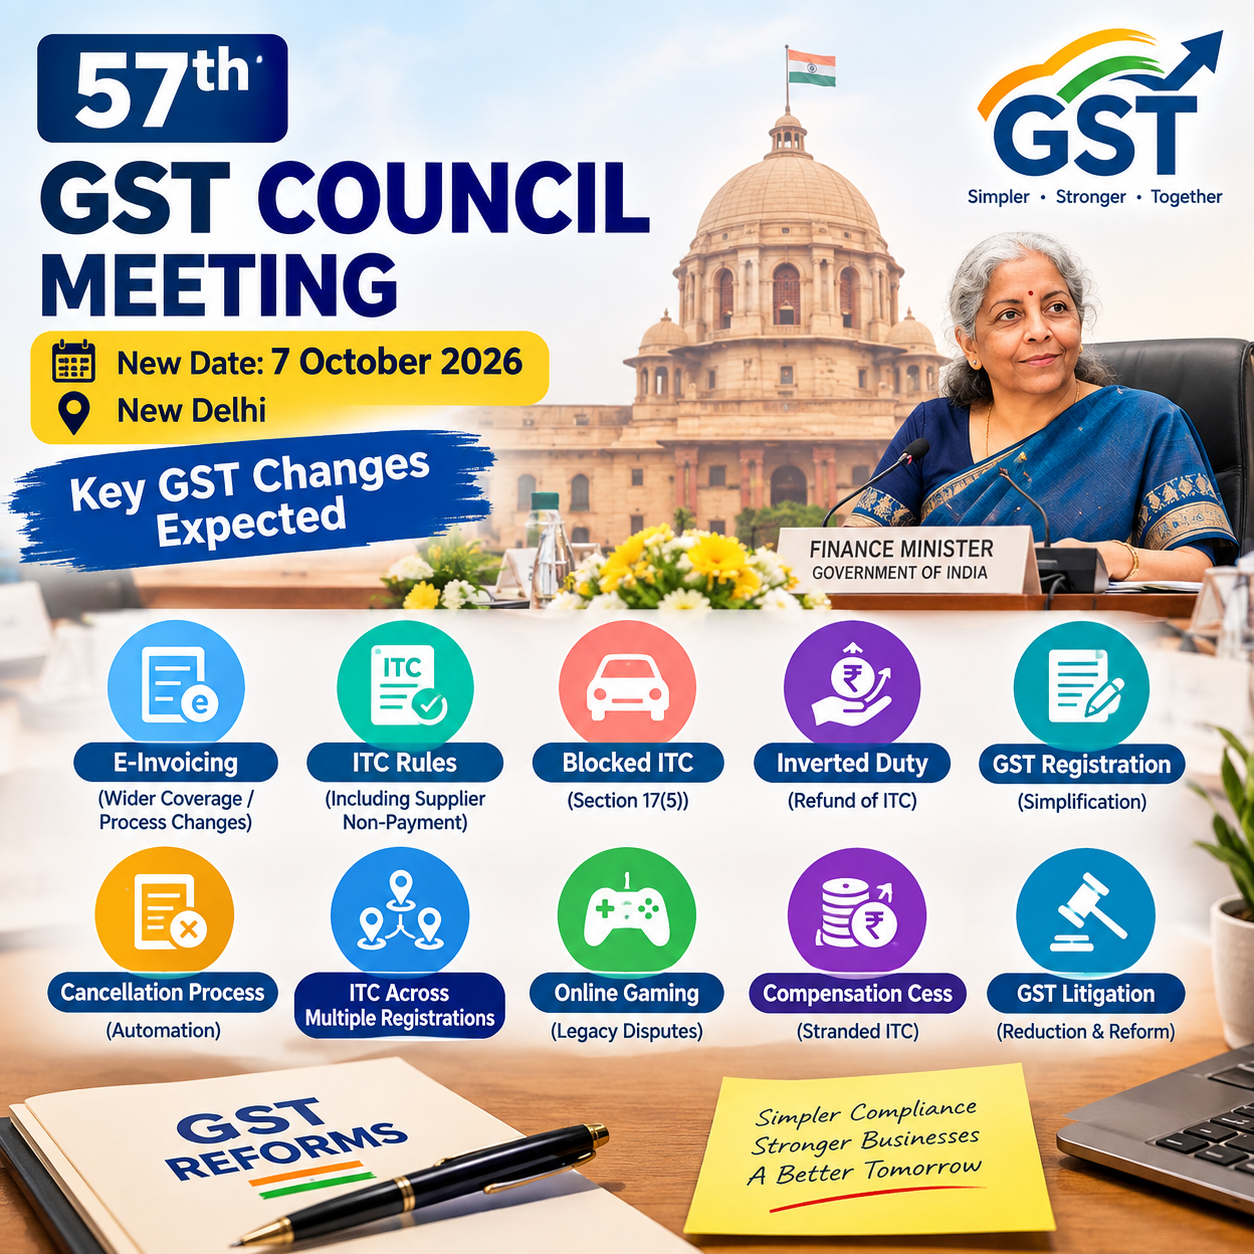
The 57th GST Council Meeting, conducted in New Delhi on 8 October 2026, primarily focused on simplifying GST administration, improving processing speed, and expanding the use of technology in tax compliance. Rather than introducing changes to GST rates, the Council concentrated on procedural and administrative reforms relating to registration, return filing, refunds, Input Tax Credit (ITC), litigation, registration cancellation, e-commerce, exports, and transportation of goods. According to the meeting’s outcome note, no GST rate revisions were announced. The Council also decided that rate-related issues would be considered annually at a separate meeting dedicated exclusively to GST rates.

The reforms follow a year of implementation of the two-rate structure. During this period, taxable supplies and GST collections increased, while the effective tax rate on domestic supplies declined. The Council reported that monthly taxable supplies rose from ₹40.19 lakh crore to ₹50.58 lakh crore, while supplies reported to consumers increased from ₹5.98 lakh crore to ₹7.58 lakh crore. Gross tax liability also recorded growth, whereas the effective tax rate on domestic supplies decreased from 14.55% to 13.13%. The overall observation was that tax rates declined while the tax base expanded.

1. GST Registration Process to Become Simpler and More Automated

A key area of reform is the GST registration system. Currently, applications identified as low-risk, along with applications where output tax on supplies to registered persons does not exceed ₹2.5 lakh per month, can receive system-based registration within three working days without direct intervention by a tax officer. The Council stated that approximately 61% of GST registrations are already processed through this automated mechanism, while the remaining applications are examined by officers.

Under the proposed improvements, the registration portal will become more intuitive and applicant-friendly. It will display only the fields relevant to the applicant and identify the documents required for each specific purpose.

The Council has also approved automatic processing of selected registration amendment applications. Between November 2025 and September 2026, approximately 16.73 lakh amendment applications were submitted, of which 65.45% concerned changes such as trade names, directors’ or partners’ details, and addresses of additional places of business. These specified categories will now be eligible for automatic acceptance.

These changes are intended to reduce manual verification, simplify applications, and speed up routine registration-related procedures.

2. GST Return Filing to Improve Buyer-Seller Data Matching

The Council has proposed further integration between supplier-reported transactions and the Input Tax Credit claimed by buyers. It observed that approximately 95,000 system-generated notices are issued annually because of differences between GST returns. However, the recovery against these notices represents only around 0.08% of the amount involved, suggesting that many discrepancies arise from reporting or data-entry errors.

Under the proposed mechanism, adjustments made by a supplier to previously reported sales will be communicated through the sales statement, enabling the corresponding buyer to account for the change in the original transaction. Taxpayers will also be allowed to correct certain details relating to earlier periods, including an incorrectly entered buyer GST registration number.

The Invoice Management System (IMS) will play an important role in reconciling these transactions. The buyer’s accepted position will flow into the relevant return, helping align supplier reporting with the buyer’s ITC records.

The proposed framework represents a move towards invoice-level reconciliation, reducing avoidable mismatches and improving coordination between buyers and suppliers.

3. GST Refunds to Be Processed More Quickly Through Automation

Improving the refund mechanism is another significant objective of the Council’s recommendations. The time permitted for issuing an acknowledgement of a refund application is proposed to be reduced from 15 days to 10 days. If neither an acknowledgement nor a deficiency memo is issued within this period, the application will be treated as acknowledged.

The Council has also proposed a risk-based refund system under which 90% of the claimed refund amount may be sanctioned through automated processing, subject to the prescribed risk assessment. The refund order is proposed to be issued within three working days of acknowledgement, compared with the existing seven-day period referred to in the outcome note.

Additionally, refunds relating to excess balances in the Electronic Cash Ledger are proposed to be processed automatically without requiring officer intervention.

The proposed system will also reduce repetitive data entry. Relevant shipping details will be obtained from Customs records, while payment information will be sourced from banking systems. This integration is expected to simplify refund applications and reduce administrative delays.

4. Important Proposed Changes in Input Tax Credit

The 57th GST Council Meeting has recommended several changes concerning Input Tax Credit. The proposals include allowing ITC on health and life insurance policies taken for employees, as well as on telecommunication towers and pipelines installed outside factory premises.

Credit is also proposed to be allowed on free samples and on stock written off due to the expiry of its shelf life where the applicable law requires the goods to be destroyed.

Another important proposal concerns services that are purchased and resupplied within the same business line. The Council has indicated that such transactions should not result in the same service being taxed twice because the credit chain is interrupted.

Examples discussed include hotel accommodation costing up to ₹7,500 per night booked through an agent, restaurant and catering services, and passenger transportation. In certain cases, these services were taxed at 5% without ITC, which restricted the flow of credit between businesses.

The proposed changes aim to restore the credit chain in eligible transactions and reduce tax-related distortions in service industries.

5. Inverted Duty Structure Refunds to Include Input Services and Plant & Machinery

The Council has proposed expanding the refund mechanism applicable to an inverted duty structure. Under the earlier framework described in the outcome note, refunds were restricted to tax attributable to input goods.

The proposed amendment will allow refunds relating to tax paid on input services under the inverted duty structure for ITC availed on or after 1 November 2026.

The restriction relating to tax paid on plant and machinery is also proposed to be removed. In such cases, the eligible refund would be calculated at one-sixtieth of the relevant credit for each month, reflecting the working life of the asset. This provision is proposed to apply to ITC availed on or after 1 April 2027.

These measures could help businesses manage accumulated credits and improve working capital availability, particularly in industries such as pharmaceuticals and fast-moving consumer goods (FMCG).

6. GST Litigation Procedures to Follow a Standardised Framework

The Council has proposed a more uniform approach to GST litigation and adjudication. The standard framework is expected to cover the issuance and service of notices, pre-notice communications, the grounds for alleging fraud, hearing procedures, and the preparation of adjudication orders.

Another important proposal is the introduction of a monetary threshold for issuing notices. Under the recommendation, no notice would be issued where the tax amount involved is below ₹10,000.

The objective is to reduce unnecessary disputes and avoid spending disproportionate administrative resources on matters involving relatively small amounts.

Standardised procedures could also improve consistency in the handling of GST disputes across different jurisdictions.

7. Proposed Relief in GST Arrest, Prosecution, and General Penalties

The Council’s outcome note contains important recommendations concerning GST enforcement and penalties. It states that the power of arrest under GST is proposed to be removed.

The prosecution threshold is also proposed to increase from ₹1 crore to ₹5 crore. In addition, the minimum punishment is proposed to be removed, allowing the court to determine whether a fine, imprisonment, or both would be appropriate in an individual case.

The general penalty applicable when no specific penalty is prescribed is proposed to be reduced from ₹25,000 to ₹10,000.

The Council has emphasised a more proportionate approach to compliance failures. Delayed return filing, reporting mistakes, or payment defaults would continue to attract the applicable recovery provisions, interest, and proportionate penalties, rather than additional punitive consequences beyond the relevant legal framework.

The broader objective is to use technology and invoice-level information to identify mismatches and potentially fraudulent ITC claims. The Council’s approach places greater emphasis on detecting irregularities through data analysis rather than relying primarily on deterrent enforcement measures.

8. E-Way Bill Checks and Physical Inspection of Goods in Transit

The Council has proposed changes to the procedure for physically inspecting goods transported under the GST framework.

Under the proposed system, a vehicle may be stopped for inspection only when specific intelligence is available. Prior authorisation from an officer holding a rank not below Joint Commissioner would also be required.

The proposal further restricts inspection powers to the originating State and the destination State. States through which the goods merely transit would not be permitted to stop the vehicle for inspection under the proposed framework.

For instance, if a consignment travels through five States before reaching its destination, physical verification would generally be limited to the State from which the goods originate and the State where they are delivered, rather than permitting routine checks in every intervening State.

E-Way Bills and other prescribed documents would continue to be required, and their details would remain subject to system-based verification. The principal change is that physical inspection would be linked to specific information or intelligence rather than conducted routinely without such a basis.

9. Simplified GST Registration Cancellation and a Proposed Scheme for Small Businesses

The Council has recommended an automated and phased approach to GST registration cancellation and business closure, beginning with smaller taxpayers.

Under the proposed framework, filing the final return would become part of the registration closure application instead of being treated as a separate subsequent step.

Where a GST registration has been suspended or cancelled because of a pending return or missing bank account details, the system is proposed to restore the registration once the taxpayer fulfils the outstanding requirement.

The Council has also granted in-principle approval for an optional compliance scheme for small taxpayers with turnover of up to ₹5 crore who make supplies exclusively to consumers. Under the proposed arrangement, eligible taxpayers would file returns annually while paying tax quarterly.

However, the detailed framework and the necessary legal amendments are expected to be presented at the next Council meeting. Therefore, this proposal should be understood as an in-principle decision rather than an operational filing facility currently available to taxpayers.

10. Key Reforms for Service Exports and E-Commerce Businesses

The meeting also addressed GST-related issues affecting exporters of services and sellers operating through e-commerce platforms.

Changes concerning export of services

An Indian business providing services to a foreign customer through its own overseas branch is proposed to become eligible for export benefits, subject to the applicable conditions and the removal of the restriction identified in the outcome note.

This proposal may be relevant to analytics companies, design businesses, engineering consultants, and Indian offices of international organisations.

The Council has also proposed treating services performed in India on goods belonging to a foreign customer as exports of services, even when the goods do not physically leave India. Examples include testing, repairs, certification, research, and processing activities.

The objective is to improve the tax treatment of these transactions and make India more competitive as a destination for contract processing and specialised services.

Changes concerning e-commerce sellers

Small sellers using e-commerce platforms may receive greater flexibility in managing GST registrations across States.

Under the proposal, a seller could declare an electronic commerce operator’s warehouse located in another State as the seller’s Principal Place of Business in that State, subject to the operator’s consent. This consent is proposed to be obtained automatically through the system.

The seller would still need to maintain a physical presence in at least one State, and the registration in the additional State would be restricted to supplies made through the relevant platforms.

The Council has also proposed a consistent tax treatment for similar services offered through different platform business models. Differences in contractual arrangements have led to varying interpretations of the same provisions. Under the proposed approach, the tax treatment would be determined by the actual service supplied, ensuring that comparable services receive comparable tax treatment regardless of how a platform structures the transaction.

No GST Rate Revision in the 57th GST Council Meeting

A key takeaway from the meeting is that no GST rate changes were announced at the 57th GST Council Meeting.

Instead, the discussions focused on resolving operational difficulties, removing inconsistencies, and addressing ambiguities that remained after the previous year’s rate-related changes.

The Council has decided to consider GST rate matters once a year at a dedicated meeting. This approach is intended to separate rate-related decisions from discussions concerning GST administration and compliance procedures.

Consequently, businesses should distinguish between the procedural reforms proposed at this meeting and changes to the tax rates applicable to goods and services. The emphasis was on improving how the GST system functions in practice, including registration, return filing, refunds, ITC claims, business closure, transportation, exports, and dispute resolution.

How Will the 57th GST Council Meeting Affect Taxpayers?

The recommendations indicate a move towards a more automated, technology-enabled, and risk-based GST compliance framework.

The principal implications for businesses include:

  • Registration: Greater automation and faster processing of eligible applications.
  • Return filing: Improved coordination between supplier declarations and buyer ITC claims.
  • Refunds: Shorter acknowledgement timelines and increased system-based processing.
  • Input Tax Credit: Proposed changes affecting selected insurance, infrastructure, sample, stock, and service transactions.
  • Litigation: More standardised procedures and a proposed monetary threshold for notices.
  • Enforcement: Proposed changes to arrest, prosecution, and general penalty provisions.
  • Transportation: Greater reliance on specific intelligence before conducting physical inspections.
  • Business closure: A more integrated registration cancellation process.
  • Small taxpayers: A proposed optional annual return scheme with quarterly tax payments for eligible businesses.
  • Exports and e-commerce: Proposed clarifications intended to simplify selected cross-border service and platform-based transactions.

For businesses, the key message is that GST compliance is gradually moving away from repetitive manual procedures towards data matching, risk-based assessments, and automated decision-making.

However, taxpayers should carefully distinguish between recommendations announced by the Council and provisions that have become legally effective. Some proposals require detailed rules, system modifications, notifications, or legislative amendments before they can be implemented.

In conclusion, the 57th GST Council Meeting represents a significant step towards GST process reform rather than another round of rate revisions. Its broader objective is to make compliance more convenient for businesses while strengthening the tax administration’s ability to identify discrepancies through technology and invoice-level information.

The proposed measures aim to address the remaining inconsistencies and ambiguities in GST administration and advance the principles underlying GST 2.0, with a greater emphasis on simplification, transparency, automation, and proportionate enforcement.
RBI EDF Rules Change from October 2026: Important Update for Freelancers & Content Creators

New RBI EDF Rules Effective from 1 October 2026 for Freelancers, YouTubers & Influencers

A major regulatory update has become applicable from 1 October 2026 for individuals and businesses in India earning income from overseas service transactions.

The Reserve Bank of India (RBI) has introduced the Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026, replacing the previous FEMA framework governing exports. The new Regulations came into effect on 1 October 2026.

One of the key changes under the new framework is the introduction of a common Export Declaration Form (EDF) mechanism covering exports of goods, services and software.

This change is especially relevant to:

  • Freelancers
  • Consultants
  • Content creators
  • YouTubers
  • Social-media influencers
  • Digital marketing professionals
  • Graphic and web designers
  • Agencies
  • IT and software service providers
  • Other professionals supplying services to clients or recipients located overseas

For service exporters operating from the Domestic Tariff Area (DTA), the Authorised Dealer (AD) bank is the designated authority for services other than software. For software exports, the framework also provides for AD banks/STPI in the DTA, while separate provisions apply to SEZs.


1. What is the Major Change from 1 October 2026?

The earlier FEMA framework generally allowed exports of services to be carried out without an export declaration where none of the prescribed declaration forms was applicable.

The position has changed under the 2026 Regulations.

As per Regulation 3(2), an exporter of services is required to furnish an Export Declaration Form (EDF) declaring the amount representing the full export value of the services.

Accordingly, individuals and businesses receiving payments from overseas for genuine service exports should review whether their transactions are covered by the new FEMA reporting requirements.

Important Clarification

EDF is not a GST return or GST form.

It is an export declaration under FEMA/RBI regulations and operates separately from GST returns, GST invoices, LUT requirements and income-tax compliance.


2. Which Service Providers May Come Under EDF Compliance?

The new requirement may be relevant to several categories of professionals and businesses providing services to overseas recipients.

Freelancers

A freelancer based in India who provides services such as programming, graphic design, consulting, writing, advertising, marketing or similar professional services to a foreign client may be carrying out an export of services.

YouTubers and Content Creators

Digital creators may also need to evaluate the new rules where they receive payments connected with overseas entities or platforms.

Possible arrangements may involve:

  • YouTube or Google
  • Meta
  • Upwork
  • Fiverr
  • International customers or clients
  • Other overseas platforms

However, receiving money from a foreign source alone does not automatically mean that the receipt qualifies as an export of services.

The actual agreement, nature of the service, identity and location of the recipient and applicable place-of-supply rules must be considered.


3. What Qualifies as an Export of Service under GST?

The FEMA requirement should not be confused with the GST definition of export of services.

Under Section 2(6) of the IGST Act, a service is treated as an export of service when the prescribed conditions are fulfilled.

These include:

  1. The service provider is located in India.
  2. The recipient is located outside India.
  3. The place of supply is outside India.
  4. Payment is received in convertible foreign exchange, subject to the applicable legal provisions.
  5. The supplier and recipient are not merely establishments of the same person.

These conditions are also reflected in CBIC’s official GST guidance.

Therefore, simply receiving a payment in dollars, pounds or another foreign currency does not automatically establish that the transaction is an export of service for GST purposes.

The transaction must be tested against all applicable conditions.


4. Who Receives the EDF?

For service exporters located in the Domestic Tariff Area (DTA), the designated authority for services other than software is the Authorised Dealer (AD) bank.

An AD bank is a bank authorised under FEMA to undertake specified foreign-exchange transactions.

Consequently, freelancers, consultants, creators and other service exporters receiving overseas payments should coordinate with the AD bank through which their export proceeds are processed.

The actual submission process may differ between banks. Depending on the bank, EDF filing may be handled through an online banking portal, email-based process or another prescribed mechanism.

Therefore, exporters should confirm the exact procedure with their respective AD bank rather than assuming that every bank follows an identical filing method.


5. What is the EDF Filing Deadline?

The filing timeline is an important aspect of the new compliance framework.

The 2026 Regulations state that the EDF is required to be furnished within 30 days from the end of the month in which the invoice for services was raised.

Example

Suppose a freelancer raises service invoices during October 2026.

The applicable monthly deadline would generally be:

30 November 2026

This means the calculation is not simply 30 days from the date of each individual invoice.

Understanding this distinction can help service exporters organise their monthly FEMA compliance properly.


6. Can Multiple Service Invoices Be Reported Through One EDF?

Yes.

The new framework provides an option to submit a single EDF covering services exported during a month to one or more recipients.

This can make the reporting process more convenient for professionals who issue several export invoices during the month.

Example

Suppose a content creator has the following invoices during October 2026:

Overseas Recipient Invoice No. Amount
Google/Overseas Entity INV-101 USD 1,000
Meta/Overseas Entity INV-102 USD 700
Foreign Client INV-103 USD 500

Subject to the transaction-specific requirements and the AD bank’s process, these service exports may be reported through one monthly EDF.

The EDF includes relevant invoice-level details for the services being declared.


7. Alternative Filing Option for Non-Software Services

The Regulations also provide an important alternative for services other than software.

In such cases, the exporter may furnish the EDF on or before the date on which the payment is received.

Therefore, service exporters should consider the applicable filing route based on their transaction structure and coordinate with their AD bank to ensure that the declaration is submitted correctly and within the prescribed timeline.


Standard Filing Route

Invoice issued during a month → EDF to be filed within 30 days after the end of that month

Alternative Route for Non-Software Services

EDF may be submitted on or before the date the payment is received

This alternative provides additional flexibility to exporters of services other than software.


8. Can the EDF Deadline Be Extended by the Bank?

Yes.

The Authorised Dealer (AD) bank has the authority to extend the time limit for submitting an EDF when the exporter requests an extension and explains the reasons for the delay.

The bank must be satisfied that the reasons provided by the exporter are reasonable before granting the extension.

Therefore, where a genuine delay occurs, the exporter should approach the AD bank and request appropriate relief instead of leaving the EDF compliance pending.


9. What Details Need to Be Reported in the EDF?

The EDF requires detailed information about the export transaction. It is not limited to reporting the amount received from the overseas customer.

The form generally captures information such as:

  • Nature/type of export
  • AD code
  • Importer Exporter Code (IEC)
  • GSTIN
  • PAN
  • Name and address of the exporter
  • Details of the AD bank
  • Method of realisation
  • Recipient or consignee details
  • Third-party payment information, wherever applicable
  • Description of the goods or services
  • Total export value

For service exports, additional information may include:

  • Name and address of the recipient
  • Country of the recipient
  • Invoice number
  • Invoice date
  • Currency
  • Invoice value
  • Net realisable value
  • Contract number and date, wherever applicable
  • Description of services
  • SAC code
  • Relevant remarks

Because the EDF requires invoice and transaction-level information, exporters should maintain accurate invoices, contracts and payment records.


10. What Records Should YouTubers and Content Creators Keep?

Creators receiving income from overseas sources should maintain sufficient documentation to establish the nature and flow of the transaction.

1. Contract or Agreement

Keep the agreement, platform terms or other documentation identifying the relevant contracting party or overseas recipient.

2. Payment Reports

Download and retain statements, payment reports or remittance confirmations provided by the platform or client.

3. Export Invoice

Raise and preserve the relevant invoice for the services supplied.

4. Bank Records

Maintain bank statements and foreign-remittance documents showing receipt of the export proceeds.

5. EDF Copy

Keep a copy or acknowledgement of the EDF submitted to the AD bank.

6. GST Documentation

Where GST registration applies, maintain export invoices, LUT documents and relevant GST return records.

A well-maintained documentation trail should ideally look like:

Agreement → Invoice → EDF → Foreign Remittance → Bank Statement → GST Records


11. The Payment Country Does Not Always Identify the Service Recipient

One practical issue that service exporters should understand is that the country from which a payment is received may not necessarily be the country or entity of the actual contractual recipient.

For instance, an international platform may have one entity as the contracting party while the payment is processed through another group company, payment centre or jurisdiction.

Therefore, exporters should not identify the recipient merely by looking at the location from which the bank payment originated.

Instead, review:

  • Contract/agreement
  • Platform payment statement
  • Invoice
  • Actual recipient or contracting entity
  • Payment arrangement

The key principle is:

The source of the remittance should not automatically be treated as the identity of the service recipient.

The entire transaction structure should be examined before reporting the details in GST and FEMA records.


Export Proceeds Realisation Period Has Also Been Revised

Another important change effective from 1 October 2026 concerns the period within which export proceeds must generally be realised and repatriated.

Under the amended Regulation 5, export proceeds relating to services, including software, are generally required to be realised and repatriated within:

9 months from the date of invoice

For exports invoiced or settled in Indian Rupees, the applicable period is generally:

12 months

This remains subject to the conditions and requirements prescribed under the applicable regulatory framework.

The September 2026 amendment reduced the earlier 15-month period to 9 months, with the revised provision becoming effective from 1 October 2026.

Realisation Period at a Glance

Category of Export General Realisation Period
Services and software 9 months from invoice date
Exports invoiced/settled in INR 12 months
Goods Generally 9 months from shipment
Goods supplied to an overseas warehouse 9 months from sale from the warehouse
Project exports Based on applicable contractual payment terms

Where circumstances justify additional time, an exporter may approach the AD bank for an extension, subject to the applicable conditions and approval process.


GST Compliance Still Applies Separately

The introduction of the RBI EDF mechanism does not eliminate or replace GST requirements.

A service provider exporting services must separately determine whether the transaction satisfies the GST conditions for export and whether registration, LUT and refund provisions apply.

Under Section 16 of the IGST Act, exports of services are treated as zero-rated supplies.

Subject to the applicable conditions, a registered exporter may generally choose to:

  • Export services under LUT/bond without payment of IGST and claim an eligible refund of accumulated ITC; or
  • Export services after paying IGST and claim the applicable refund.

GST Registration for Exporters

GST registration should be examined separately from FEMA/EDF compliance.

CBIC guidance indicates that a person whose outward supplies consist entirely of exports may need GST registration to claim refunds because exports are treated as zero-rated supplies.

For service providers, the general GST registration threshold is ₹20 lakh, subject to applicable exceptions and the lower threshold prescribed for specified special-category States.

Therefore, exporters should assess their individual circumstances instead of assuming that receiving foreign payments automatically removes the need for GST registration.


LUT for Exporting Services Without IGST

A registered exporter who intends to supply services without payment of IGST will generally need to make the export under a valid Letter of Undertaking (LUT), subject to the applicable GST rules and conditions.

This allows eligible exports to be made without charging IGST, with the possibility of claiming a refund of eligible accumulated input tax credit.

Therefore, exporters should keep their compliance chain properly coordinated:

GST Registration → LUT → Export Invoice → GST Return → EDF → Bank Realisation


Export Invoices Must Contain the Required Details

Export invoices issued by registered persons should comply with the applicable GST invoice requirements.

Depending on the method of export, the invoice should contain the appropriate endorsement, such as:

“SUPPLY MEANT FOR EXPORT UNDER BOND OR LETTER OF UNDERTAKING WITHOUT PAYMENT OF IGST”

or the relevant endorsement applicable when IGST is paid.

The invoice should also contain the prescribed information relating to the supplier, recipient, invoice number and date, description of services, country and other applicable particulars.

Proper invoice preparation is important because the same information may need to be reflected consistently across GST, FEMA and banking records.


Reconcile FEMA and GST Records

Maintaining consistency between different compliance records will become increasingly important.

For example, assume a service exporter issues export invoices worth:

₹10 lakh during October 2026

The following records should be capable of being matched:

  • Export invoices
  • GST returns
  • EDF
  • Bank remittance records
  • Accounting books

Since the EDF captures invoice-level information and SAC details for service exports, maintaining a consolidated export-reconciliation statement can simplify the compliance process.


Example: Income Earned by a YouTube Creator

Consider a creator based in India who receives payments from an overseas entity for content-related or other qualifying services.

Step 1 – Determine the Recipient

Review the agreement, platform documentation and payment statement to establish the actual overseas contracting/recipient entity.

Step 2 – Issue the Invoice

Prepare the appropriate invoice containing the required service and recipient information.

Step 3 – Review GST Requirements

Check whether the transaction meets the conditions for export of services and determine the applicable GST registration and LUT requirements.

Step 4 – Prepare the EDF

Report the relevant transaction through the EDF applicable to the relevant month.

Step 5 – File Through the AD Bank

Submit the EDF using the process specified by the relevant Authorised Dealer bank.

Step 6 – Receive the Export Proceeds

Ensure that the payment is received through the appropriate banking channel and properly recorded.

Step 7 – Reconcile the Records

Match the transaction across:

Invoice ↔ EDF ↔ Bank Credit ↔ GST Records


Example: Creator Using Multiple Overseas Platforms

Suppose an Indian creator earns service-related income during October 2026 from:

  • YouTube
  • Meta
  • Upwork
  • A direct overseas customer

Where the individual transactions qualify as service exports, the new FEMA framework allows one EDF to cover services exported during the month to one or more recipients, subject to the applicable requirements.

The EDF will still require the relevant invoice- and recipient-level details.

Therefore, exporters should not automatically assume that a separate EDF must be prepared for every individual invoice.


What Should Service Exporters Do Now?

Service exporters should consider taking the following practical steps:

✔ Review Overseas Receipts

Identify all payments received from foreign clients, platforms and entities.

✔ Establish the Actual Recipient

Check the underlying agreement and supporting documents instead of relying solely on the country from which the payment was received.

✔ Verify Export-of-Service Conditions

Review the GST definition of export of services and applicable place-of-supply rules.

✔ Review GST Registration

Check turnover, registration requirements and refund eligibility.

✔ Maintain a Valid LUT

Where applicable, ensure LUT requirements are completed before exporting services without payment of IGST.

✔ Issue Accurate Invoices

Ensure that invoice information is consistent with GST and FEMA requirements.

✔ Coordinate With the AD Bank

Contact the Authorised Dealer bank and understand its EDF filing procedure and documentation requirements.

✔ Prepare Monthly EDF Data

Maintain invoice-wise information every month so that EDF filing can be completed within the prescribed timeline.

✔ Reconcile All Records

Regularly match invoices, EDF details, GST returns, accounting records and bank receipts.


Final Takeaway

The introduction of the EDF requirement for service exports from 1 October 2026 is an important FEMA compliance development for professionals and businesses receiving overseas service income.

Freelancers, consultants, YouTubers, influencers, designers, digital marketers, agencies and other service providers should review whether their transactions fall within the new reporting framework.

However, RBI/FEMA compliance and GST compliance remain separate obligations. A foreign payment should therefore be reviewed from both the FEMA and GST perspectives.

The practical compliance flow can be summarised as:

Overseas Income → Identify the Actual Recipient → Issue Proper Invoice → Review GST/LUT → File EDF → Receive Export Proceeds → Reconcile Bank, GST & FEMA Records

Key EDF Deadlines to Remember

Normal route:
Invoice raised during the month → EDF within 30 days from the end of that month

Alternative route for services other than software:
EDF on or before receipt of payment

The important point is that the normal deadline is calculated with reference to the end of the month in which the service invoice is raised, rather than simply counting 30 days from the individual invoice date.

With the new framework, maintaining accurate contracts, invoices, EDF records, GST documents and banking records will be essential for smooth FEMA and tax compliance.

New GST Multi-State Registration Facility: Key Details

GSTN launches a new facility for GST registration across multiple States/UTs

Facility introduced from: 1 October 2026

GST registration has become more convenient for businesses that operate or plan to operate in multiple States and Union Territories.

GSTN has introduced a new “Multistate Registration” functionality on the GST Common Portal. This facility allows taxpayers having the same PAN to start GST registration applications for multiple States/UTs through a single process, eliminating the need to repeatedly enter common registration information for each State.

At present, the facility is available only to Normal Taxpayers.

The new functionality aims to simplify the registration process by reducing duplicate data entry and making it easier for businesses with operations in multiple States and Union Territories to complete their GST registrations.

What Is the New Multistate GST Registration Facility?

The GST Common Portal has introduced a new “Multistate Registration” facility for taxpayers who need GST registration in more than one State or Union Territory.

Under this facility, applicants can select all the required States/UTs together instead of initiating completely separate registration processes from the beginning for each State.

The applicant first enters the common details through a Master Temporary Reference Number (Master TRN).

After the common registration information is submitted, the GST portal creates separate State-specific TRNs for each selected State/UT.

This helps eliminate the need to repeatedly enter the same basic information for every State registration application.


Who Is Eligible to Use This Facility?

The Multistate Registration functionality is intended for taxpayers who:

  • Need GST registration in multiple States or Union Territories;
  • Have the same PAN for all the registrations; and
  • Are registered or applying as a Normal Taxpayer.

According to the GSTN advisory, the functionality is currently available specifically for Normal Taxpayers.

Therefore, it should not be understood as a registration facility currently available to every category of taxpayer.


Where Can Applicants Find the New Multistate Registration Option?

A dedicated “Multistate Registration” option has been added to the GST Common Portal homepage.

Using this option, an applicant can choose the States and/or Union Territories where GST registration is required.

Once the required locations are selected, the portal generates a Master Temporary Reference Number (Master TRN).

This Master TRN is then used to provide the common registration details applicable to the selected registrations.


What Does Master TRN Mean?

The Master TRN (Temporary Reference Number) is generated after the applicant selects the States/UTs for which GST registration is required.

It serves as the initial reference for entering and submitting the Common Registration Information (CRI) for all the selected locations.

As a result, the applicant does not need to enter the same basic information separately at the initial stage of every State registration application.

This common-data approach is one of the key advantages of the new Multistate Registration facility.


What Is Common Registration Information (CRI)?

After receiving the Master TRN, the applicant can enter the Common Registration Information (CRI).

The GSTN advisory includes various common details, such as:

1. Business Information

Details concerning the business and its basic constitution are provided at this stage.

2. Promoter or Partner Details

Information relating to promoters or partners can be included in the common registration details.

3. Authorised Signatory Details

Details of the authorised signatory are also captured as part of the common information.

4. Authorised Representative

Where applicable, information relating to the authorised representative can also be provided.

5. Goods and Services

Details of the goods and services supplied or dealt with by the business are included in the common registration information.

The major benefit is that these common details are entered once instead of being repeatedly entered for every State.


Master TRN Must Be Submitted Within 15 Days

One important requirement under the GSTN advisory is that the Master TRN must be submitted within 15 days.

Simply generating the Master TRN does not mean that the GST registration process has been completed.

The applicant must use the Master TRN to provide and submit the Common Registration Information within the specified 15-day period.

Practical Tip

Businesses should keep the necessary information and supporting documents ready before starting the Multistate Registration process.

Generating a Master TRN without completing the common information within the prescribed period could result in unnecessary delays.


What Happens After the Common Information Is Submitted?

The major benefit of the new facility becomes visible after the Common Registration Information (CRI) is successfully submitted.

Once the CRI is submitted through the Master TRN, the GST portal generates separate TRNs for each State/UT selected by the applicant.

For example, assume a business requires GST registration in:

Delhi + Haryana + Maharashtra + Karnataka

The applicant can select all four locations through the Multistate Registration option.

The process will broadly work as follows:

Master TRN is generated

↓

Common Registration Information is entered and submitted

↓

Individual State-specific TRNs are generated

↓

Separate State registration applications are completed

Therefore, the applicant does not need to repeat the entire registration process independently from the beginning for every State.


Which Details Are Auto-Populated in State Applications?

Once the State-specific TRNs are generated, the common information submitted through the CRI is automatically populated in the respective State registration applications.

Importantly, the GSTN advisory clarifies that this information remains editable.

Applicants should therefore carefully review the pre-filled information and make corrections or modifications wherever required before submitting the individual State applications.


What Details Need to Be Entered Separately for Each State?

The Multistate Registration facility does not eliminate the need to provide State-specific information.

After the common details are carried forward, the applicant must complete the information applicable to each individual State/UT.

This includes:

Principal Place of Business (PPoB)

Details of the Principal Place of Business applicable to the particular State registration must be provided.

Additional Place of Business (APoB)

Where applicable, the applicant must enter details of the Additional Place of Business for that State.

State-Specific Details

Any other information specifically required for the relevant State/UT registration must also be furnished.

Aadhaar Authentication

Where applicable, the required Aadhaar authentication process must be completed separately for the respective registration application.


Does Multistate Registration Mean One GSTIN for Multiple States?

No.

The new facility does not create a single GST registration number that covers multiple States.

Instead, it simplifies the GST registration application process.

The applicant enters common information once through the Master TRN, after which that information is carried forward into the respective State applications.

Each State/UT will continue to have its own GST registration and applicable State-specific requirements.

In short, the new Multistate Registration facility makes applying for GST registrations across multiple States more convenient by reducing repetitive data entry while retaining separate State-wise registration requirements.

Master TRN vs State-Specific TRN

The new GST Multistate Registration process becomes easier to understand when the roles of the Master TRN and State-Specific TRN are separated.

Particulars Master TRN State-Specific TRN
Role Starts the common registration procedure Used to complete registration for a particular State/UT
Generated when After the applicant selects multiple States/UTs After the Common Registration Information (CRI) is submitted
Common details Common information is provided through it Common information is pre-filled
PPoB Not provided at the common stage Must be provided for the relevant State
APoB Not provided at the common stage Required wherever applicable
State-specific details Not required at this stage Must be furnished
Aadhaar authentication Forms part of the complete registration procedure Completed for the relevant State application, wherever applicable

In short, the Master TRN serves as the common entry point, while the State-Specific TRNs allow the applicant to proceed with registration separately for each selected State or Union Territory.


Key Benefit: Less Repetition in Data Entry

The biggest advantage of the Multistate Registration facility is that it helps businesses avoid entering identical information multiple times.

Previously, a business requiring GST registrations in several States generally had to complete separate applications and provide common business information repeatedly.

For businesses operating in many States, this could involve entering the same details again and again, including:

  • Business information;
  • Promoter or partner details;
  • Authorised signatory information;
  • Authorised representative details; and
  • Goods and services information.

Under the new system, the common details are submitted through the Common Registration Information (CRI) at the initial stage.

That information is then carried forward to the respective State applications, making the registration procedure more convenient and efficient.


Does the Facility Provide a Single GSTIN for Multiple States?

No.

The introduction of Multistate Registration does not mean that a business will receive one GSTIN covering all its States.

The facility is designed to allow taxpayers to start applications for multiple State/UT registrations through a common process.

Once the Master TRN and CRI stages are completed, separate State-specific TRNs are generated. The applicant must then complete the registration requirements for each individual State or Union Territory.

Therefore, the facility simplifies the registration application workflow, but the State-wise GST registration structure continues to remain in place.


Multistate Registration: Step-by-Step Example

Consider a company named ABC Private Limited that has the same PAN and requires GST registration in:

Haryana, Delhi, Maharashtra and Karnataka.

The process would broadly work as follows.

Step 1 – Select the States

ABC Private Limited opens the Multistate Registration option on the GST Common Portal and selects Haryana, Delhi, Maharashtra and Karnataka.

Step 2 – Obtain the Master TRN

After the States are selected, the portal generates a Master TRN.

Step 3 – Provide Common Details

The applicant uses the Master TRN to submit the Common Registration Information.

The common information may include:

  • Business details;
  • Promoter/director/partner information, as applicable;
  • Authorised signatory details;
  • Authorised representative details, wherever applicable; and
  • Goods and services details.

Step 4 – Submit the Master TRN

The Master TRN has to be submitted within the prescribed 15-day period.

Step 5 – Generate State-Specific TRNs

After submission of the CRI, the portal creates individual TRNs for the selected States:

  • Haryana
  • Delhi
  • Maharashtra
  • Karnataka

Step 6 – Complete Each State Application

The common information is carried forward and auto-populated in the respective State applications.

The applicant then completes the remaining State-level requirements, such as:

  • Principal Place of Business;
  • Additional Place of Business, where applicable;
  • State-specific information; and
  • Aadhaar authentication, wherever required.

Thus, the common registration information does not have to be entered from scratch for every State.


Who Can Benefit From the New Facility?

The Multistate Registration functionality can be particularly helpful for businesses that have operations spread across different parts of India.

Examples include businesses with:

  • Multiple branches;
  • Warehouses in different States;
  • Manufacturing plants in different locations;
  • Offices across various States;
  • Distribution or supply networks; and
  • Several State-wise business establishments.

Such businesses may require multiple GST registrations.

The ability to provide common registration information once can reduce the administrative effort involved in preparing multiple applications.


Which Information Still Has to Be Provided Separately?

The new facility does not remove State-specific requirements.

Even after the common information has been submitted, the applicant must complete the information relevant to each individual State or Union Territory.

The State-level information includes:

Principal Place of Business

The applicant must provide the PPoB details applicable to the particular State registration.

Additional Place of Business

Where relevant, APoB details must also be furnished for that State.

State-Specific Information

Any information specifically required for the relevant State/UT must be completed separately.

Aadhaar Authentication

Where applicable, the required Aadhaar authentication must be completed as part of the respective State registration application.

For example, if a company operates warehouses in both Haryana and Maharashtra, the applicable location details for Haryana and Maharashtra will still need to be entered separately.


How Can Tax Professionals Use This Facility?

The new functionality can also be useful for CAs, GST consultants and tax professionals managing multiple registrations for their clients.

Instead of preparing every application independently from the beginning, the work can be divided into common and State-specific information.

Stage 1 – Common Data Preparation

The professional can first collect and verify:

  • Business details;
  • Promoter/partner details;
  • Authorised signatory information;
  • Authorised representative information; and
  • Goods and services details.

Stage 2 – State-Wise Data Preparation

Separate State-level information can then be arranged for:

  • PPoB;
  • APoB;
  • State-specific requirements; and
  • Applicable Aadhaar authentication.

This two-stage approach can make the registration exercise more structured and reduce duplicate data entry.


Important Things to Keep in Mind

Taxpayers should consider the following points before starting the Multistate Registration process.

1. Currently Applicable to Normal Taxpayers

As stated in the GSTN advisory, the functionality is presently available for Normal Taxpayers.

2. Same PAN Is Required

The facility is designed for obtaining multiple State/UT registrations under the same PAN.

3. Master TRN Is Not the Final Registration

Generating the Master TRN does not mean that GST registration has been completed.

The applicant must submit the CRI and subsequently finish the individual State applications.

4. 15-Day Requirement

The Master TRN must be submitted within 15 days as prescribed under the functionality.

5. State-Level Details Continue

PPoB, APoB, State-specific information and applicable Aadhaar authentication still need to be completed for the respective State applications.

6. Common Data Is Auto-Populated

After the CRI is submitted, the common registration information is automatically carried into the individual State applications.

7. Pre-Filled Information Can Be Modified

The auto-populated information is editable. Applicants should therefore check the details carefully and make corrections wherever necessary before submitting the State application.


How Does Multistate Registration Make GST Compliance Easier?

The main purpose of the new functionality is to minimise duplicate information entry.

For businesses seeking GST registrations across multiple States, entering identical details separately can take additional time and may create inconsistencies between applications.

With the new process, common information can be submitted once and subsequently used in the selected State/UT applications.

This can make the registration procedure more organised, especially for businesses that are expanding their operations across multiple States.


Conclusion

The new Multistate Registration facility introduced on the GST Common Portal provides a more streamlined approach for taxpayers who need GST registrations in multiple States or Union Territories.

The process begins with the selection of the required States/UTs, following which a Master TRN is generated. Through this Master TRN, the applicant submits the Common Registration Information, covering common details such as business information, promoters/partners, authorised signatory, authorised representative and goods/services.

After the CRI is submitted, the portal generates individual State-Specific TRNs. The common information is then auto-populated into the respective State applications.

However, applicants must still complete State-specific requirements, including Principal Place of Business, Additional Place of Business, State-specific information and applicable Aadhaar authentication.

Therefore, Multistate Registration does not replace separate GST registrations for individual States. Its main purpose is to make the application process faster and easier by reducing repetitive entry of common information.

For businesses with a presence across several States, as well as professionals managing multiple GST registrations, this functionality can help create a more efficient registration workflow.

In Simple Terms

Select States/UTs → Generate Master TRN → Submit Common Information → Generate State TRNs → Complete Individual State Applications

The facility is currently available for Normal Taxpayers, and taxpayers should refer to the latest GST Common Portal instructions while using the functionality.

Source: GSTN Advisory on the “Multistate Registration” Facility for GST Registration, dated 1 October 2026.

Complete Compliance Calendar for October 2026

GST | Income Tax | TDS/TCS | PF | ESI | MCA | LLP

October 2026 is an important month from a compliance perspective for businesses, professionals and tax practitioners. Along with the routine monthly and quarterly obligations, the month includes the revised tax-audit deadline of 21 October 2026, various GST return due dates, quarterly TDS/TCS requirements, PF and ESI payments, as well as key MCA and LLP-related filings.

This compliance calendar highlights the major statutory requirements that may apply to businesses and professionals during October 2026. Additional entity-specific, state-level and industry-specific compliances should be reviewed separately based on the nature and circumstances of the taxpayer.


📅 1 October 2026

Income Tax – Key Changes Effective from October

A number of amendments and procedural changes under the Income Tax Act, Income Tax Rules and related notifications come into effect from 1 October 2026.

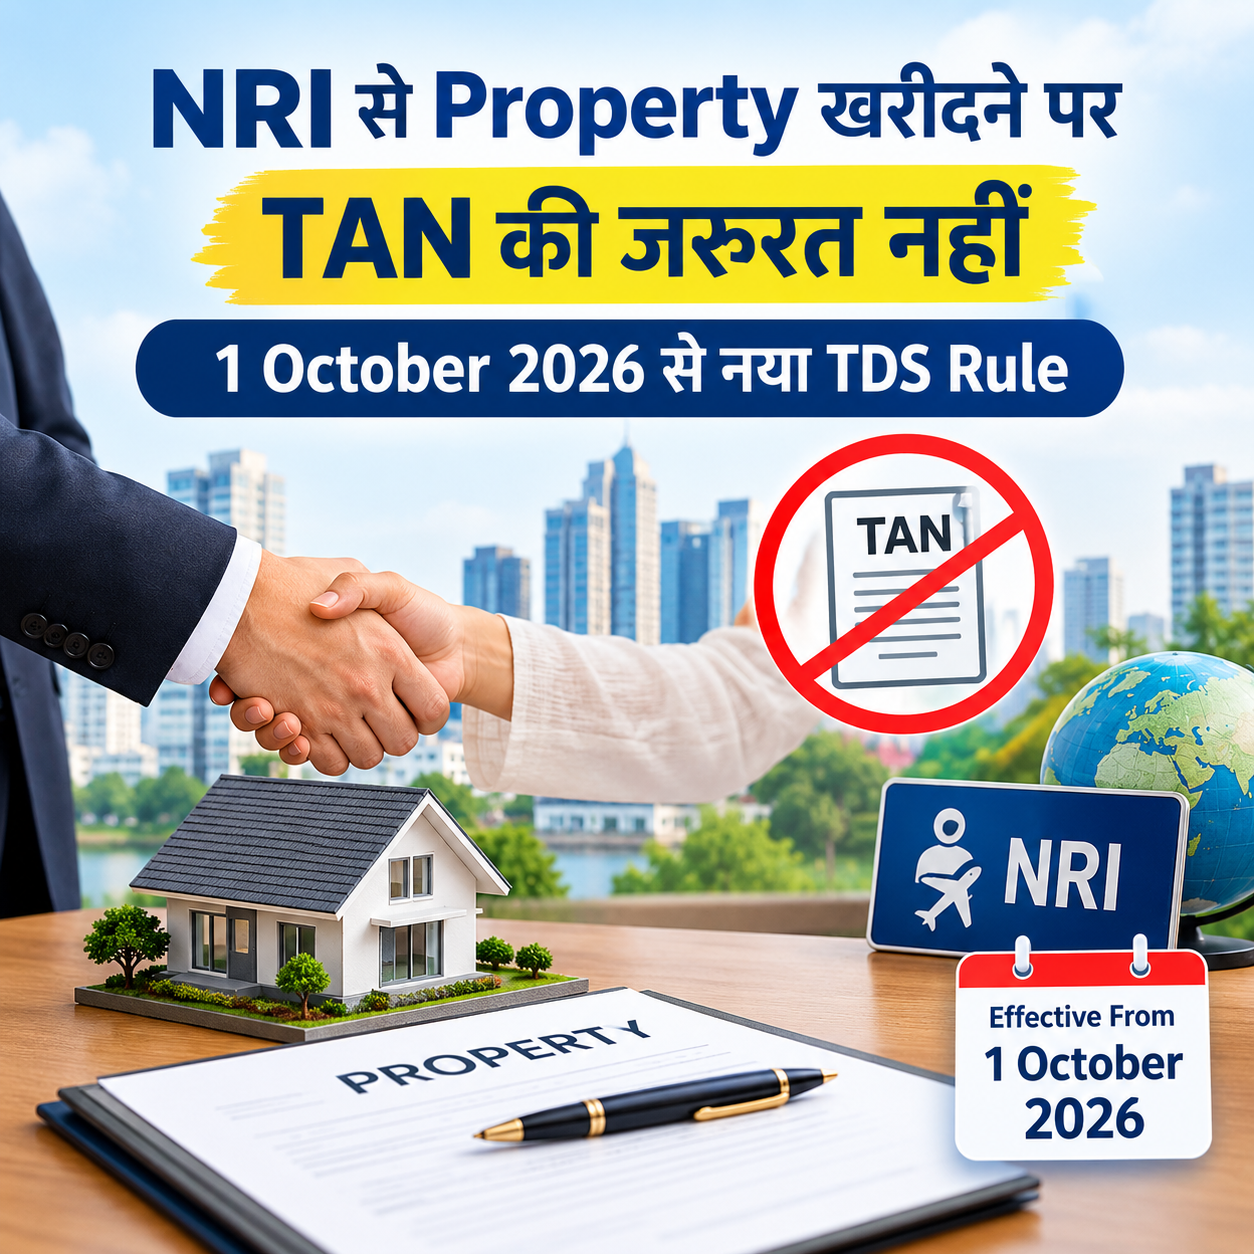
One notable change relates to the purchase of immovable property from a non-resident (NRI). In specified cases, a resident Individual or HUF purchasing property from an NRI will not be required to obtain a TAN solely for complying with the applicable TDS procedure. Instead, the new PAN-based reporting process, including Form 141, becomes applicable.

However, the removal of the TAN requirement does not mean that the underlying TDS obligation has been eliminated. Buyers involved in such transactions should carefully review the revised procedure and applicable reporting requirements before making the payment.

📅 5 October 2026

GSTR-5A – OIDAR Services

GSTR-5A applies to overseas service providers supplying Online Information and Database Access or Retrieval (OIDAR) services to non-taxable persons located in India.

General due date: 20th of the following month.

Taxpayers falling under this category should verify the relevant return period and the applicable filing date on the GST portal before filing.


📅 7 October 2026

TDS/TCS Deposit for September 2026

Tax deducted or collected during September 2026 is generally required to be deposited with the Government by 7 October 2026.

The standard Income Tax compliance timeline requires TDS to be deposited by the 7th day of the succeeding month, subject to applicable exceptions.

Who should review this compliance?

  • Companies
  • Firms and LLPs
  • Other TDS deductors
  • Employers deducting tax from salaries
  • Individuals/HUFs covered by TDS provisions
  • Persons responsible for collecting TCS, wherever applicable

Action point: Reconcile the September TDS/TCS liability with the relevant challans and accounting records before making the payment.


📅 10 October 2026

GSTR-7 – GST TDS Return

GSTR-7 for September 2026

Due date: 10 October 2026

This return is applicable to persons and entities required to deduct TDS under the GST law.


GSTR-8 – GST TCS Return

GSTR-8 for September 2026

Due date: 10 October 2026

This return applies to e-commerce operators who are required to collect TCS under GST.


📅 11 October 2026

GSTR-1 – Monthly Return

GSTR-1 for September 2026

Due date: 11 October 2026

Applicable to regular taxpayers who furnish GSTR-1 on a monthly basis.

The standard monthly GSTR-1 filing date is the 11th of the succeeding month.

Before submitting GSTR-1, verify:

  • Sales recorded in the books
  • E-invoices
  • Debit and credit notes
  • B2B invoices
  • B2C supplies
  • Export transactions
  • Advances received
  • Amendments
  • HSN-wise details

📅 13 October 2026

GSTR-1 – QRMP Taxpayers

GSTR-1 for July–September 2026

Due date: 13 October 2026

This applies to eligible taxpayers registered under the Quarterly Return Monthly Payment (QRMP) scheme.

For quarterly filers, GSTR-1 is generally due on the 13th of the month following the relevant quarter.


GSTR-5 – Non-Resident Taxable Persons

GSTR-5 for September 2026

Due date: 13 October 2026

GSTR-5 is applicable to registered non-resident taxable persons. For monthly periods covered under the current framework, the prescribed filing date is generally the 13th of the succeeding month.


GSTR-6 – Input Service Distributors

GSTR-6 for September 2026

Due date: 13 October 2026

This return is applicable to registered Input Service Distributors (ISDs).


📅 15 October 2026

EPF Payment & ECR – September 2026

Due date: 15 October 2026

Employers covered under EPF should complete the monthly provident fund contribution, payment and related ECR requirements within the prescribed deadline.

Employer review checklist:

  • New employee additions and exits
  • UAN details
  • Employee wages
  • Employer and employee contributions
  • ECR information
  • Payment status

ESI Contribution – September 2026

Due date: 15 October 2026

Employers covered by the ESI scheme should deposit the applicable contribution for September 2026 within the prescribed period.


📅 18 October 2026

CMP-08 – Composition Scheme

CMP-08 for July–September 2026

Due date: 18 October 2026

Applicable to eligible composition taxpayers who are required to submit the quarterly statement and pay the corresponding tax liability.


📅 20 October 2026

GSTR-3B – Monthly Filers

GSTR-3B for September 2026

Due date: 20 October 2026

Applicable to taxpayers filing GSTR-3B on a monthly basis.

Before filing, taxpayers should reconcile:

Books → GSTR-1 → GSTR-3B → GSTR-2B

Special attention should be given to:

  • Output tax liability
  • Input Tax Credit
  • Reverse Charge Mechanism
  • Credit/debit notes
  • Amendments
  • Interest
  • Late fees
  • Earlier-period adjustments

GSTR-5A – OIDAR Services

For OIDAR service providers covered by the relevant provisions, the applicable monthly GSTR-5A compliance should also be reviewed during this period.

Businesses providing such services should verify the relevant tax period and exact filing date available on the GST portal.


📅 21 October 2026

🚨 Tax Audit Report – Important October Deadline

21 October 2026 is one of the key compliance dates for eligible taxpayers during October.

The tax-audit report deadline for AY 2026-27 has been extended from:

30 September 2026 → 21 October 2026

The extension has been communicated by the CBDT through Circular No. 07/2026 dated 28 September 2026.

Who needs to consider this extension?

The revised date applies to the specified category covered under Sl. No. 2 in the Table below Explanation 2 to Section 139(1), subject to the applicable statutory conditions.

Important compliance distinction

The extension of the tax-audit report deadline should not automatically be treated as an extension for every audit-related form.

Taxpayers should separately verify the due date and applicability of:

  • Tax Audit Report: 21 October 2026 for eligible specified cases
  • Form 10B/10BB: Check applicability and its connection with the relevant audit-report requirements
  • Form 10BD: Separate compliance; it should not automatically be considered covered by the tax-audit extension
  • Transfer Pricing cases: Subject to separate applicable timelines

This distinction is particularly relevant for companies, firms, LLPs, societies and charitable or religious trusts.


📅 22 October 2026

GSTR-3B – QRMP Group 1

Eligible QRMP taxpayers belonging to the applicable Group 1 States/UTs should file:

GSTR-3B for July–September 2026

Due date: 22 October 2026

The applicable QRMP due date depends on the State/UT of the taxpayer’s principal place of business.


📅 24 October 2026

GSTR-3B – QRMP Group 2

Eligible QRMP taxpayers falling under the applicable Group 2 States/UTs should file:

GSTR-3B for July–September 2026

Due date: 24 October 2026

For instance, Haryana falls under the Group 2 classification under the standard QRMP arrangement. Therefore, eligible QRMP taxpayers in Haryana should generally consider 24 October 2026 as the applicable quarterly GSTR-3B deadline.


📅 25 October 2026

ITC-04 – Job Work Reporting

ITC-04 is relevant for manufacturers or principals who are required to report specified details relating to goods sent to or received back from job workers.

For the April–September 2026 period, the relevant filing date is 25 October 2026, subject to the taxpayer’s applicable category and reporting frequency.

Information to reconcile before filing:

  • Goods sent to job workers
  • Goods received back
  • Goods supplied from job-worker premises
  • Job-work challans
  • Pending goods
  • Time limits prescribed under Section 143

📅 30 October 2026

AOC-4 – Financial Statements

AOC-4/AOC-4 XBRL may become due during October for companies whose AGM date results in an October filing deadline.

The statutory filing period is linked to the actual AGM date and applicable provisions. Therefore, 30 October should not be treated as a common due date applicable to every company.

Companies should calculate their filing deadline based on their AGM date and the relevant MCA requirements.

The applicable annual filing forms are available on the MCA V3 portal.


LLP Form 8 – Statement of Account & Solvency

LLPs are required to file Form 8 – Statement of Account & Solvency within the prescribed period following the end of the financial year.

For FY 2025-26, the generally applicable due date is:

30 October 2026

LLPs should complete the required statement, certification and filing formalities before the applicable deadline.


TCS Certificate – Form 27D

Where applicable, the TCS certificate relating to the second quarter should be issued within the prescribed period.

Businesses should verify the applicable certificate requirements under the new Income Tax framework, including the transition from the earlier form numbering.


📅 31 October 2026

Quarterly TDS Statements – Q2

The quarterly TDS statements for July–September 2026 are generally required to be filed by:

31 October 2026

Under the new Income Tax framework, several forms have been renumbered. For example:

  • Form 138 – corresponding to the earlier Form 24Q for salary TDS
  • Form 140 – corresponding to the earlier Form 26Q for specified non-salary resident payments
  • Form 27Q – reporting relating to specified payments to non-residents under the applicable framework

The Income Tax Department prescribes 31 October as the Q2 due date for the relevant Form 138 and Form 140 filings.


TCS Quarterly Statement – Q2

For the period July–September 2026, the quarterly TCS statement in Form 143 is generally due on:

31 October 2026

The applicable TCS collectors should complete the statement after reconciling collections, challans and transaction records.


MSME Form-1 – Half-Yearly Filing

Specified companies having payments outstanding to Micro and Small Enterprises beyond the prescribed period should review their MSME Form-1 reporting requirements for the April–September 2026 period.

October is an important month for the half-yearly reporting cycle.

Companies should verify:

  • Vendor balances
  • MSME registration details
  • Pending invoices
  • Invoice due dates
  • Payments already made
  • Amounts remaining outstanding beyond the prescribed period

📌 October 2026 – GSTR-9 & GSTR-9C Preparation

Although GSTR-9 and GSTR-9C for FY 2025-26 are generally not due in October, this month can be used to begin the annual GST reconciliation process.

GSTN’s framework provides for the annual return and reconciliation statement within the prescribed annual-return timeline, generally linked to 31 December of the subsequent financial year, unless the Government extends the deadline.

Therefore, businesses should begin their FY 2025-26 reconciliation in October rather than waiting until the final month.

Key reconciliation areas:

Books of Accounts

↓

GSTR-1

↓

GSTR-3B

↓

GSTR-2B / ITC

↓

E-Invoices

↓

Credit & Debit Notes

↓

RCM

↓

HSN Summary

↓

GSTR-9 / GSTR-9C

Early reconciliation can help identify differences between accounting records and GST returns before the annual filing deadline.


📊 October 2026 Compliance Calendar – Quick Reference

Date Compliance Period Applicable To
5 Oct GSTR-5A September 2026 OIDAR suppliers, where applicable
7 Oct TDS/TCS payment September 2026 Deductors/collectors
10 Oct GSTR-7 September 2026 GST TDS deductors
10 Oct GSTR-8 September 2026 E-commerce operators
11 Oct GSTR-1 September 2026 Monthly filers
13 Oct GSTR-1 July–September 2026 QRMP taxpayers
13 Oct GSTR-5 September 2026 NRTPs
13 Oct GSTR-6 September 2026 ISDs
15 Oct PF/ECR September 2026 EPF-covered establishments
15 Oct ESI September 2026 ESI-covered establishments
18 Oct CMP-08 July–September 2026 Composition taxpayers
20 Oct GSTR-3B September 2026 Monthly filers
21 Oct Tax Audit Report AY 2026-27 Specified eligible audit cases
22 Oct GSTR-3B July–September 2026 QRMP Group 1
24 Oct GSTR-3B July–September 2026 QRMP Group 2
25 Oct ITC-04 April–September 2026 Applicable job-work cases
30 Oct AOC-4 FY 2025-26 Companies, based on AGM date
30 Oct LLP Form 8 FY 2025-26 LLPs
31 Oct TDS statement July–September 2026 TDS deductors
31 Oct TCS statement – Form 143 July–September 2026 TCS collectors
31 Oct MSME Form-1 April–September 2026 Specified companies

⭐ October 2026 – CA & Tax Professional Action Checklist

Income Tax

☐ Deposit September TDS/TCS by 7 October
☐ Complete outstanding tax-audit work
☐ Submit eligible tax-audit reports by 21 October
☐ Work on audited ITRs considering the applicable extended timeline
☐ Prepare Q2 TDS statements
☐ Prepare the Q2 TCS statement
☐ Review NRI property transactions and the new Form 141 procedure

GST

☐ File GSTR-7
☐ File GSTR-8
☐ Complete monthly GSTR-1
☐ File QRMP GSTR-1
☐ File GSTR-5
☐ File GSTR-6
☐ Submit CMP-08
☐ Complete monthly GSTR-3B
☐ Complete QRMP GSTR-3B
☐ Review and file ITC-04, where applicable
☐ Begin FY 2025-26 GSTR-9/GSTR-9C reconciliation

Payroll

☐ Complete PF payment and ECR
☐ Deposit ESI contribution
☐ Reconcile salary TDS
☐ Review employee master data and payroll records

Companies & LLPs

☐ Review AOC-4/AOC-4 XBRL due dates
☐ Check MGT-7/MGT-7A requirements based on AGM date
☐ Review MSME Form-1 applicability
☐ Complete LLP Form 8
☐ Check ADT-1 filing requirements based on AGM
☐ Review other applicable event-based MCA filings

15 Big Rules and Changes Taking Effect in October 2026

October 2026 is an important month for taxpayers, businesses and professionals from the perspective of income tax, GST, banking and financial compliance. Several new provisions are taking effect this month, while a number of important compliance activities also require attention.

One of the key developments is the extension of the tax-audit and income-tax return deadlines. Meanwhile, the GST sector is preparing for the 57th GST Council meeting, and businesses should also begin their preparation for the FY 2025-26 annual GST return.

Beyond taxation, taxpayers should also take note of changes concerning property purchases from NRIs, UPI charges, EPF, NPS, bank withdrawals, fixed deposits and digital banking records.

Here are the major October 2026 updates that taxpayers and businesses should keep in mind.


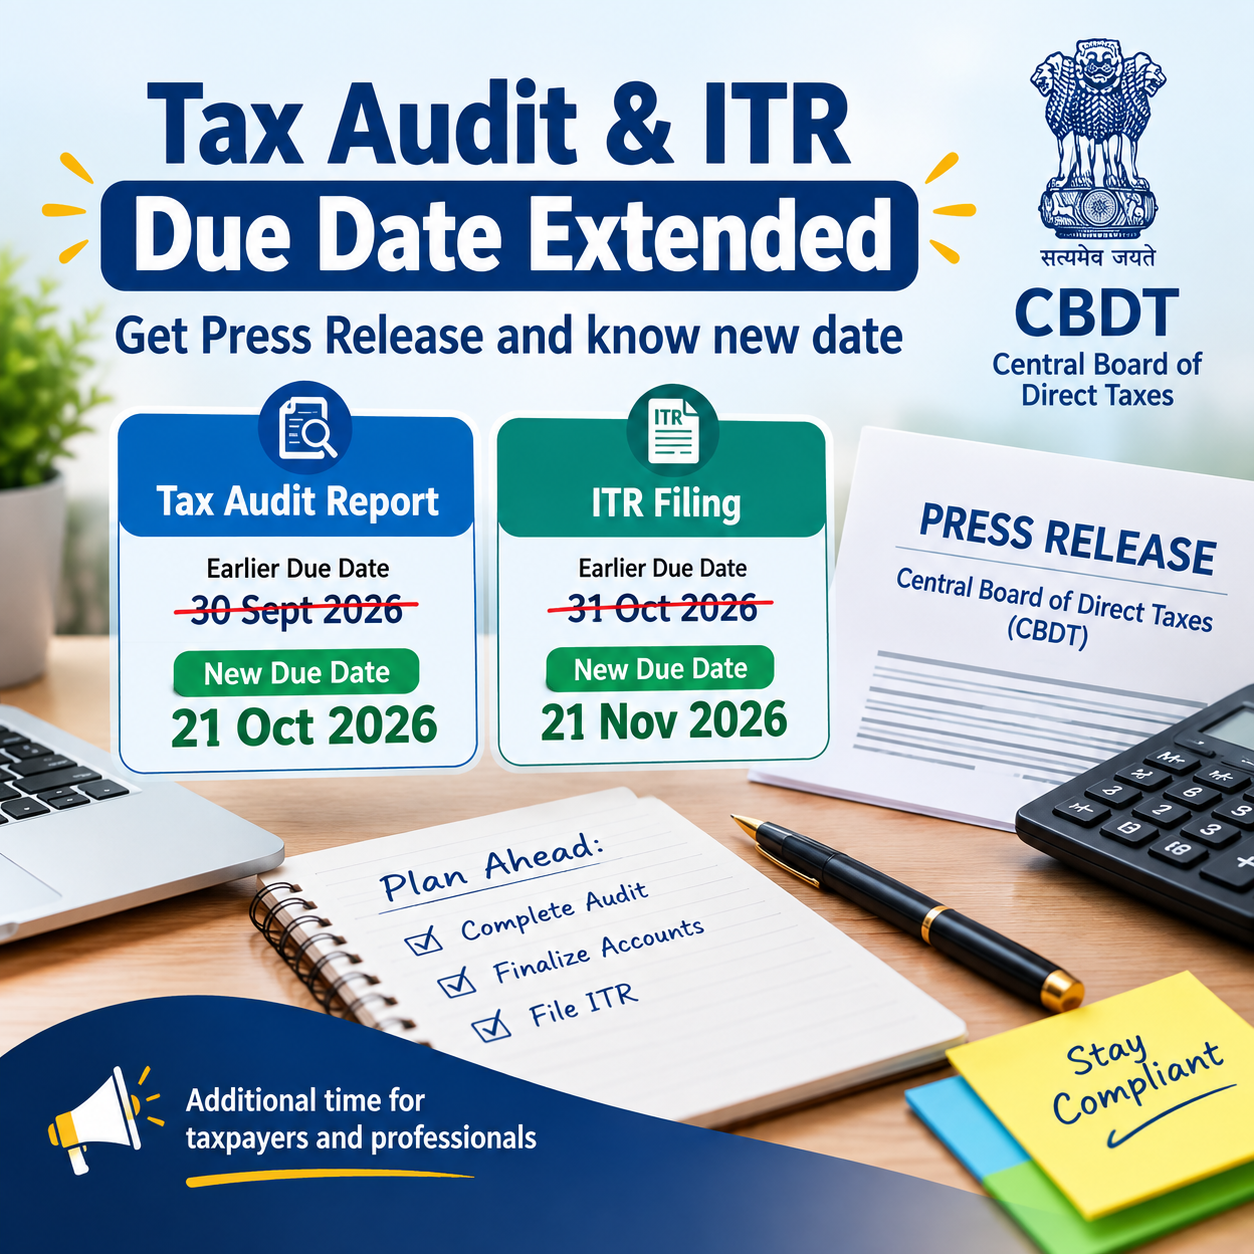
1. Tax Audit Due Date Extended to 21 October 2026

A major update for taxpayers and tax professionals is the extension of the tax-audit report deadline for Assessment Year 2026-27.

Through CBDT Circular No. 07/2026 dated 28 September 2026, the due date for furnishing the tax-audit report has been extended from 30 September 2026 to 21 October 2026 for taxpayers falling within the relevant category specified under Explanation 2 to Section 139(1) of the Income-tax Act, 1961.

The related deadline for filing the Income Tax Return has also been shifted from 31 October 2026 to 21 November 2026.

Who can avail of this extension?

It is important to understand that this extension is not applicable universally to every taxpayer or every type of audit report.

In general, the extended timeline applies to taxpayers belonging to the category where the normal ITR due date was 31 October 2026, including:

  • Companies required to get their accounts audited and which do not fall under transfer-pricing provisions.
  • Non-company taxpayers whose accounts are subject to audit under the Income-tax Act or another applicable law, subject to the prescribed conditions.
  • Firms, LLPs and other entities covered by the relevant tax-audit provisions.
  • Partners of firms whose accounts are required to be audited, wherever the applicable conditions are fulfilled.
  • Other taxpayers falling within the relevant category under Explanation 2 to Section 139(1).

A key distinction is transfer pricing. Taxpayers covered by Section 92E follow a separate compliance schedule and are not covered by this particular extension. Their applicable reporting and return deadlines continue according to the transfer-pricing provisions.

What happens to Form 10B and Form 10BB?

Charitable and religious trusts and institutions should also examine the impact of the extended deadline.

Form 10B is the audit report applicable to specified charitable or religious trusts and institutions. Form 10BB applies to other eligible cases. These forms are required to be furnished within the specified timeline linked to Section 44AB.

Accordingly, where the trust or institution falls within the category covered by the revised specified date, the applicable Form 10B or Form 10BB deadline will also move to 21 October 2026.

This should, however, not be confused with Form 10BD.

Form 10BD follows a separate deadline

Form 10BD relates to the statement of donations received by specified charitable institutions. Its normal due date is 31 May immediately following the financial year in which the donations are received.

Therefore, the October tax-audit extension does not change the Form 10BD due date to 21 October.

In summary:

Compliance October 2026 deadline/status
Tax Audit Report – eligible audit cases 21 October 2026
ITR – eligible audit cases 21 November 2026
Form 10B – eligible cases 21 October 2026, where linked to the specified date
Form 10BB – applicable cases 21 October 2026, where applicable
Form 10BD Not covered by the extension; normal due date is 31 May
Form 3CEB – Transfer Pricing Report Not covered by this extension

2. ITR Due Date for Eligible Audit Cases Moved to 21 November

The extension of the tax-audit deadline has also resulted in additional time for filing the Income Tax Return for eligible taxpayers.

The revised deadline has changed from:

31 October 2026 → 21 November 2026

This provides additional time to taxpayers and professionals to complete the audit process, finalise financial statements and file the corresponding income-tax return.

However, taxpayers should remember that this is not a general extension applicable to everyone. Non-audit taxpayers and taxpayers covered by transfer-pricing provisions continue to follow their respective statutory deadlines.


3. 57th GST Council Meeting Scheduled for 7 October 2026

The 57th GST Council meeting, scheduled for 7 October 2026, is another significant development to watch during October.

The meeting is relevant for businesses, taxpayers and GST professionals because various matters concerning GST administration, compliance procedures and taxpayer facilitation may come up for discussion.

However, there is an important distinction between a proposal or recommendation discussed by the GST Council and an actual amendment in GST law.

A GST Council recommendation does not automatically make a new GST rate, rule or compliance requirement effective. Businesses should wait for the relevant notification, circular, amendment or other legal communication before making changes to their accounting and GST compliance processes.


4. Preparation for GSTR-9 and GSTR-9C for FY 2025-26

October is also an important period for businesses to start preparing for their annual GST return for FY 2025-26.

Based on the previous year’s GSTN process, annual-return forms such as GSTR-9 and GSTR-9C are expected to become available during the October period.

Businesses should therefore begin their reconciliation work well before the December deadline instead of waiting until the last month.

Key areas that should be reconciled include:

  • Books of accounts with GSTR-1
  • GSTR-1 with GSTR-3B
  • ITC recorded in books with ITC claimed in GSTR-3B
  • ITC with GSTR-2B
  • Reverse Charge Mechanism transactions
  • Credit and debit notes
  • Amendments reported in later periods
  • HSN/SAC details
  • Exempt, nil-rated and non-GST supplies
  • Refunds and outstanding demands

For FY 2025-26, the annual-return filing deadline is 31 December 2026, subject to the applicable provisions and any subsequent notification. Current professional guidance also refers to the ₹2 crore threshold for GSTR-9 and ₹5 crore threshold for GSTR-9C.

Practical approach: Businesses should use October to start the GSTR-9/9C reconciliation process rather than postponing the exercise until December.


5. New TDS Compliance for Property Purchase from an NRI

From 1 October 2026, an important compliance change applies to certain property transactions involving a non-resident seller.

When a resident individual or HUF purchases an immovable property from an NRI, the buyer-side TDS compliance process is being modified so that the buyer does not have to obtain a TAN solely for this specified TDS compliance.

Under the revised mechanism, PAN-based reporting and the prescribed form, including Form 141, become important.

It is important to understand that the removal of the TAN requirement does not mean that the TDS obligation has been abolished.

Anyone purchasing property from an NRI should therefore verify the following before completing the transaction:

  1. Whether the seller qualifies as a resident or non-resident.
  2. Whether TDS is applicable under the relevant provision.
  3. The correct TDS rate applicable to the transaction.
  4. PAN details of both parties.
  5. The reporting and prescribed-form requirements applicable from 1 October 2026.

Property transactions involving NRI sellers require particular care because incorrect TDS compliance                        can result in interest, fees and other tax-related consequences.

6. EPF Wage Ceiling Revised

Another important development concerns the EPF wage ceiling.

The wage ceiling has been increased from ₹15,000 to ₹25,000, effective from 17 September 2026. As a result, employers may need to consider the revised limit while handling October payroll and the related ECR compliance process.

Employers should review their payroll systems and verify employee eligibility, contribution calculations and ECR information before completing the applicable monthly filing.


7. Revised Charges for NPS Services

NPS subscribers should also take note of the updated charges applicable to various NPS services from October 2026.

The changes may be particularly relevant when opening a new NPS account or reviewing the charges associated with services provided through Points of Presence and other intermediaries.

Subscribers should remember that charges may vary between PoP-based NPS accounts and direct/e-NPS channels. The applicable cost depends on the account-opening and service route.

Therefore, users should refer to the applicable PFRDA/NPS charge structure for their specific account instead of relying only on the headline charge.


8. Disclosure of Interest Rates on Bulk Fixed Deposits

Another banking-related change concerns bulk fixed deposits.

Under the revised framework, banks are required to publish the applicable interest rates for bulk deposits on their websites.

This requirement is more relevant to large depositors, companies and institutions than to individuals holding smaller fixed deposits.

Businesses, trusts and other organisations with significant deposits should therefore check the bank’s published bulk-deposit rates before making a fresh deposit or renewing an existing large deposit.


9. SBI BSBD Accounts: Revised Cash Withdrawal Charges

SBI’s revised service-charge provisions for Basic Savings Bank Deposit (BSBD) accounts are also relevant during October.

Under the revised arrangement, BSBD customers are entitled to a specified number of free cash withdrawals. Charges may apply once the permitted free limit has been exceeded.

The reported revised fee is ₹15 plus applicable GST per transaction after the free withdrawal limit.

Customers who make frequent cash withdrawals should check the free transaction limit applicable to their account and refer to the latest SBI service-charge schedule.


10. Revised SBI ATM Transaction Limits

SBI customers should also review the ATM transaction limits applicable from October 2026.

For certain salary-account customers using ATMs belonging to other banks, the number of free transactions is being revised.

After the applicable free limit is exhausted, charges may be imposed on both financial and non-financial transactions, depending on the nature of the transaction and the relevant service-charge rules.

Customers who regularly use other-bank ATMs should therefore verify their applicable free limit rather than assuming that the previous limit remains unchanged.


11. UPI Merchant Transactions and MDR Changes

Another significant payment-related development involves UPI merchant transactions.

Under the reported changes, merchant transactions above the specified threshold may attract MDR under the revised framework from 15 October 2026.

MDR is primarily a cost associated with merchant payment acceptance. It should not be treated as a general fee imposed on normal person-to-person UPI transfers.

Businesses accepting UPI payments should therefore examine the charges applicable through their acquiring bank or payment service provider and assess the potential impact on transaction costs.

Before making changes to customer pricing or accounting treatment, businesses should verify the final applicable regulatory and implementation instructions.


12. LPG Subsidy and Aadhaar-Based Authentication

Consumers who receive LPG subsidy benefits should ensure that their Aadhaar authentication or e-KYC requirements have been completed wherever applicable.

Those who have already completed the required authentication generally do not need to repeat the process simply because October has begun.

Consumers who have not yet completed the applicable authentication should check the latest instructions issued by their LPG provider to avoid any disruption to eligible subsidy benefits.


13. Greater Recognition of Digital Banking Records

Changes concerning the legal framework for bankers’ books and banking records are also relevant to the financial sector.

From October 2026, the framework provides recognition to electronic, digital and certain cloud-based banking records, subject to the applicable prescribed conditions.

The development reflects the increasing shift from traditional physical banking records to digitally maintained information.

For businesses, it also highlights the importance of maintaining accurate electronic records, proper audit trails and dependable data backups.


14. Updated Process for Delayed Birth and Death Registration

The procedure for delayed registration of births and deaths is also undergoing changes.

Under the revised framework, the authority required to approve a delayed registration can vary depending on the length of the delay.

Therefore, applicants should not assume that the same authority or approval procedure applies to every delayed registration case.

The relevant authority, documents and approval process should be confirmed according to the specific period by which the registration has been delayed.


15. October TDS/TCS Compliance Requirements

October is also an important compliance month for TDS and TCS deductors and collectors, particularly in relation to quarterly compliance for the second quarter.

Businesses should ensure that they have:

  • Deducted TDS correctly.
  • Properly matched and accounted for challans.
  • Verified PAN details.
  • Filed applicable TDS/TCS statements within the prescribed time.
  • Initiated corrections promptly wherever errors are identified.
  • Reconciled Form 26AS, AIS and other relevant records wherever required.

As tax compliance continues to become increasingly digital, businesses should also maintain the underlying supporting documents and records in an organised manner.


16. MCA and Annual Corporate Filing Requirements

October can also be an important compliance period for companies and LLPs, depending on their financial year, AGM date and applicable statutory filing timelines.

Companies should review whether they need to complete filings or compliances such as:

  • AOC-4
  • MGT-7 / MGT-7A
  • MSME-related reporting
  • Director-related compliances
  • Auditor-related filings
  • Other applicable event-based MCA forms

There is no common October deadline that applies to every company. The actual due date depends on the entity’s AGM date, financial year and individual statutory circumstances.

Companies should therefore maintain an entity-specific MCA compliance calendar instead of relying on a standard October deadline.


Key October 2026 Dates at a Glance

Date Important update
1 October 2026 Various banking, NPS, property-TDS and other compliance changes take effect
7 October 2026 57th GST Council Meeting
October 2026 Expected period for GSTR-9 and GSTR-9C availability/preparation for FY 2025-26
15 October 2026 UPI merchant MDR-related implementation
21 October 2026 Extended tax-audit/reporting deadline for eligible taxpayers
21 November 2026 Extended ITR filing deadline for eligible audit cases
31 December 2026 FY 2025-26 annual GST return deadline, subject to applicable provisions

What Should Businesses and Taxpayers Do in October 2026?

October should be viewed not only as a month in which several new provisions take effect, but also as an important preparation period for upcoming compliance deadlines.

Businesses should first determine whether they actually fall within the category eligible for the 21 October tax-audit deadline. Companies, firms, LLPs, trusts, societies and other entities should examine their applicable statutory provisions and return category rather than assuming that the extension automatically applies to them.

Charitable and religious institutions should separately verify their Form 10B or Form 10BB requirements. These should not be confused with Form 10BD, which follows a separate due-date mechanism.

GST-registered businesses should also begin their FY 2025-26 GSTR-9 and GSTR-9C reconciliation once the relevant forms are available on the GST portal. Starting early can help businesses identify discrepancies between books of accounts, GSTR-1, GSTR-3B and input-tax-credit records and resolve them before the annual-return deadline.

Businesses should additionally review October payroll changes, NPS charges, banking service fees, UPI merchant costs and NRI property TDS requirements wherever these are relevant to their operations.

Taking these steps early can help taxpayers and businesses organise their documentation, identify applicable changes and avoid last-minute compliance issues.

New Tax Audit & ITR Deadline: Due Date Extended, Check Latest Update

The Central Board of Direct Taxes (CBDT) has announced a significant extension of the due dates for filing the Tax Audit Report and Income Tax Return for Assessment Year 2026-27. The extension applies to taxpayers who fall under the specified audit category covered by Section 139(1) of the Income-tax Act, 1961.                                     The CBDT issued its press release on 28 September 2026, confirming an extension of the applicable deadlines. The revised timelines are intended to give the affected taxpayers and tax professionals additional time to complete the audit formalities and file their income tax returns.

The Central Board of Direct Taxes (CBDT) has announced an extension of the due date for filing the Return of Income for Assessment Year 2026-27 for taxpayers covered under S. No. 2 of the Table below Explanation 2 to Section 139(1) of the Income-tax Act, 1961.

For such taxpayers, the income tax return filing deadline has been extended from 31 October 2026 to 21 November 2026. Consequently, the specified date for furnishing the tax audit report for AY 2026-27 has also been extended from the earlier date to 21 October 2026.

The CBDT has issued a press release confirming these revised deadlines.

Tax Audit Deadline Revised

According to the CBDT press release, the “specified date” for submitting the audit report under the Income-tax Act, 1961 has been extended for the applicable category of taxpayers.

The original deadline was:

30 September 2026

The new deadline announced by CBDT is:

21 October 2026

Accordingly, taxpayers covered under the specified category will have additional time to complete and furnish their tax audit reports.

The change is especially relevant to taxpayers whose accounts are required to undergo tax audit and to Chartered Accountants responsible for preparing, finalising, and uploading the related audit reports.

Income Tax Return Deadline Also Revised

CBDT has simultaneously extended the Income Tax Return filing deadline for AY 2026-27 for taxpayers falling under the specified category.

The previous deadline was:

31 October 2026

The revised deadline is:

21 November 2026

Therefore, the extension provides additional time for both completion of the audit-report requirements and subsequent filing of the income tax return for the taxpayers covered by the announcement.

Extension Applies Only to the Specified Category

Taxpayers should note that the CBDT announcement does not constitute a blanket extension for all taxpayers.

The press release specifically covers persons referred to at Serial No. 2 in the table under Explanation 2 to Section 139(1) of the Income-tax Act, 1961.

Therefore, taxpayers should verify whether their particular case falls within this specified category before relying on the revised deadlines.

Revised Tax Audit Report Date

The CBDT press release clearly provides that the “specified date” for furnishing the audit report has been shifted from 30 September 2026 to 21 October 2026.

In practical terms, the audit-report deadline is extended first, followed by the revised ITR filing deadline applicable to the specified category.

Particulars Earlier Deadline Revised Deadline
Tax Audit Report – specified date 30 September 2026 21 October 2026
ITR for AY 2026-27 – specified category 31 October 2026 21 November 2026

What Additional Time Can Be Used For

For taxpayers covered by the CBDT announcement, the extended timeline can help provide additional time to:

  • Complete the tax audit process
  • Finalise books and financial records
  • Complete audit-related disclosures and reporting
  • Furnish and upload the audit report
  • Verify tax calculations and liabilities
  • Prepare and review the Income Tax Return
  • Reconcile applicable tax-related information before filing the return

At the same time, taxpayers should remember that this extension is not a universal extension applicable to every taxpayer.

Separate Formal Order or Notification

The CBDT press release also indicates that a separate formal order/notification will be issued to give effect to the revised deadlines.

Taxpayers and tax professionals should therefore refer to the formal CBDT order or notification as well for the detailed operative provisions of the extension.

Key Points at a Glance

The key dates announced in the CBDT press release dated 28 September 2026 for the specified audit category for AY 2026-27 are:

Tax Audit Report:
30 September 2026 → 21 October 2026

Income Tax Return:
31 October 2026 → 21 November 2026

The revised dates apply specifically to the persons covered by the category identified in the CBDT announcement. Therefore, taxpayers should first confirm their eligibility for the extension rather than assuming that the revised deadlines apply to all taxpayers.

TDS on NRI Property Purchase: No TAN Needed from 1 October 2026

NRI Property Purchase: TAN Not Required from 1 October 2026 | New TDS Compliance Rules

CBDT has issued Notification No. 121/2026 dated 22 September 2026, introducing significant procedural changes for TDS compliance when an immovable property is purchased from a non-resident. The amendment is especially relevant for resident Individuals and HUFs who purchase property from an NRI.

The Finance Act, 2026 had already provided that, from 1 October 2026, a resident Individual or HUF will not need to obtain a TAN for deducting tax on consideration paid for the transfer of immovable property to a non-resident. The latest CBDT notification now gives effect to the related changes in the Income-tax Rules and introduces a new reporting mechanism through Form No. 141 along with Schedule E.

The notification, known as the Income-tax (Fifth Amendment) Rules, 2026, will apply from 1 October 2026.


What Changes from 1 October 2026?

Consider a situation where a resident Individual purchases a house in India from an NRI.

Under the earlier compliance framework, TDS had to be deducted on payments made to a non-resident. Since the transaction was covered by the provisions applicable to payments to non-residents, the buyer was required to obtain a TAN for TDS compliance.

The Finance Act, 2026 has now provided relief from this additional requirement.

The amendment was introduced because obtaining a TAN for an individual property transaction can create an unnecessary compliance burden, particularly where a resident Individual or HUF makes only a one-time purchase from an NRI.

Accordingly, the relevant provision has been amended to remove the TAN requirement for eligible resident Individuals and HUFs with effect from 1 October 2026.

An Important Clarification

Removal of TAN does not mean removal of TDS.

This distinction is crucial.

From 1 October 2026, an eligible resident Individual or HUF can deduct the applicable TDS without obtaining TAN. However, the underlying TDS obligation on the payment made to the non-resident seller will continue to apply.


Why Has the Government Introduced This Change?

The amendment addresses the difference in compliance requirements between property purchases from resident and non-resident sellers.

When the Property Seller Is a Resident

For specified property transactions involving a resident seller, an Individual or HUF can comply with the applicable TDS provisions without obtaining TAN, subject to the prescribed conditions and procedures.

When the Property Seller Is a Non-Resident

Property transactions involving an NRI seller are subject to the TDS provisions applicable to payments made to non-residents. Under the earlier framework, this could require the resident buyer to obtain a TAN, even when purchasing only one property.

The 2026 amendment seeks to reduce this additional compliance requirement.

The Budget memorandum explained that the change provides a relaxation from the requirement to obtain TAN for a resident Individual or HUF in cases involving the purchase of immovable property from a non-resident.


Which TDS Provision Applies to Property Purchased from an NRI?

The Income-tax Act, 2025 reorganised the TDS provisions into a tabular structure.

For payments made to non-residents, Section 393(2), Table Serial No. 17 covers specified payments, including amounts chargeable to tax that are not taxable under the head “Salaries.”

Therefore, where a resident Individual or HUF purchases immovable property from a non-resident and the payment is subject to TDS, the relevant framework is:

Section 393(2) → Table Serial No. 17

Section 393(2) Applies — Not the Regular Resident-Property TDS Provision

For a property transaction involving a non-resident seller, the applicable provision is Section 393(2), Table Serial No. 17, rather than the ordinary TDS provision applicable to property purchases from a resident under Section 393(1).


What Did CBDT Notify on 22 September 2026?

The CBDT Notification No. 121/2026 dated 22 September 2026 introduces important procedural amendments relating to TDS on purchases of immovable property from non-residents.

The notification makes changes to Rules 215, 218 and 219 and revises Forms 132 and 141. These amendments will take effect from 1 October 2026.

Broadly, the changes can be divided into four key areas:

  1. TAN exemption for eligible Individuals and HUFs
  2. Procedure for depositing TDS
  3. Reporting of TDS through Form 141
  4. Issuance of TDS certificate through Form 132

Let us look at each change in detail.


1. TAN Will Not Be Required from 1 October 2026

The most significant relief comes from the amendment to Section 397.

A resident Individual or HUF who is required to deduct TDS on consideration paid for the transfer of immovable property to a non-resident will no longer need to obtain a TAN, subject to the conditions prescribed under the law.

The Finance Act, 2026 specifically brought this category within the exemption provided under Section 397(1)(c).

TDS Position Before and After 1 October 2026

Particular Up to 30 September 2026 From 1 October 2026
Buyer Resident Individual/HUF Resident Individual/HUF
Seller Non-resident Non-resident
TDS Applicable Applicable
Relevant provision Section 393(2), Table 17 Section 393(2), Table 17
TAN Required Not required
Reporting Existing non-resident TDS procedure Form 141 – Schedule E
TDS Certificate Existing procedure Form 132

Therefore, the amendment should not be interpreted as an exemption from TDS.

The correct takeaway is:

From 1 October 2026, a resident Individual or HUF purchasing immovable property from a non-resident can deduct the applicable TDS without obtaining TAN.


2. Form 141 Gets a New Reporting Framework

Another significant change introduced through the 22 September 2026 notification relates to Form No. 141.

The existing form has been modified so that it now also covers transactions falling under Section 393(2), Table Serial No. 17.

The notification has specifically added this provision to the heading of Form 141.

More importantly, a new section titled:

Schedule E — TDS on Consideration for Transfer of Immovable Property under Section 393(2), Table Serial No. 17

has been incorporated into Form 141.

This new schedule provides the reporting framework for these transactions after the TAN requirement has been removed.


What Details Must Be Reported in Schedule E?

The newly introduced Schedule E requires detailed information concerning the property, buyers, non-resident sellers and the corresponding TDS transaction.

1. Information About the Property

The buyer will have to provide details such as:

  • Complete address of the immovable property
  • Nature/type of property

The available property categories include:

  • Land other than agricultural land
  • Building or a part of a building
  • Both land and building

These details form part of the newly prescribed Schedule E.


2. Information of All Buyers

Schedule E also requires details of every buyer involved in the transaction.

The information includes:

  • Serial number
  • Buyer’s PAN
  • Buyer’s name
  • Percentage/proportion of the total consideration payable or credited by each buyer

The total proportion reported for all buyers should add up to 100%.

Example of a Joint Property Purchase

Suppose a husband and wife jointly purchase a property.

The reporting could reflect:

  • Husband — 50%
  • Wife — 50%

The form therefore captures the PAN and respective share of consideration for each buyer.


3. Detailed Information About Non-Resident Sellers

Since the transaction involves a non-resident seller, Schedule E requires additional information about each seller/deductee.

The prescribed details include:

  • PAN, where available
  • Name of the seller
  • Status
  • Contact number
  • Email address
  • Foreign residential address
  • Tax Residency Certificate number
  • Tax Identification Number
  • Proportion of the total sale consideration received or debited to each seller

This makes the reporting requirements more detailed than those generally applicable to a standard resident-property TDS transaction.


PAN Alone Is Not Sufficient for an NRI Seller

One of the important points in the amended Form is contained in Note 6.

The prescribed note clarifies that the contact number, email address and foreign address of the non-resident deductee are mandatory, regardless of whether the non-resident has a PAN.

In cases where the non-resident seller does not have a PAN, the specified details relating to the seller’s Tax Residency Certificate (TRC) and Tax Identification Number (TIN) may also be required in accordance with Rule 217 to determine the applicable rate and avoid higher-rate deduction where the prescribed conditions are satisfied.

Therefore, buyers should not assume that the absence of the seller’s PAN automatically means that TDS can simply be deducted at a higher rate.

The new Schedule E has been specifically structured to collect comprehensive information about the non-resident seller and the applicable tax details.

4. Agreement Date and Registration Date

The newly introduced Schedule E also captures important dates related to the property transaction.

The buyer is required to provide:

  • Date of agreement
  • Date of registration, wherever applicable or available

These details help establish the sequence and timing of the property transaction for reporting and TDS purposes.


5. Sale Consideration and Stamp Duty Value

Schedule E specifically requires reporting of two important amounts:

  • Total Stamp Duty Value of the property
  • Total Sale Consideration relating to the property

These figures are relevant for determining the appropriate tax treatment and TDS liability in transactions involving a non-resident seller.

The transaction cannot simply be treated in the same manner as the standard 1% TDS mechanism applicable to purchases from resident sellers. The applicable provisions for payments to a non-resident have to be examined separately.


6. Instalment-Based Property Payments Are Also Included

The new Schedule E recognises that the purchase consideration may be paid in multiple instalments rather than in a single payment.

The buyer must specify whether the consideration is being paid:

  • In a lump sum, or
  • Through instalments

Where payment is made in instalments, the form further requires the buyer to identify whether the payment represents:

  • First instalment
  • Subsequent instalment
  • Final instalment

For a subsequent or final instalment, the acknowledgement number of the earlier filing is also required.

In the case of the final instalment, the form additionally requires the total consideration paid or credited, including the current instalment.

This provision is particularly relevant for NRI property transactions, where the sale consideration may commonly be settled through several payments.


7. Information Relating to the NRI Seller’s Capital Gains

Schedule E does not merely capture payment-related information. It also seeks specific details concerning the tax treatment of the non-resident seller.

The form requires information such as:

  • PAN of the deductee/seller
  • Name of the seller
  • Whether the seller has opted out of the applicable tax regime under Section 202(1), wherever relevant
  • Nature of capital gains arising to the seller

The capital-gain category includes options such as:

  • Long-term capital gains
  • Short-term capital gains, excluding specified gains

This is important because TDS in a transaction involving an NRI is determined with reference to the amount chargeable to tax and the applicable provisions/rate. It is therefore different from simply applying the standard 1% TDS rule used for specified property purchases from resident sellers.


8. Detailed TDS Calculation Information

The new Schedule E also provides for reporting of the actual TDS computation.

The relevant fields include:

  • Proportionate stamp duty value
  • Amount paid or credited through earlier instalments
  • Amount paid or credited in the current transaction
  • Date of payment or credit
  • Amount on which TDS is applicable
  • Applicable TDS rate
  • Certificate number under Section 395(1), where obtained by the deductee
  • Certificate number under Section 395(2), where obtained by the deductor
  • TDS amount deducted
  • Date of TDS deduction

These requirements indicate that Form 141 is designed as a detailed transaction-level reporting statement, rather than being merely a replacement form after the removal of the TAN requirement.


What Happens If the NRI Has a Lower or Nil TDS Certificate?

The new reporting framework also takes into account situations where the non-resident seller has obtained a lower or nil deduction certificate.

Schedule E provides a specific field for the certificate number issued under Section 395(1) when the deductee has obtained such a certificate.

It also provides a separate field for the certificate issued under Section 395(2) where the certificate has been obtained by the deductor.

Therefore, the removal of the TAN requirement does not mean that the lower or nil deduction certificate provisions have been discontinued.

The buyer must still determine the applicable TDS after considering the provisions relevant to the non-resident seller and the amount chargeable to tax.


Payment and Form 141 Compliance Under the Amended Rules

The CBDT notification has also made corresponding amendments to the procedural rules.

Rule 218(3) has been modified to specifically include consideration for the transfer of immovable property covered under Section 393(2), Table Serial No. 17, where the payment or credit is made by a resident Individual or HUF.

A corresponding amendment has also been made to Rule 219(5), which now specifically refers to the same category of transactions.

Therefore, the notification goes beyond simply changing the format of a form. The relevant Rules have also been updated to establish the payment and reporting procedure for these transactions.


Form 132 Also Covers NRI Property Transactions

CBDT has additionally amended Rule 215(1).

The revised provision now covers TDS deducted under:

Section 393(2), Table Serial No. 17

where a resident Individual or HUF deducts tax from consideration payable for the transfer of immovable property.

As a result, Form No. 132 has also been revised.

The amended form specifically covers transactions involving:

Transfer of immovable property by a non-resident to a resident Individual or Hindu Undivided Family.

Thus, from 1 October 2026, the overall compliance process can be understood as:

TDS deduction → Payment and reporting through Form 141 → TDS certificate through Form 132

The key benefit is that an eligible resident Individual or HUF does not need to obtain TAN merely for carrying out this TDS compliance on the purchase of immovable property from a non-resident.

What TDS Rate Applies to Property Purchased from an NRI?

Buyers need to be especially cautious about the TDS rate in these transactions.

A purchase of property from a non-resident seller should not be treated in the same way as the standard property transaction involving a resident seller under Section 393(1), Table Serial No. 3(i), where the specified 1% TDS mechanism applies subject to the prescribed conditions.

For a transaction involving an NRI seller, the relevant provision is:

Section 393(2) — Table Serial No. 17

This provision deals with specified sums chargeable to tax that are paid to a non-resident.

Therefore, it would be incorrect to apply the general statement:

“Property purchase means 1% TDS.”

The 1% mechanism relates to the specified resident-seller property transaction. In an NRI property purchase, the buyer must determine TDS by considering the amount chargeable to tax, applicable tax rates, relevant treaty provisions where applicable, and any valid lower or nil deduction certificate.


How Is TDS Handled in a Joint Property Purchase?

The new Schedule E of Form 141 becomes particularly important where more than one person purchases the property.

For example:

  • Mr. A — Resident Individual — 50% share
  • Mrs. A — Resident Individual — 50% share

If they jointly purchase property from an NRI, Schedule E requires details of each buyer, including:

  • PAN
  • Name
  • Proportion of the total consideration

The same principle applies when there are multiple non-resident sellers. The form requires information relating to each seller/deductee and their respective share of the consideration.

Another important procedural point is that where there is more than one deductor, each deductor is required to furnish a separate form.

This makes buyer-wise reporting particularly important in joint property transactions.


What If the NRI Seller Does Not Have a PAN?

The amended reporting framework also deals with cases where the non-resident seller does not have a PAN.

The following details must be provided:

  • Contact number
  • Email address
  • Address outside India

These details are required irrespective of whether the seller has a PAN.

Where PAN is not available, the prescribed information relating to the seller’s tax residency and identification in the country of residence must also be furnished, wherever applicable, so that the relevant TDS-rate provisions can be properly considered.

Practical Tip for Buyers

A buyer should collect the NRI seller’s required overseas tax information before the transaction is completed.

Waiting until the TDS filing stage may create avoidable compliance issues, particularly where the seller’s PAN, Tax Residency Certificate or Tax Identification Number is required.


Old TDS Framework vs New Framework

Property Purchased by a Resident Individual/HUF from an NRI

Particular Up to 30 September 2026 From 1 October 2026
Buyer Resident Individual/HUF Resident Individual/HUF
Seller Non-resident Non-resident
Applicable provision Section 393(2), Table 17 Section 393(2), Table 17
TDS Applicable, subject to chargeability Applicable, subject to chargeability
TAN Required Not required
Reporting Existing non-resident TDS procedure Form 141 – Schedule E
TDS Certificate Applicable Form 132
Seller information Required More detailed prescribed reporting
Joint purchasers Applicable Buyer-wise details required
Instalment payments Applicable Specifically reported in Schedule E
Lower/Nil deduction certificate Available subject to conditions Available subject to conditions

Why Is CBDT Notification No. 121/2026 Significant?

The change announced in Budget 2026 was the starting point for removing the TAN requirement.

The Finance Act, 2026 amended the relevant provision so that, from 1 October 2026, a resident Individual or HUF purchasing immovable property from a non-resident would no longer need to obtain TAN solely for this TDS obligation.

However, removing TAN also required the government to establish an alternative compliance mechanism.

The transaction still needs to be properly:

  • Reported
  • Linked with the buyer and seller
  • Matched with the property details
  • Accompanied by the applicable TDS payment
  • Reflected in the TDS certificate

The CBDT Notification No. 121/2026 dated 22 September 2026 addresses these procedural requirements by making amendments to the relevant Income-tax Rules and modifying Forms 132 and 141.

The introduction of Schedule E in Form 141 is particularly important because it provides a dedicated reporting structure for transactions covered by Section 393(2), Table Serial No. 17.


Effective From 1 October 2026

The Income-tax (Fifth Amendment) Rules, 2026 come into force from 1 October 2026.

Therefore, the relevant date of the transaction/payment becomes important.

Transactions falling before 1 October 2026

The existing compliance framework, including the applicable TAN requirement, continues to apply.

Transactions falling on or after 1 October 2026

Where a resident Individual or HUF purchases immovable property from a non-resident, TAN will no longer be required under the amended provisions. However, the applicable TDS, payment and reporting requirements will continue.


Practical Checklist for Buying Property from an NRI

Before proceeding with the transaction, a resident Individual or HUF should keep the following information ready.

Buyer Details

  • PAN
  • Name
  • Residential status
  • Share in the property/consideration

NRI Seller Details

  • PAN, if available
  • Name
  • Overseas address
  • Contact number
  • Email address
  • Tax Residency Certificate details
  • Tax Identification Number
  • Share of sale consideration

Property Information

  • Property address
  • Type/nature of property
  • Agreement date
  • Registration date, where available
  • Stamp Duty Value
  • Total sale consideration

TDS Information

  • Previous instalment payments
  • Current payment
  • Date of payment/credit
  • Amount subject to TDS
  • Applicable TDS rate
  • TDS amount
  • Lower/Nil deduction certificate details, where applicable

The new Schedule E provides for reporting of these categories of information.


Key Takeaway

The amendment effective from 1 October 2026 provides procedural relief to resident Individuals and HUFs purchasing immovable property from non-resident sellers.

However, the most important distinction is:

TAN has been removed — TDS has not been removed.

From 1 October 2026, an eligible resident Individual or HUF will not need to obtain TAN merely because TDS is required on the purchase of immovable property from a non-resident under Section 393(2), Table Serial No. 17.

At the same time, the buyer must continue to comply with the applicable TDS provisions and the newly prescribed reporting mechanism through Form 141 with Schedule E, along with the TDS certificate requirements under Form 132.

In Simple Terms

Property purchased from a Resident
→ Section 393(1), Table Serial No. 3(i)

Property purchased from a Non-Resident
→ Section 393(2), Table Serial No. 17

From 1 October 2026
→ Resident Individual/HUF buying from NRI
→ No TAN requirement
→ TDS obligation continues
→ Form 141 + Schedule E reporting
→ Form 132 TDS certificate

Major Rules Changing from 1 October 2026: GST, Tax, UPI, PF & TDS Updates You Need to Know

 Several new rules are scheduled to take effect, important compliance deadlines will fall during the month, and some major policy developments may also emerge.

In particular, people should keep an eye on important updates related to Income Tax, GST, UPI, PF, TDS, Aadhaar, and LPG.

It is important to note that not all of these changes will come into effect on 1 October itself. Some rules will become effective from 1 October, some are important developments taking place during October, while others were introduced in September but may have a more visible practical impact from October onwards.

Let us understand these updates one by one.


1. UPI MDR to Apply from 15 October 2026 — What You Need to Know

One of the major UPI-related developments in October concerns the introduction of a Merchant Discount Rate (MDR) framework.

From 15 October 2026, a new MDR framework will apply to specified Person-to-Merchant (P2M) UPI transactions. For eligible merchant transactions above ₹2,000, the standard MDR will be 0.4%. For transactions of ₹75,000 or more, the maximum MDR will be capped at ₹300 per transaction.

However, this does not mean that customers will have to pay a 0.4% charge on every UPI payment.

Person-to-Person (P2P) UPI transactions will continue to remain free. MDR will also not apply to merchant payments up to ₹2,000 and eligible transactions involving small merchants covered under the zero-MDR framework.

Another important point is that MDR is not a Government tax. It is a merchant-side charge distributed among participants in the payment ecosystem. Banks have also been advised to ensure that merchants do not pass this cost on to customers.

Therefore, if you make a UPI payment of ₹5,000 or ₹10,000, it should not automatically be interpreted as a “0.4% UPI tax” on the customer.

2. Tax Audit: Penalty Risk After 30 September 2026

For businesses and professionals, 30 September 2026 is an important compliance deadline.

For tax audit cases relating to FY 2025-26 (AY 2026-27), the due date for furnishing the tax audit report is 30 September 2026. The Income Tax Department has clarified that tax audits for FY 2025-26 will continue to be governed by the Income-tax Act, 1961, even if the audit report is filed after 1 April 2026.

If the tax audit report is not furnished by 30 September and the Government does not grant any extension, there may be an exposure to penalty under Section 271B.

The penalty is generally:

0.5% of turnover or gross receipts

or

₹1,50,000

whichever is lower.

ITR Due Date for Tax Audit Cases

For regular tax audit cases, the due date for filing the Income Tax Return (ITR) is 31 October 2026. Different deadlines may apply to taxpayers covered by transfer-pricing provisions.

According to the Income Tax Department’s FAQ, for FY 2025-26, the tax audit report is due by 30 September 2026, while the applicable ITR for audit cases is generally due by 31 October 2026.

3. Important GST Council Meeting Scheduled for 7 October 2026

Another major event for GST taxpayers in October is the upcoming 57th GST Council Meeting.

The 57th GST Council Meeting is now scheduled to be held on 7 October 2026 in New Delhi. The meeting was originally planned for 12 September but was later rescheduled. The meeting of GST officials is expected to take place on 5–6 October.

The meeting may discuss several GST process and compliance reforms, including matters relating to ITC rules, GST registration, e-invoicing, refunds, and GST-related litigation.

However, taxpayers should keep one important point in mind:

A discussion or recommendation by the GST Council does not automatically mean that a new GST rule will become effective on the same day.

Where required, any proposed change may need a formal notification, amendment to the rules, or a legislative amendment before it becomes applicable.

Therefore, taxpayers with an existing GST demand, ITC dispute, or statutory compliance deadline should not postpone their existing compliance obligations simply because they are waiting for the 7 October meeting.


4. No TAN Requirement for Property Purchase from an NRI

From 1 October 2026, the TAN requirement for a resident Individual or HUF purchasing immovable property from an NRI for TDS purposes is being removed.

As per Budget 2026, in such transactions the buyer will be able to deduct and report TDS using their PAN. The seller’s PAN will also need to be quoted in the relevant challan-cum-statement.

In simple terms, the earlier mechanism was:

Resident Individual/HUF + NRI Seller → TAN required

From 1 October 2026, the mechanism will be:

Resident Individual/HUF + NRI Seller → PAN-based TDS compliance

It is important to understand that removal of the TAN requirement does not mean that the TDS obligation itself has been abolished. Applicable TDS provisions will continue to apply, and the buyer must comply with the relevant requirements.

This change is particularly relevant for individuals and HUFs purchasing immovable property from NRI sellers.


5. EPF Wage Ceiling Increased from ₹15,000 to ₹25,000

A significant employee-related development concerns EPFO coverage.

The Government has increased the wage ceiling for mandatory EPFO coverage from:

₹15,000 → ₹25,000 per month

The change is effective from 17 September 2026, meaning its practical implications may start appearing in October payroll and subsequent payroll processing. According to the Government, around 51 lakh additional employees could potentially come under EPFO coverage.

This means that a substantial number of eligible employees earning wages between ₹15,000 and ₹25,000 per month may now come within the statutory EPF framework, subject to the applicable scheme provisions.

For example, if the contribution is calculated at 12% on the revised ceiling of ₹25,000:

₹25,000 × 12% = ₹3,000

Under the earlier ₹15,000 ceiling:

₹15,000 × 12% = ₹1,800

This results in a potential difference of:

₹3,000 − ₹1,800 = ₹1,200

However, the actual EPF contribution for an individual employee will depend on the person’s applicable EPF membership status and the relevant provisions of the scheme.

6. Children’s Aadhaar Mandatory Biometric Update — Free Facility Available Until 30 September

Parents should also take note of an important deadline at the end of September.

According to UIDAI, the Mandatory Biometric Update (MBU) for children aged 5 to 17 years is available free of charge until 30 September 2026.

Therefore, if your child’s mandatory biometric update is still pending, it would be advisable to complete it before 30 September, as the special free-of-cost facility is available only until this date.

One important clarification is that this is not the regular Aadhaar authentication process. It refers specifically to the Mandatory Biometric Update, under which biometric details such as the child’s fingerprints, iris scans, and photograph are updated.


7. Aadhaar Biometric Authentication Required for Subsidised LPG

Another important consumer-related development takes effect from October.

From 1 October 2026, domestic LPG consumers will need to complete Biometric Aadhaar Authentication (BAA) to book refills at the regulated retail selling price along with the applicable subsidy.

Consumers who have not yet completed the authentication can reportedly do so through any of the following options:

  • At the time of LPG delivery
  • At the LPG distributor’s showroom
  • Through the relevant Oil Marketing Company’s mobile application

According to the Government, 27.43 crore consumers, or approximately 89.9%, had already completed the authentication. Those consumers do not need to take any further action.

LPG consumers should therefore check whether their Aadhaar biometric authentication has already been completed.


8. TDS and TCS: Key Points to Keep in Mind During October

TDS and TCS compliance will also remain important for businesses during October. With the transition to the new Income-tax Act, taxpayers must be particularly careful not to confuse FY 2025-26 / AY 2026-27 with FY 2026-27 / Tax Year 2026-27.

Compliance relating to income earned during FY 2025-26 (AY 2026-27) will continue to be governed by the Income-tax Act, 1961.

On the other hand, income relating to FY 2026-27 (Tax Year 2026-27) will fall under the framework of the new Income-tax Act, 2025.

The Income Tax Department has provided clarification regarding this transition.

Therefore, while filing TDS/TCS returns, making challan payments, issuing certificates, or completing other related compliances during October, taxpayers should ensure that they select the correct financial year, tax year, applicable Act, and relevant form.


9. Companies Should Also Review Their MCA/ROC Compliance

For companies, October is not limited to tax-related compliance. Depending on the company’s AGM date and applicable provisions, several MCA/ROC filings may also become due during October.

These may include, where applicable:

  • AOC-4 / AOC-4 XBRL
  • ADT-1
  • MSME-related reporting
  • Other event-based ROC filings

The exact due date is not the same for every company. Certain filings depend on factors such as the actual AGM date and the company’s category.

Companies should therefore review their MCA compliance calendar before the beginning of October and identify all applicable filing deadlines.


10. Do Not Miss Regular GST and Other October Compliance Deadlines

The GST Council meeting is not the only GST-related development to watch in October. Regular GST return filing and tax payment obligations will continue to apply according to their respective due dates.

Taxpayers should not assume that the 7 October GST Council meeting will automatically postpone existing GST return or tax payment deadlines.

Accordingly, GSTR-1, GSTR-3B, CMP-08, and other applicable GST compliances should continue to be completed within their respective due dates, unless the Government officially announces a specific extension.


October 2026: Major Updates at a Glance

Update Important Date Who Is Affected?
TAN requirement removed for resident Individual/HUF purchasing property from an NRI 1 October 2026 NRI property buyers
Aadhaar Biometric Authentication for LPG 1 October 2026 Eligible subsidised LPG consumers
57th GST Council Meeting 7 October 2026 GST taxpayers and businesses
UPI MDR framework 15 October 2026 Specified merchant transactions
PF wage ceiling increased from ₹15,000 to ₹25,000 17 September 2026; impact on October payroll Eligible employees and employers
Free Aadhaar MBU facility for children ends 30 September 2026 Children aged 5–17
Tax Audit Report due date 30 September 2026 Tax audit cases
ITR due date for audit cases 31 October 2026 Tax audit cases

Conclusion

October 2026 is more than just the beginning of a new month. It brings several important compliance requirements, regulatory developments, and financial updates that may affect taxpayers, businesses, employees, and consumers.

Before October begins, it is therefore important to prepare a checklist covering GST returns, tax audit, ITR filing, TDS/TCS, PF, Aadhaar, LPG requirements, MCA/ROC filings, and other applicable compliances.

Keeping track of the relevant dates and completing the required actions on time can help taxpayers and businesses stay up to date with the applicable rules.

FY 2025-26 Tax Audit: 30 September Deadline Remains Unchanged — What CAs Should Do

Tax Audit Deadline 30 September 2026: No Extension Yet — What CAs Should Do Now

With the 30 September 2026 tax audit deadline approaching, Chartered Accountants across India are closely watching for one key development: will the government extend the deadline or will 30 September remain the final date?

As of 21 September 2026, there has been no official CBDT notification announcing an extension.

Current Tax Audit Due Date — No Extension Announced

For FY 2025-26 / AY 2026-27, the current compliance position is:

Compliance Due Date
Tax Audit Report — Form 3CA/3CB-3CD under Section 44AB 30 September 2026
ITR filing for taxpayers subject to audit 31 October 2026
Transfer Pricing cases — Form 3CEB under Section 92E Audit: 31 October 2026 / ITR: 30 November 2026

At present, no notification has been issued changing these dates.

For AY 2026-27, the Income-tax Act, 1961 continues to apply. The new Income-tax Act, 2025 applies prospectively from FY 2026-27. Therefore, the applicable tax-audit provisions, including Section 44AB and the existing Section 271B penalty framework, continue to be relevant for FY 2025-26.

Who Is Required to Get a Tax Audit?

The major tax-audit thresholds can be summarized as follows:

Category Basic Limit Enhanced Limit*
Business under Section 44AB ₹1 crore ₹10 crore
Profession under Section 44AB ₹50 lakh —
Business under Section 44AD where presumptive provisions are not followed ₹2 crore ₹3 crore
Profession under Section 44ADA where presumptive provisions are not followed ₹50 lakh ₹75 lakh

*Enhanced limits are subject to the prescribed conditions relating to cash receipts and payments, including the 5% threshold.

These limits should always be checked against the specific facts and applicable provisions.

Why Is There a Demand for More Time?

Several practical difficulties have contributed to requests from professional bodies for an extension.

1. A Tight Compliance Calendar

For taxpayers who are not covered by tax audit, the ITR deadline was 31 August 2026. The tax-audit report deadline follows on 30 September, while ITR filing for audit cases is generally due on 31 October.

This creates a particularly busy period for tax professionals during August, September and October.

2. Transition to the New Income-Tax Law

FY 2025-26 / AY 2026-27 is an important transition period.

Although the new Income-tax Act, 2025 comes into operation from FY 2026-27, AY 2026-27 remains governed by the Income-tax Act, 1961.

Accordingly, tax audits for FY 2025-26 continue to involve the existing framework, including Forms 3CA/3CB and Form 3CD.

This makes it important for professionals to ensure that the correct provisions and forms are being applied to the correct assessment year.

3. Availability of Forms and Utilities

Professional associations have also highlighted delays concerning the availability of certain return forms and utilities.

Tax audit work involves more than reviewing accounting records. Information reported during the audit often needs to be reconciled with the taxpayer’s return and related schedules.

4. Extensive Reconciliation and Reporting

Tax auditors need sufficient time for activities such as:

  • Reviewing financial information
  • Reconciling accounting and tax records
  • Verifying supporting documents
  • Preparing and reviewing Form 3CD
  • Checking applicable tax positions
  • Collecting confirmations and other evidence
  • Completing professional review and authentication

The Chartered Accountants Association, Jalandhar, has referred to these additional requirements while seeking an extension of the deadline to 31 October 2026.

5. Client Information May Arrive Late

Another practical challenge is the timely receipt of complete information from clients.

Depending on the nature of the business, auditors may need:

  • Final books of accounts
  • Bank statements
  • GST records
  • TDS/TCS information
  • Fixed-asset schedules
  • Loan and interest details
  • Related-party information
  • Stock and inventory records
  • Expense ledgers
  • Confirmations and other audit evidence

Consequently, although the statutory deadline is 30 September 2026, the actual time available to complete an audit may be considerably shorter.

6. Filing the Audit Report Is Not the Final Step

Another important point is the approval process.

After the CA electronically submits the tax-audit report, the taxpayer is required to approve it through the income-tax e-filing account.

Therefore, leaving the entire process until 30 September can create additional risk if there are portal problems, approval delays or other technical issues.

Practical Approach: Work With 30 September as the Deadline

The safest approach for practitioners is to plan on the basis that 30 September 2026 remains the applicable deadline.

If the CBDT subsequently announces an extension, it can provide additional breathing room. Until then, an extension should not be treated as part of the working plan.

What Could Happen If the Deadline Is Missed?

Failure to complete a tax audit within the applicable time limit can have financial and compliance consequences.

Section 271B Penalty

The existing Section 271B framework provides for a penalty of:

0.5% of turnover or gross receipts, subject to a maximum of ₹1,50,000.

However, Section 273B provides relief where the taxpayer can establish reasonable cause for the failure.

Such relief should not be assumed automatically. Appropriate evidence and documentation of the circumstances are important.

Possible Consequences for Delayed ITR Filing

A delayed tax audit can also affect the subsequent ITR filing process.

Depending on the taxpayer’s circumstances, delayed filing may result in interest under Section 234A on unpaid tax and may have implications for the carry-forward of certain losses.

9-Day Action Plan for CAs

With limited time remaining, practitioners can consider the following workflow:

1. Prioritize the Pending Client List

Review all pending audits immediately and categorize clients according to complexity, outstanding information and the amount of work remaining.

2. Resolve Reconciliation Issues Early

Focus on major reconciliation areas such as:

  • AIS
  • Form 26AS
  • GST data
  • GSTR-2B
  • GSTR-3B
  • TDS/TCS records

These issues can consume significant time if left until the final days.

3. Complete Supporting Documentation in Parallel

Form 3CD annexures, management representations and supporting documents should be completed alongside the audit instead of waiting until the final review stage.

4. File Reports as They Become Ready

Where an audit is complete, consider filing the report promptly rather than accumulating completed reports for the final two days.

5. Identify High-Risk Delays

If a client is unlikely to provide the required information or complete the process on time, identify the issue immediately and maintain proper documentation regarding the circumstances.

6. Record Portal Problems

If technical difficulties occur on the e-filing portal, maintain appropriate records such as screenshots, error messages and relevant timestamps.

Such documentation may be useful when explaining the circumstances behind a delay.

Frequently Asked Questions

Has the tax audit deadline been extended to 31 October 2026?

No official extension has been announced as of 21 September 2026. The currently applicable tax-audit deadline remains 30 September 2026.

Practitioners should verify the latest CBDT notification before relying on any extension.

Is this the same extension given for AY 2025-26?

No. The extension applicable to AY 2025-26 was part of the previous assessment year’s compliance cycle.

For AY 2026-27, the currently applicable tax-audit deadline is 30 September 2026, unless the CBDT announces otherwise.

Should taxpayers wait for an extension before completing the audit?

It is prudent to continue preparing on the assumption that 30 September 2026 is the deadline.

If an official extension is subsequently announced, taxpayers and professionals can adjust their timelines accordingly.

Final Takeaway

At present, the 30 September 2026 tax-audit deadline remains unchanged.

With only a limited number of working days available, CAs should focus on completing pending audits, obtaining client information, resolving reconciliations and filing reports as soon as they are ready.

Plan for 30 September. Treat any future extension as additional time rather than something to depend upon.

Disclaimer: This article is intended for general informational purposes and reflects publicly available information as of 21 September 2026. Taxpayers and professionals should verify the latest CBDT notifications and applicable provisions before taking compliance decisions. For specific cases, consult a qualified tax professional.

57th GST Council Meeting: New Schedule and Important GST Changes Expected

The 57th GST Council meeting, which was originally planned for 12 September 2026, has now been rescheduled to 7 October 2026 in New Delhi. The earlier date coincided with the BRICS Leaderan


s’ Summit scheduled to take place in New Delhi on 12–13 September.

The October meeting is expected to be significant as the Council may discuss several GST process and compliance reforms following the major GST rate rationalisation carried out in 2025.

Finance Minister Nirmala Sitharaman has indicated that the meeting is likely to consider process-related reforms, including e-invoicing and input tax credit (ITC) provisions. The government has also sought suggestions from industry stakeholders and tax professionals regarding provisions that may be causing unnecessary complexity or inconsistencies.

However, taxpayers should keep one important point in mind:

Issues being discussed or proposed before the GST Council are not changes in law unless they are subsequently implemented through the required legal, notification or rule-making process.


ITC When the Supplier Fails to Pay Tax — Section 16(2)(c)

One of the key concerns under discussion is the difficulty faced by a genuine purchaser when the supplier does not pay the applicable GST to the Government.

Under the existing provisions of Section 16(2)(c), payment of the tax charged on a supply to the Government is one of the conditions associated with claiming ITC, subject to the applicable statutory framework.

This can create difficulties for a bona fide recipient who has:

  • received the goods or services;
  • obtained a valid tax invoice;
  • made payment to the supplier;
  • fulfilled the other applicable ITC requirements;

but the supplier has subsequently failed to properly report or deposit the tax.

Industry representatives have therefore been seeking a mechanism that could protect a bona fide buyer from losing legitimate ITC solely because of a supplier’s default. This issue has been highlighted in discussions and reports ahead of the Council meeting.


Review of Blocked ITC Under Section 17(5)

Another major area of discussion is blocked input tax credit under Section 17(5).

The current provision restricts ITC on certain specified goods and services, subject to prescribed exceptions. These include areas such as certain motor vehicles, food and beverages, health-related services, club memberships and other specified categories.

Industry stakeholders have been requesting a review of some of these restrictions.

Although motor vehicle-related ITC provisions may come up for discussion, taxpayers should not assume that ITC will automatically become available after 7 October. Any change would require the appropriate legal process following a Council recommendation.


Inverted Duty Structure and Refund of Accumulated ITC

The inverted duty structure is another important issue that may receive attention.

An inverted duty situation arises when the GST rate applicable to inputs is higher than the GST rate on the final outward supply. This can result in the accumulation of ITC and create a working-capital burden for businesses.

Industry has been requesting changes to the refund mechanism and treatment of accumulated ITC.

Reports ahead of the meeting have identified refund-related provisions and inverted-duty issues among the matters that could potentially be considered.

This issue can be particularly important for businesses where:

GST on Inputs > GST on Outward Supplies

resulting in a continuous accumulation of unused credit.


GST Registration Process — Proposed Simplification

GST registration is another significant area forming part of the broader process-reform discussion.

Businesses have raised concerns regarding:

  • repeated submission of documents;
  • differences in requirements between jurisdictions;
  • physical verification procedures;
  • delays in registration;
  • difficulties in cancellation;
  • additional scrutiny faced by genuine businesses.

The Government has also been working towards a more standardised registration mechanism for larger businesses, particularly businesses having monthly ITC exceeding ₹2.5 lakh.


Simplification of GST Cancellation

The GST registration cancellation process is also expected to be considered as part of the broader reform exercise.

The objective of such reforms would be to make registration and cancellation procedures more streamlined and automated, helping genuine taxpayers avoid unnecessary procedural delays.


E-Invoicing — Possible Expansion and Process Reforms

E-invoicing is another important subject because the Finance Minister has specifically referred to it as part of the GST process-reform agenda for the October meeting.

There has been discussion regarding the possibility of extending e-invoicing to a broader group of taxpayers, including consideration of its applicability to composition taxpayers.

The GST Council may therefore examine further expansion of the e-invoicing framework along with related procedural improvements.


Utilisation of ITC Across Multiple GST Registrations

Another issue that has attracted industry attention is the treatment of unused ITC across different GST registrations of the same business.

For instance, a company may have GST registrations in:

Delhi | Haryana | Maharashtra | Punjab

It may have significant unused ITC under one registration while another registration has an output tax liability.

Under the existing GST framework, the electronic credit ledger of one State registration cannot simply be transferred to another State registration.

Industry has therefore been seeking possible mechanisms to deal with stranded or unutilised ITC across multiple registrations.

Greater flexibility in the utilisation of surplus ITC has been identified in reports as one of the issues that could be considered by the Council.


Online Gaming — Resolution of Legacy GST Issues

Online gaming is another area involving significant legacy disputes and litigation.

Industry stakeholders have been seeking possible solutions for legacy tax issues and ongoing disputes relating to the earlier GST treatment of online gaming.

Reports ahead of the meeting have identified the regularisation of legacy positions in the online gaming sector as one of the concerns that industry may place before the GST Council.


Key Takeaway for Taxpayers

The 57th GST Council meeting on 7 October 2026 could bring discussions on several important GST process reforms, including ITC rules, blocked credits, inverted-duty refunds, registration and cancellation, e-invoicing, cross-registration ITC utilisation and legacy online gaming issues.

However, taxpayers should distinguish between industry representations, proposals and Council discussions and actual changes in GST law.

Any proposal will become applicable only after the necessary recommendation, notification, amendment or rule-making process is completed.

“The GST Council may consider ways to resolve or regularise legacy disputes and pending litigation related to the online gaming sector.”


Compensation Cess — Issue of Stranded ITC

Another significant issue emerging after the GST rate rationalisation is the treatment of unused input tax credit related to compensation cess.

Industry stakeholders have raised concerns regarding compensation cess credit that remains embedded in existing inventory, particularly in sectors such as automobiles.

According to reporting by The Indian Express, automobile dealers have accumulated considerable ITC associated with the now-discontinued compensation cess and are seeking clarity on how this credit should be treated.

The issue is therefore particularly relevant to:

Automobile Dealers + Tobacco Businesses + Other Sectors Affected by the Transition from Compensation Cess

“The treatment of unutilised compensation-cess credit remains an important issue that industry expects the GST Council to examine.”


Another Key Issue: GST Litigation

The October meeting is increasingly being viewed as a process-reform-focused meeting, with reducing unnecessary GST litigation forming an important part of the broader reform agenda.

Finance Minister Nirmala Sitharaman has invited industry stakeholders and professionals to highlight GST provisions that may be creating unnecessary complexity, inconsistencies or anomalies.

The objective is to identify areas where procedural improvements or clarification could make GST compliance simpler and potentially reduce avoidable disputes and litigation.