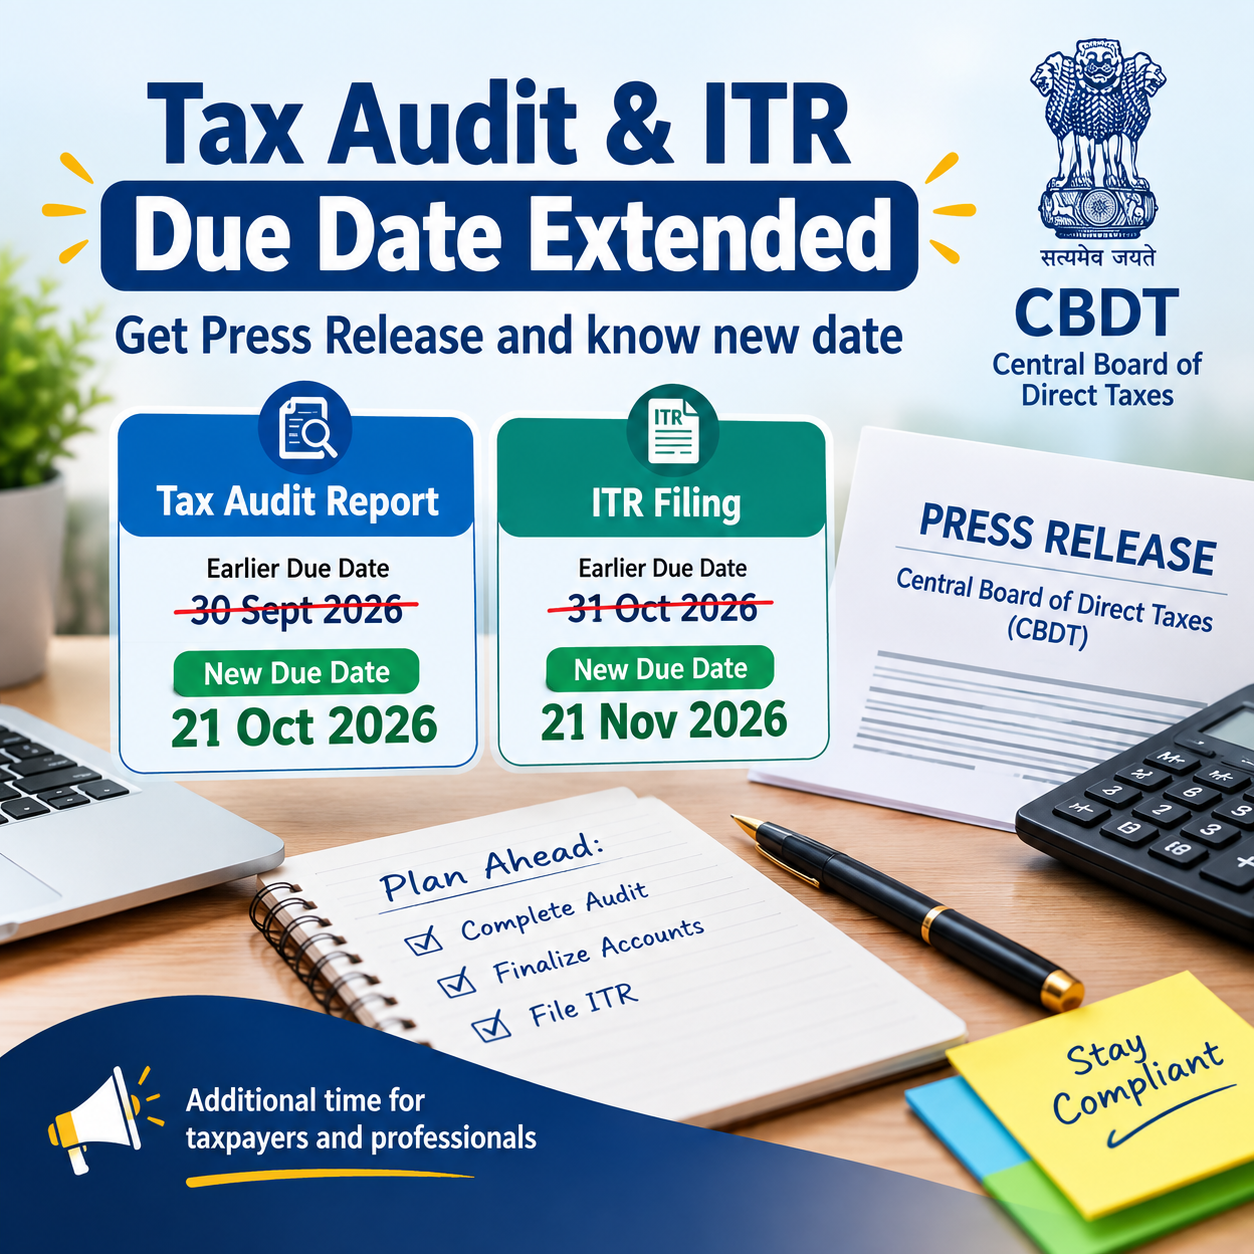
The Central Board of Direct Taxes (CBDT) has announced a significant extension of the due dates for filing the Tax Audit Report and Income Tax Return for Assessment Year 2026-27. The extension applies to taxpayers who fall under the specified audit category covered by Section 139(1) of the Income-tax Act, 1961. The CBDT issued its press release on 28 September 2026, confirming an extension of the applicable deadlines. The revised timelines are intended to give the affected taxpayers and tax professionals additional time to complete the audit formalities and file their income tax returns.
The Central Board of Direct Taxes (CBDT) has announced an extension of the due date for filing the Return of Income for Assessment Year 2026-27 for taxpayers covered under S. No. 2 of the Table below Explanation 2 to Section 139(1) of the Income-tax Act, 1961.
For such taxpayers, the income tax return filing deadline has been extended from 31 October 2026 to 21 November 2026. Consequently, the specified date for furnishing the tax audit report for AY 2026-27 has also been extended from the earlier date to 21 October 2026.
The CBDT has issued a press release confirming these revised deadlines.
Tax Audit Deadline Revised
According to the CBDT press release, the “specified date” for submitting the audit report under the Income-tax Act, 1961 has been extended for the applicable category of taxpayers.
The original deadline was:
30 September 2026
The new deadline announced by CBDT is:
21 October 2026
Accordingly, taxpayers covered under the specified category will have additional time to complete and furnish their tax audit reports.
The change is especially relevant to taxpayers whose accounts are required to undergo tax audit and to Chartered Accountants responsible for preparing, finalising, and uploading the related audit reports.
Income Tax Return Deadline Also Revised
CBDT has simultaneously extended the Income Tax Return filing deadline for AY 2026-27 for taxpayers falling under the specified category.
The previous deadline was:
31 October 2026
The revised deadline is:
21 November 2026
Therefore, the extension provides additional time for both completion of the audit-report requirements and subsequent filing of the income tax return for the taxpayers covered by the announcement.
Extension Applies Only to the Specified Category
Taxpayers should note that the CBDT announcement does not constitute a blanket extension for all taxpayers.
The press release specifically covers persons referred to at Serial No. 2 in the table under Explanation 2 to Section 139(1) of the Income-tax Act, 1961.
Therefore, taxpayers should verify whether their particular case falls within this specified category before relying on the revised deadlines.
Revised Tax Audit Report Date
The CBDT press release clearly provides that the “specified date” for furnishing the audit report has been shifted from 30 September 2026 to 21 October 2026.
In practical terms, the audit-report deadline is extended first, followed by the revised ITR filing deadline applicable to the specified category.
Particulars
Earlier Deadline
Revised Deadline
Tax Audit Report – specified date
30 September 2026
21 October 2026
ITR for AY 2026-27 – specified category
31 October 2026
21 November 2026
What Additional Time Can Be Used For
For taxpayers covered by the CBDT announcement, the extended timeline can help provide additional time to:
Complete the tax audit process
Finalise books and financial records
Complete audit-related disclosures and reporting
Furnish and upload the audit report
Verify tax calculations and liabilities
Prepare and review the Income Tax Return
Reconcile applicable tax-related information before filing the return
At the same time, taxpayers should remember that this extension is not a universal extension applicable to every taxpayer.
Separate Formal Order or Notification
The CBDT press release also indicates that a separate formal order/notification will be issued to give effect to the revised deadlines.
Taxpayers and tax professionals should therefore refer to the formal CBDT order or notification as well for the detailed operative provisions of the extension.
Key Points at a Glance
The key dates announced in the CBDT press release dated 28 September 2026 for the specified audit category for AY 2026-27 are:
Tax Audit Report:
30 September 2026 → 21 October 2026
Income Tax Return:
31 October 2026 → 21 November 2026
The revised dates apply specifically to the persons covered by the category identified in the CBDT announcement. Therefore, taxpayers should first confirm their eligibility for the extension rather than assuming that the revised deadlines apply to all taxpayers.
Tax Audit Late Fee FY 2025-26: Will It Be ₹75,000 or ₹1,50,000?
There is significant confusion among taxpayers, businesses and tax professionals about the penalty or fee applicable when the Tax Audit Report for FY 2025-26 (AY 2026-27) is filed after the prescribed due date.
The confusion mainly stems from the introduction of the Income-tax Act, 2025, which became effective from 1 April 2026. The new law introduces a different fee mechanism for failure to complete the required tax audit and submit the audit report.
Under the new provisions, the prescribed amounts are:
₹75,000 where the delay is up to one month; and
₹1,50,000 where the delay exceeds one month.
This raises an important question:
If the tax audit report relating to FY 2025-26 is submitted late, will the taxpayer be liable to pay ₹75,000 or ₹1,50,000?
The answer is No — the new ₹75,000 / ₹1,50,000 fee does not apply to FY 2025-26
The reason is that FY 2025-26 corresponds to AY 2026-27, and this year continues to be governed by the Income-tax Act, 1961.
The fact that the audit report may actually be submitted after 1 April 2026 does not by itself shift the audit to the new law.
The new fee provisions apply to Tax Year 2026-27 and later tax years.
Therefore, it is essential to distinguish between FY 2025-26 / AY 2026-27 and Tax Year 2026-27.
1. Understanding the Transition Between the Two Laws
The primary source of confusion is the transition from the Income-tax Act, 1961 to the Income-tax Act, 2025.
FY 2025-26
FY 2025-26 covers income earned from:
1 April 2025 to 31 March 2026
This financial year corresponds to:
AY 2026-27
It continues to be governed by:
Income-tax Act, 1961
Accordingly, the tax audit requirement remains covered by:
Section 44AB
The applicable tax audit forms continue to be:
Form 3CA / Form 3CB along with Form 3CD, wherever applicable.
Tax Year 2026-27
The new tax year covers income earned from:
1 April 2026 to 31 March 2027
This period falls under:
Income-tax Act, 2025
The corresponding tax audit provision is:
Section 63
The tax audit report under the new framework is:
Form No. 26
The new audit provisions and the revised fee mechanism therefore need to be considered separately for Tax Year 2026-27.
2. What Is the New Tax Audit Fee?
Under the Income-tax Act, 2025, the new fee provision is contained in Section 428.
Where a person fails to have the accounts audited and furnish the required audit report in accordance with Section 63, the prescribed fee is:
Delay of up to one month
₹75,000
Delay of more than one month
₹1,50,000
Thus, the new law provides a two-level fee structure depending on the period of delay.
It is also important not to confuse these amounts with the earlier penalty provisions. The new framework treats this amount as a fee, whereas the earlier law provided for a penalty.
3. Is the ₹75,000 Fee Applicable to FY 2025-26?
No.
This is the key point taxpayers need to understand.
Consider a taxpayer who is required to undergo tax audit for:
FY 2025-26 / AY 2026-27
Even if the tax audit report is submitted after 1 April 2026, the new Section 428 fee of ₹75,000 or ₹1,50,000 does not automatically become applicable.
The reason is that the audit relates to FY 2025-26, a year covered by the earlier Income-tax Act.
The transitional provisions ensure that the relevant provisions of the old law continue to apply to such years.
4. What Is the Income Tax Department’s Position?
The Income Tax Department has clarified the treatment of tax audit reports during the transition between the two Acts.
For FY 2025-26, the Tax Audit Report:
relates to AY 2026-27;
continues to fall under the Income-tax Act, 1961;
is required to be furnished using Form 3CA / Form 3CB / Form 3CD, as applicable; and
remains governed by the provisions of the old Act even where the report is uploaded after 1 April 2026.
Therefore, the applicable law is not determined simply by looking at the date on which the audit report is actually uploaded.
The crucial factor is the financial year or tax year to which the audit relates.
5. What Happens If the FY 2025-26 Tax Audit Is Delayed?
For FY 2025-26, the consequences of failure to comply with the tax audit requirement continue to be examined under the Income-tax Act, 1961.
The relevant provision is:
Section 271B
Section 271B provides for a penalty where a taxpayer fails to get the accounts audited or fails to furnish the audit report as required under Section 44AB.
The penalty may be calculated as the lower of:
0.5% of total sales, turnover or gross receipts
or
₹1,50,000
Accordingly, the maximum penalty under the old provision is:
₹1,50,000
However, this should not be confused with the new ₹75,000 / ₹1,50,000 fee structure introduced under the Income-tax Act, 2025.
The two provisions operate under different laws and apply to different tax years.
6. Penalty under Section 271B is NOT the same as the new late fee
This distinction is extremely important.
Old Act — FY 2025-26
The consequence is:
Penalty under Section 271B
It is not an automatic fixed late fee of ₹75,000.
The Assessing Officer may impose the penalty subject to the provisions of the Act.
The maximum is generally:
0.5% of turnover/gross receipts or ₹1.50 lakh, whichever is lower.
There is also an important protection under:
Section 273B
Section 273B provides that penalty under certain provisions, including Section 271B, may not be imposed where the taxpayer proves that there was reasonable cause for the failure.
Therefore, for FY 2025-26, the taxpayer should not mechanically calculate:
“Tax audit late by one month = ₹75,000.”
That is not the correct position.
7. What changes from Tax Year 2026-27?
Now consider a tax audit relating to:
Tax Year 2026-27
This period starts on:
1 April 2026
and ends on:
31 March 2027
This is governed by the:
Income-tax Act, 2025
The tax audit requirement is under:
Section 63
and the new tax audit report is:
Form No. 26
For failure to get the accounts audited and furnish the report within the prescribed time, the new fee under Section 428 applies.
Therefore:
Particulars
Tax Year 2026-27 onwards
Delay up to one month
₹75,000
Delay beyond one month
₹1,50,000
This is the new regime.
8. Is ₹75,000 charged every month?
No.
This is another important point.
The provision does not say:
₹75,000 per month.
It provides:
Up to one month of delay
₹75,000
Thereafter
₹1,50,000
So it is not a recurring ₹75,000 every month.
For example, if the tax audit report is delayed by:
10 days → ₹75,000
20 days → ₹75,000
30 days → ₹75,000
More than one month → ₹1,50,000
The provision should therefore not be interpreted as a monthly late fee.
9. Example — Tax Year 2026-27
Suppose a taxpayer is required to furnish the tax audit report by:
30 September 2027
Case 1 — Report filed on 10 October 2027
Delay = 10 days
Applicable fee:
₹75,000
Case 2 — Report filed on 25 October 2027
Delay = 25 days
Applicable fee:
₹75,000
Case 3 — Report filed on 5 November 2027
Delay exceeds one month.
Applicable fee:
₹1,50,000
Therefore, once the delay crosses the one-month threshold, the higher fee becomes applicable.
10. Example for FY 2025-26
Let us consider a practical example for the current tax-audit cycle.
Assume the taxpayer has:
Financial Year: FY 2025-26
Tax Audit Report Due Date: 30 September 2026
Now suppose the audit report is submitted on:
15 October 2026
The taxpayer should not conclude:
“The report is delayed by 15 days, so I must pay ₹75,000.”
That conclusion would be incorrect.
The Section 428(c) fee introduced under the new Income-tax Act, 2025 does not become applicable to the FY 2025-26 audit simply because the report is uploaded after 1 April 2026.
The audit for FY 2025-26 continues to be governed by the provisions of the Income-tax Act, 1961.
Accordingly, the relevant consequence is considered under the Section 271B penalty framework, subject to applicable provisions, including the reasonable-cause protection available under Section 273B.
11. Why Is There Confusion About the Tax Audit Late Fee?
The confusion surrounding the ₹75,000 and ₹1,50,000 amounts can mainly be attributed to three factors.
Reason 1 — The New Income-tax Act Became Effective From 1 April 2026
The Income-tax Act, 2025 came into effect from 1 April 2026.
As a result, many taxpayers assume that every tax compliance action performed after this date must automatically be governed by the new law.
However, this interpretation is not correct.
The transition provisions determine which law applies to a particular tax year.
Reason 2 — Section 428 Introduces a ₹75,000 Fee
Section 428 of the new Act specifies amounts of:
₹75,000
and
₹1,50,000
for the applicable tax-audit default.
Because these figures are clearly mentioned in the new law, several articles and social-media discussions have described the situation simply as:
“The tax audit late fee is now ₹75,000.”
However, that statement does not provide the complete picture.
The more accurate position is:
The ₹75,000 / ₹1,50,000 tax-audit fee mechanism under the new Act applies to Tax Year 2026-27 and subsequent tax years. It does not become applicable to the FY 2025-26 tax audit merely because the report is filed after 1 April 2026.
Reason 3 — FY 2025-26 and Tax Year 2026-27 Are Being Mixed Up
A major source of misunderstanding is the failure to distinguish between the two periods.
FY 2025-26
1 April 2025 to 31 March 2026
Corresponding assessment year:
AY 2026-27
Applicable law:
Income-tax Act, 1961
Tax Year 2026-27
1 April 2026 to 31 March 2027
Applicable law:
Income-tax Act, 2025
The new provisions, including the revised tax-audit fee mechanism, apply to this new tax year.
Therefore, identifying the year to which the audit relates is essential before determining the applicable late-compliance provisions.
12. Old Tax Audit Rules vs New Tax Audit Rules
The key differences can be summarized as follows:
Particulars
FY 2025-26 / AY 2026-27
Tax Year 2026-27 onwards
Applicable Law
Income-tax Act, 1961
Income-tax Act, 2025
Tax Audit Provision
Section 44AB
Section 63
Audit Report
Form 3CA / 3CB + Form 3CD
Form 26
Consequence of Default
Penalty under Section 271B
Fee under Section 428
First Amount
Not prescribed as a fixed ₹75,000 fee
₹75,000
Higher Amount
Maximum penalty can reach ₹1.50 lakh
₹1,50,000
Reasonable Cause
Section 273B applies to Section 271B penalty
New fee mechanism operates differently
Mandatory ₹75,000 Fee
Not applicable
Applicable
₹1,50,000 Fee After One Month
Not applicable as a Section 428 fee
Applicable
The table highlights an important point: although the figure of ₹1.50 lakh appears under both frameworks, the nature and manner of its application are different.
13. Is ₹1.50 Lakh Automatically Payable Under Section 271B?
No.
This is another important point that taxpayers should understand.
Under the old law, Section 271B provides for a penalty calculated as:
0.5% of total sales, turnover or gross receipts
or
₹1.50 lakh, whichever is lower.
Therefore, ₹1.50 lakh represents the maximum statutory limit, and it is not automatically imposed in every case of delayed tax audit.
Example 1 — Turnover of ₹50 lakh
Suppose the taxpayer has turnover of:
₹50 lakh
The calculation would be:
0.5% × ₹50 lakh = ₹25,000
Therefore, based on the statutory formula, the penalty would be capped at the lower applicable amount rather than automatically becoming ₹1.50 lakh.
Example 2 — Turnover of ₹10 crore
Suppose turnover is:
₹10 crore
Then:
0.5% × ₹10 crore = ₹5 lakh
Since Section 271B provides a maximum limit of ₹1.50 lakh, the statutory ceiling would be:
₹1.50 lakh
Thus, under Section 271B, ₹1.50 lakh is the maximum limit and not an automatic penalty amount.
14. New Act Introduces a Different Fee Structure
The mechanism under the new Section 428 is substantially different from the earlier penalty system.
Under the new provision, the prescribed fee is:
₹75,000
where the delay is up to one month,
and:
₹1,50,000
where the delay extends beyond one month.
Unlike the earlier Section 271B framework, this amount is not determined by applying a percentage to turnover.
This represents an important change for taxpayers.
For instance, consider a small business having turnover of only ₹20 lakh. If the business is required to undergo tax audit under the new Act and the audit report is delayed beyond one month, the applicable statutory fee can still be:
₹1,50,000
This is because the new fee is prescribed as a fixed amount and is not linked to the taxpayer’s turnover.
15. Can Reasonable Cause Avoid the New Fee?
Taxpayers and professionals should carefully distinguish between the old and new provisions on this issue.
Under the earlier Section 271B framework, the levy is in the nature of a penalty. Section 273B provides relief where the taxpayer is able to establish a reasonable cause for the failure.
The new Section 428 mechanism, however, is expressly framed as a fee.
Therefore, it should not be assumed that the new ₹75,000 / ₹1,50,000 fee will automatically receive the same treatment as a penalty imposed under Section 271B.
The nature of the levy itself has changed.
Accordingly, for Tax Year 2026-27 onwards, taxpayers should carefully consider the requirements of Section 428 instead of assuming that the earlier reasonable-cause provisions will operate in exactly the same way.
16. What Rules Apply During the Current Tax Audit Season?
For the present tax-audit cycle, the relevant period is:
FY 2025-26 / AY 2026-27
The currently applicable due date for the tax audit report is:
30 September 2026
The Income Tax Department has clarified that the tax audit relating to FY 2025-26 continues to be governed by the Income-tax Act, 1961.
Accordingly, the applicable forms continue to include:
Form 3CA, wherever applicable;
Form 3CB, wherever applicable; and
Form 3CD.
Therefore, the following statement would be incorrect:
“Since the new Act came into force on 1 April 2026, every late tax audit from FY 2025-26 will attract a ₹75,000 fee.”
The applicability of the new fee cannot be determined merely by looking at the date on which the audit report is uploaded.
17. What If CBDT Extends the Tax Audit Due Date?
Another practical consideration is whether the prescribed due date is subsequently extended.
If the CBDT officially extends the FY 2025-26 tax-audit deadline, the compliance position would have to be determined by taking the officially extended due date into account.
Until such an extension is formally notified, taxpayers should follow the applicable statutory deadline.
For the current FY 2025-26 tax-audit cycle, the applicable due date is presently:
30 September 2026
18. Easy Way to Understand the Two Regimes
The entire transition can be remembered using the following comparison:
FY 2025-26
Income-tax Act, 1961
↓ Section 44AB
↓ Form 3CA / 3CB + Form 3CD
↓ Section 271B penalty
This distinction is important because the new fee mechanism should not be applied retrospectively to the FY 2025-26 tax audit.
19. Frequently Asked Questions
Q1. Will a ₹75,000 late fee apply to FY 2025-26 tax audit?
No.
The ₹75,000 fee under Section 428 does not apply to the FY 2025-26 tax audit simply because the report is submitted after 1 April 2026.
Q2. Is the amount ₹15,000 or ₹1,50,000 under the new provision?
The applicable higher amount is:
₹1,50,000
It is not ₹15,000.
Q3. From when does the ₹75,000 fee apply?
The ₹75,000 fee is part of the new regime applicable to Tax Year 2026-27 onwards, where the delay in furnishing the tax audit report is up to one month.
Q4. What happens when the delay is more than one month?
Under the new Section 428 mechanism, the prescribed fee becomes:
₹1,50,000
Q5. Is ₹75,000 payable for every month of delay?
No.
The provision does not impose ₹75,000 separately for every month.
The structure provides for ₹75,000 for delay up to one month and ₹1,50,000 thereafter.
Q6. Which provision applies to FY 2025-26?
For FY 2025-26 / AY 2026-27, the Income-tax Act, 1961 continues to govern the tax audit.
The consequences of non-compliance are therefore considered under Section 271B, subject to the applicable provisions of the old Act, including Section 273B.
Q7. Which audit forms are required for FY 2025-26?
For FY 2025-26, the applicable forms remain:
Form 3CA / Form 3CB along with Form 3CD, as applicable.
Q8. What form applies under the new tax-audit regime?
For Tax Year 2026-27 onwards, the new tax-audit report is:
Form No. 26
The new Form 26 replaces the earlier tax-audit reporting structure under the new framework.